1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial report Sega Sammy Holdings
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial reportSega Sammy Holdings
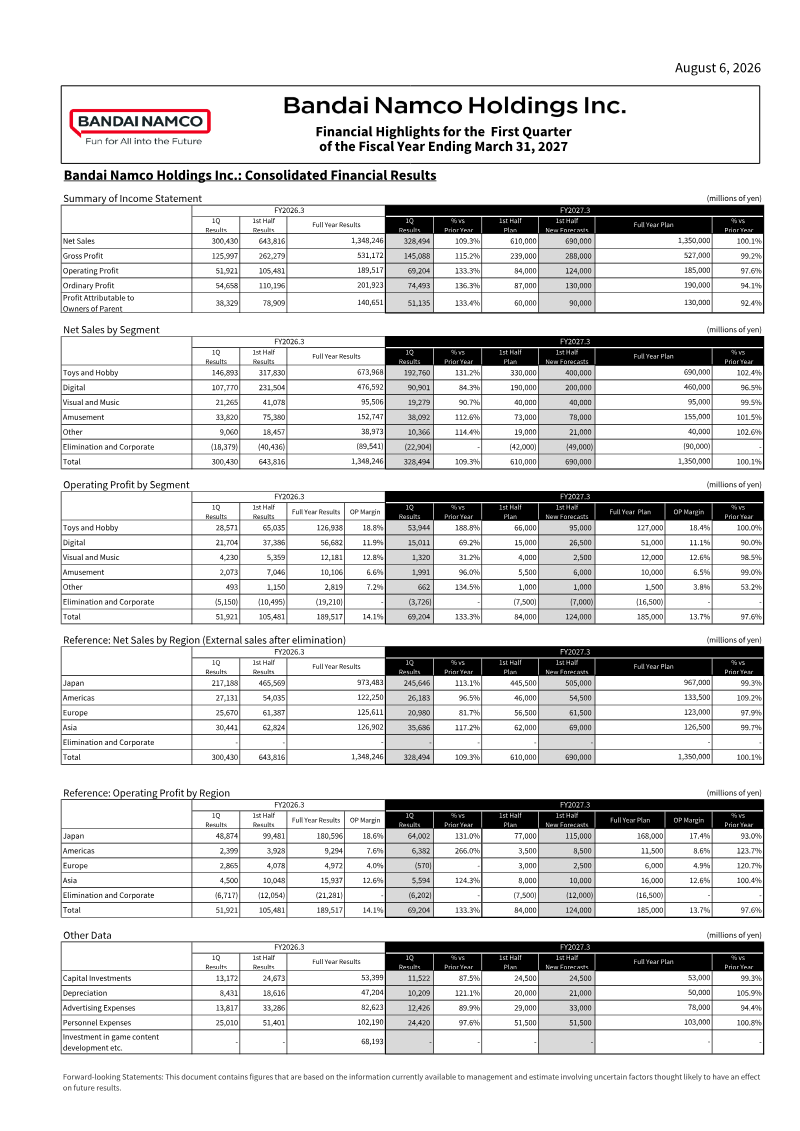
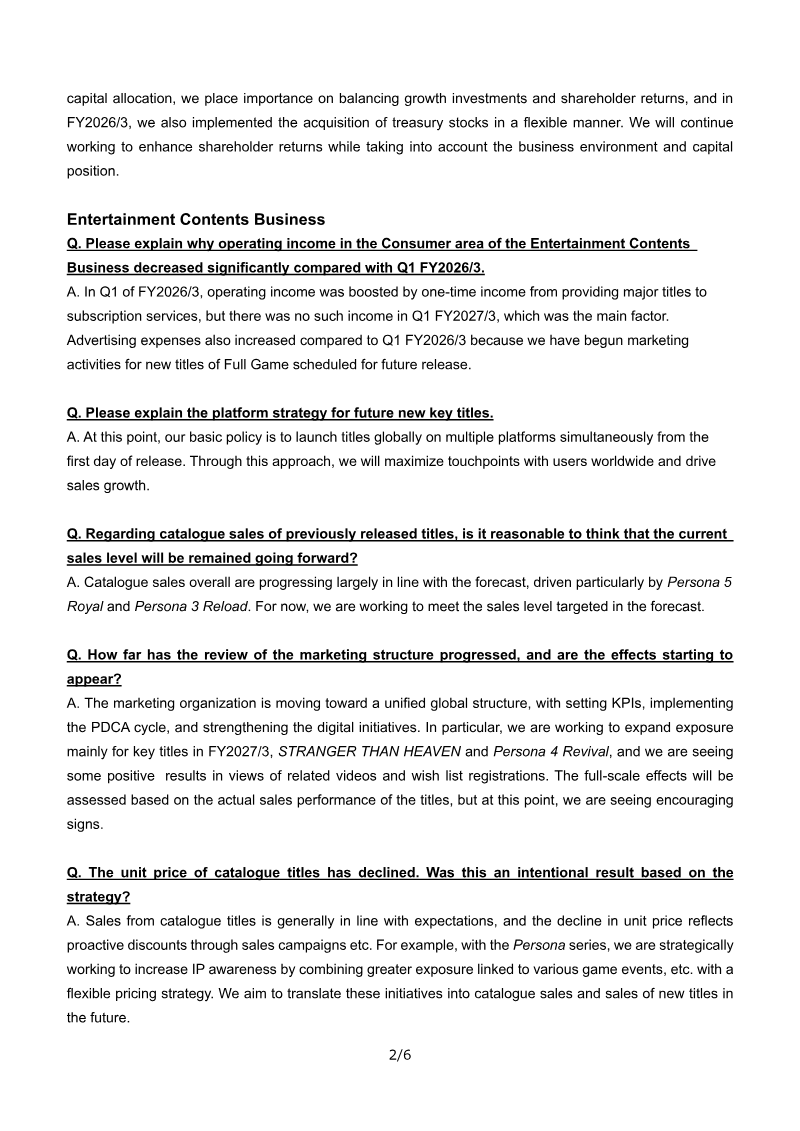
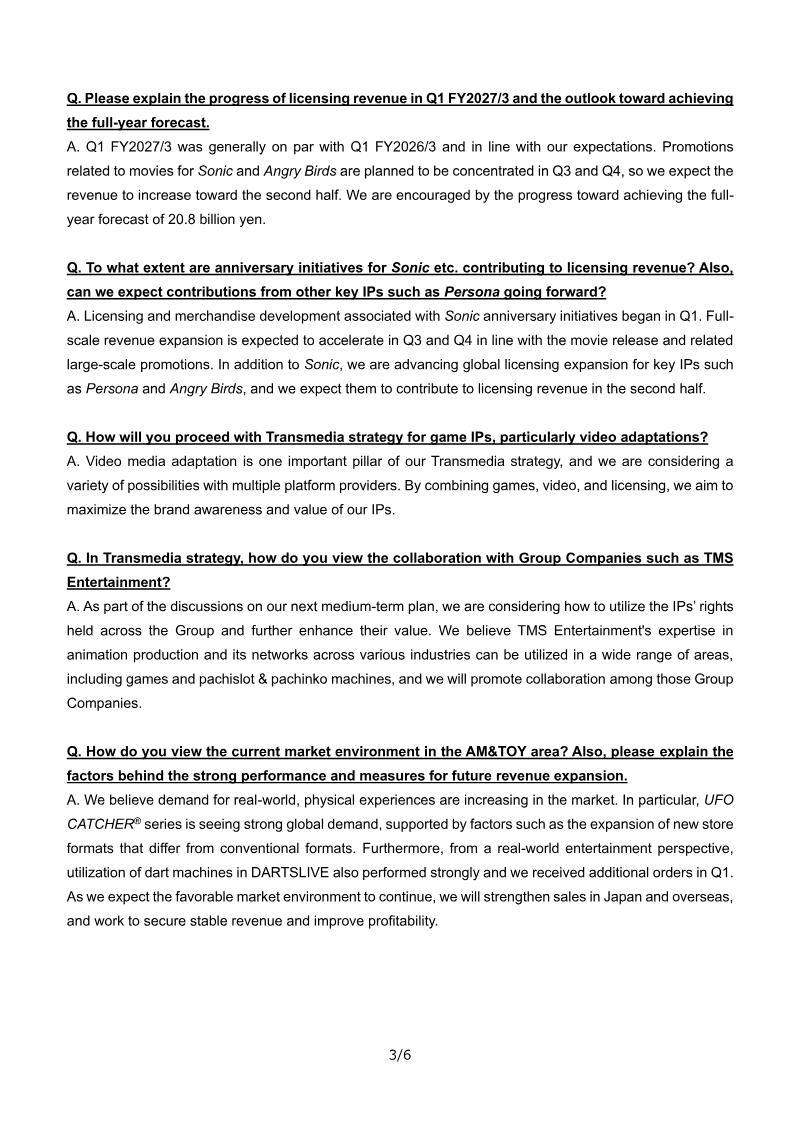
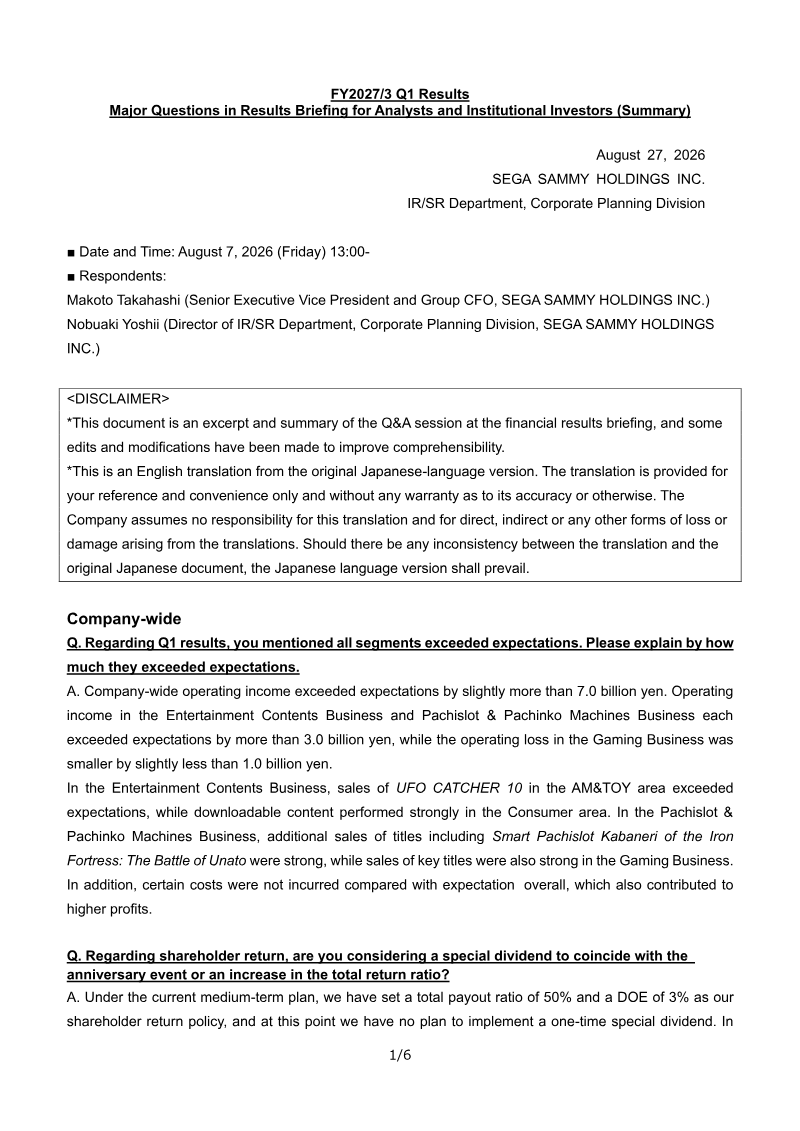
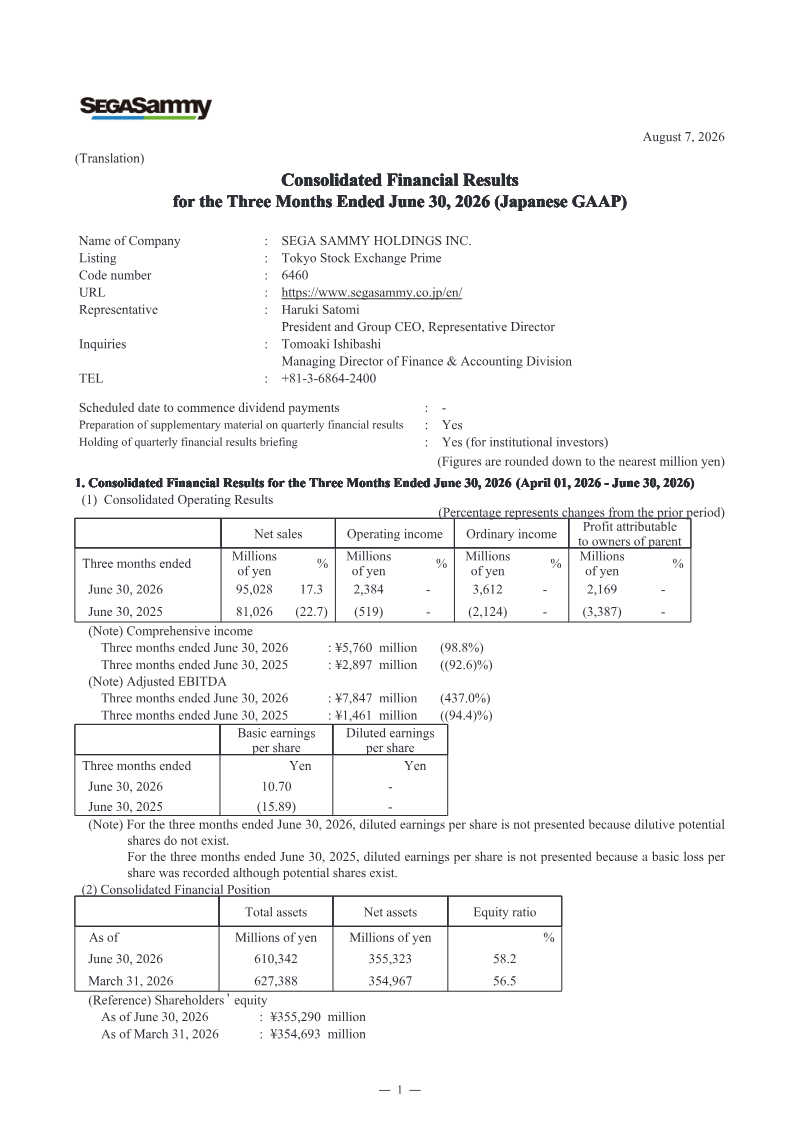
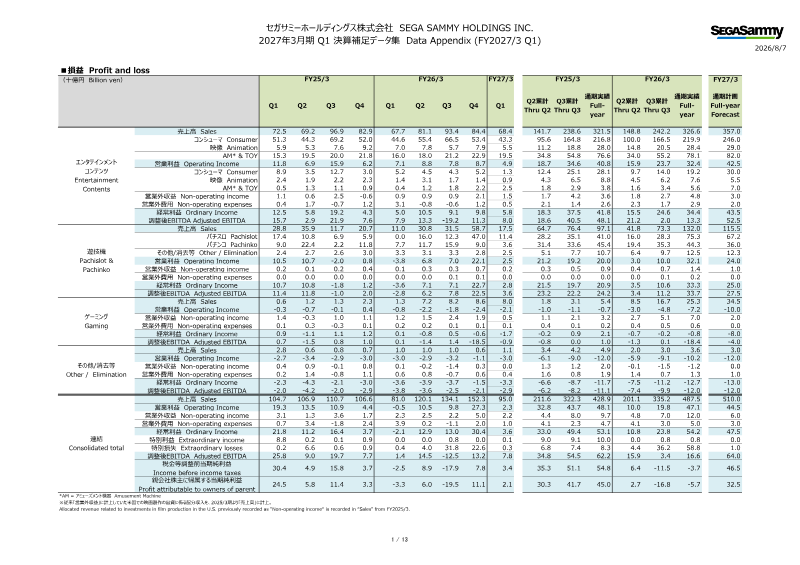
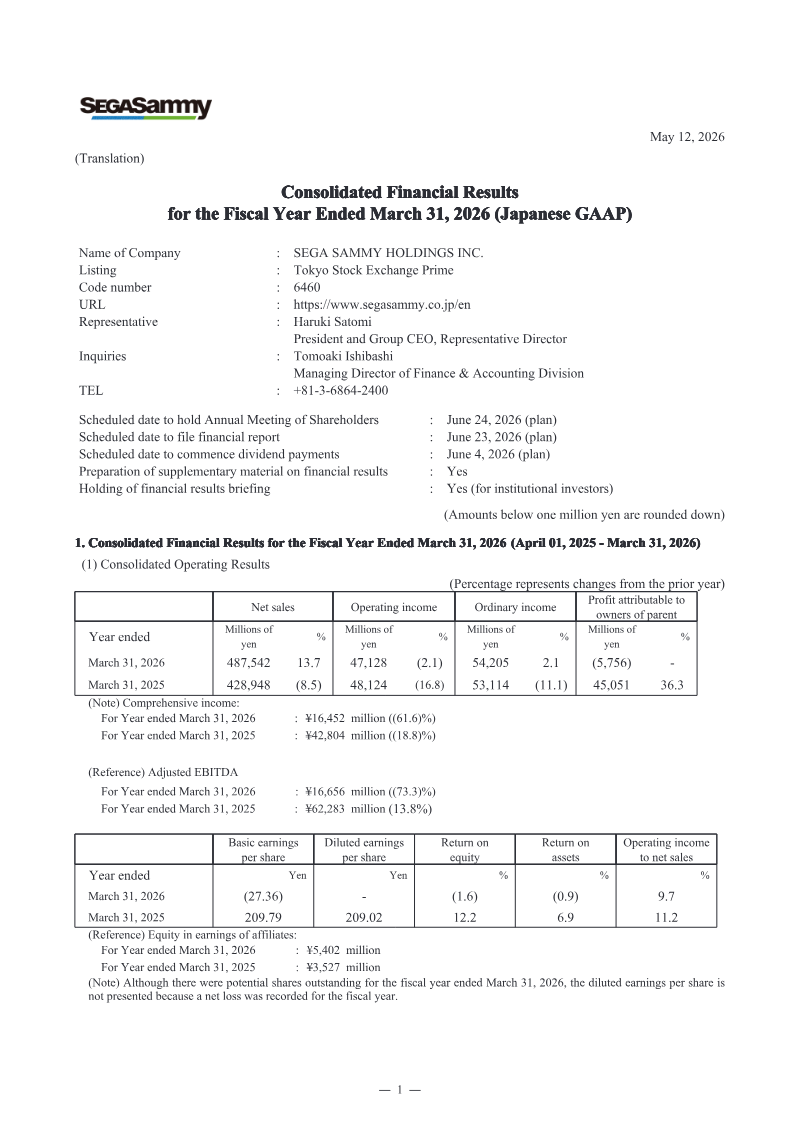
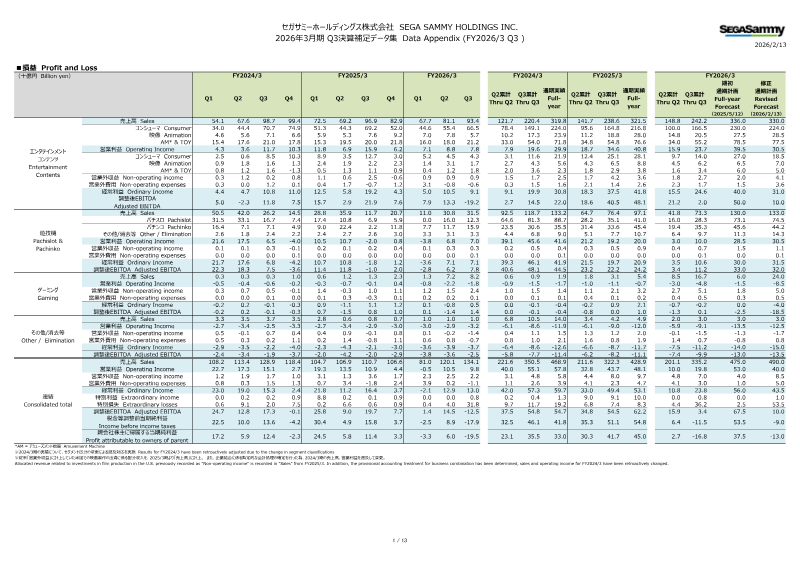
The analysis demonstrates a robust expansion of the company’s revenue and profitability over the FY24/3 to FY27/3 period, with total sales projected to climb from ¥54.1 bn in the first quarter of FY24/3 to ¥357.0 bn by FY27/3. This growth is largely driven by the consumer and entertainment segments, which account for roughly 70% of overall sales. Operating income is expected to rise from ¥4.3 bn in FY24/3 Q1 to ¥78.1 bn by FY27/3, while adjusted EBITDA is projected to increase from ¥5.0 bn to ¥62.2 bn, underscoring improving profitability margins.
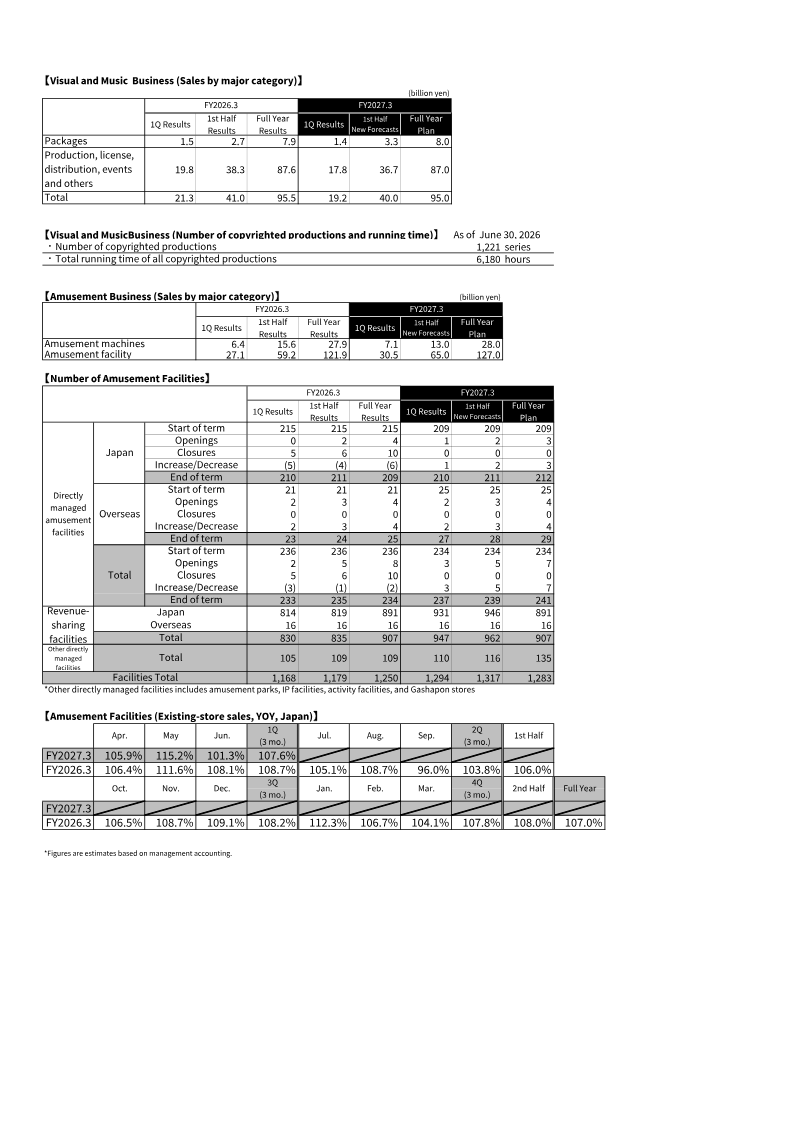
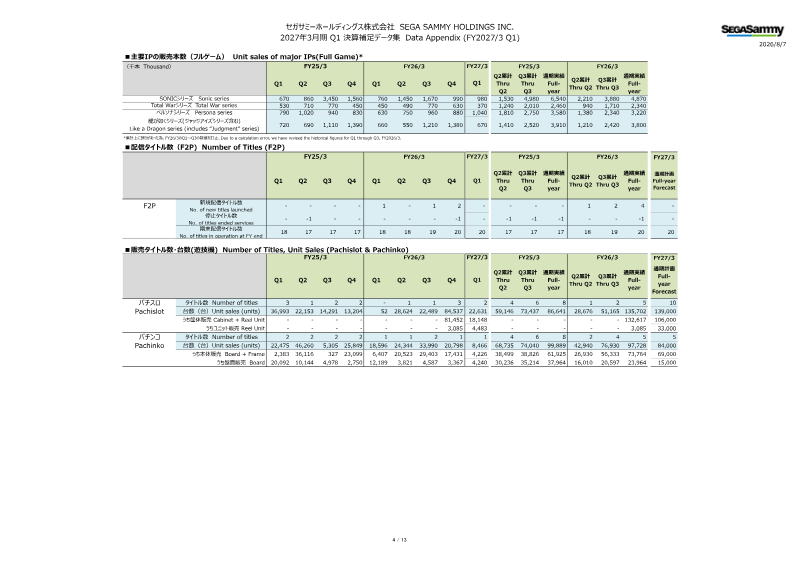
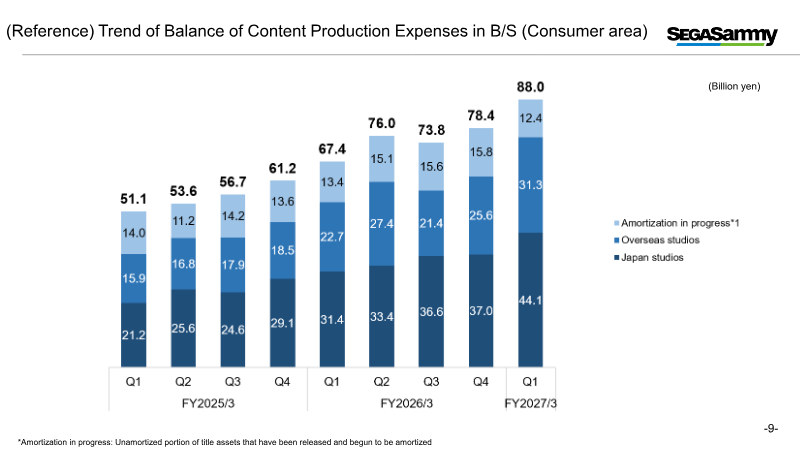
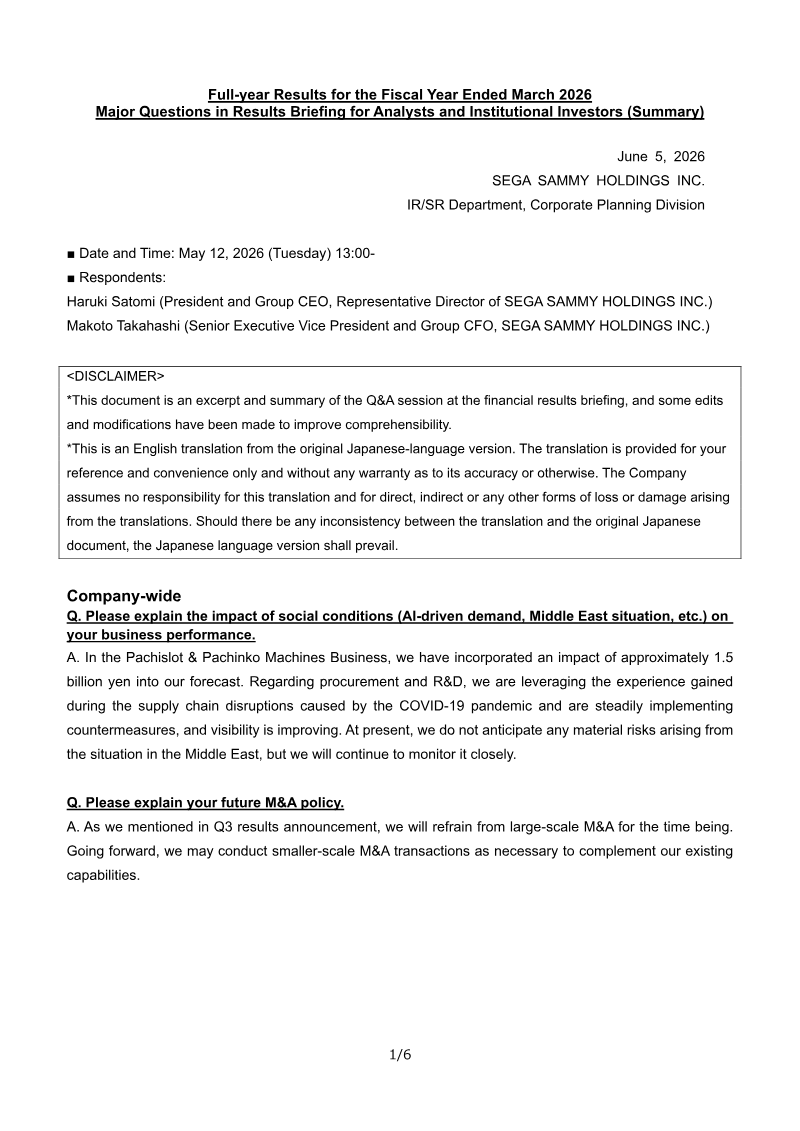
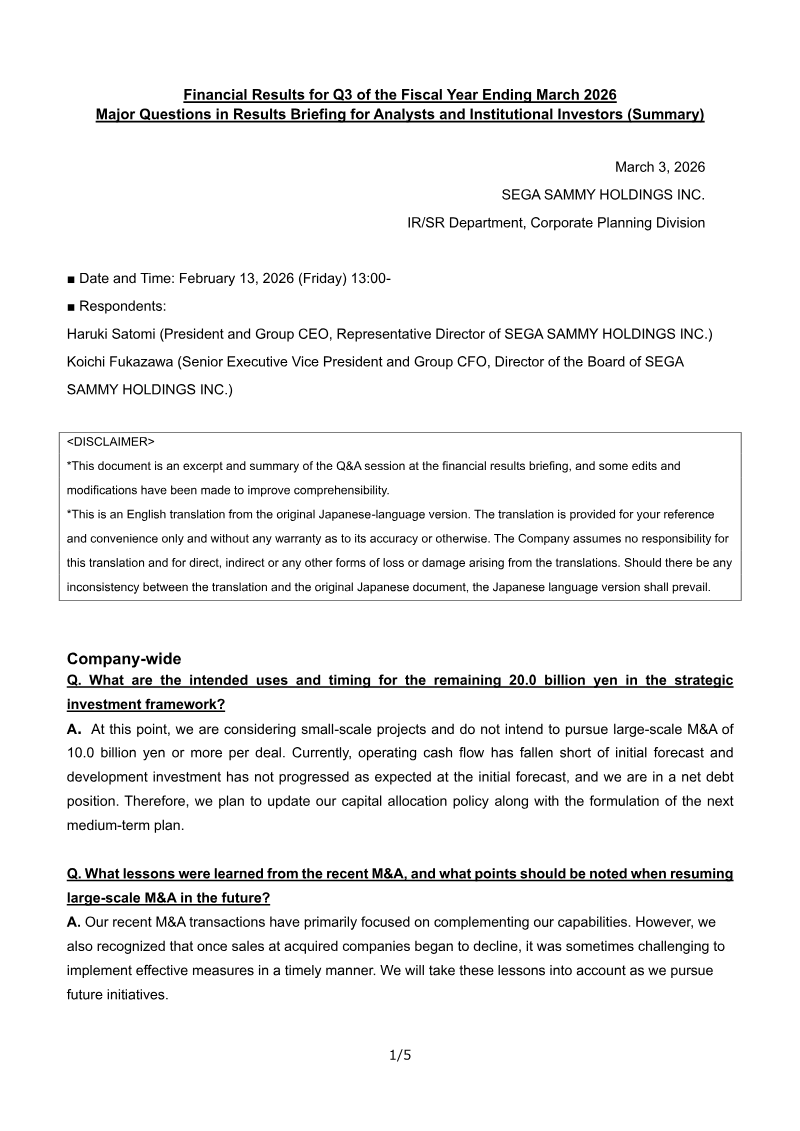
Segment-level data reveal that consumer sales doubled over the period, whereas entertainment content and gaming experienced moderate gains. International markets consistently outperform domestic ones, with overseas sales maintaining a ratio above 60% across all years. Within the gaming portfolio, flagship IPs such as the Sonic series saw a 20% year-over-year increase in unit sales during FY26/3 Q1–Q3, and the War series grew by 15%. Free-to-play titles added only one new launch and saw two cancellations, indicating a cautious approach to that segment. The casino division posted revenue growth from KRW 91.2 bn in Q1 FY24/3 to KRW 156.2 bn by the end of FY26/3, driven largely by a 30% rise in casino sales and a 25% increase in hotel revenue.
Pachinko and Pachislot performance metrics show fluctuating market share for the company, with sales shares ranging between 21% and 24% from 2023 to 2024. Prototype approval rates varied widely, from 21% to 80% for Pachislot and 23–34% for Pachinko between 2023-2025. Utilization shares declined modestly, with Pachislot utilization falling from 30.8% in FY25/3 to 30.1% in FY26/3, and Pachinko utilization dropping from 34.9% to 23.8%, suggesting a relative loss of market activity compared with competitors.
Overall, the data indicate sustained top-line growth and improving profitability driven by strong international performance and a diversified product mix, while the company faces increasing competition in the Pachinko/Pachislot arena that may require strategic adjustments to maintain market share.
Sega Sammy Holdings · 2026
Sega Sammy Holdings · 2026
Sega Sammy Holdings · 2026
Sega Sammy Holdings · 2026

Sega Sammy Holdings · 2026


Sega Sammy Holdings · 2026


Sega Sammy Holdings · 2026


Sega Sammy Holdings · 2026


Sega Sammy Holdings · 2026


Sega Sammy Holdings · 2026


Sega Sammy Holdings · 2026


Sega Sammy Holdings · 2026
NEXON Co. · 2026