Skip to main content
Game Industry
Library
Ask AI
Cited answers
Search…
⌘
K
Library
Search
TL;DR
Connect your AI
PRO
Browse
Topics
Collections
Writers
Glossary highlights
Theme
Help & info
Subscribe
Game Industry
Library
Library
TL;DR
Search
Ask AI
Saved
Collections
Asia-Pacific
Asia-Pacific
Japan, China, Korea, Southeast Asia, India and Australia.
321 documents
Reports
Presentations
Whitepapers
Newest first
Oldest first
Title A–Z
Title Z–A
NEXON Co.
Report
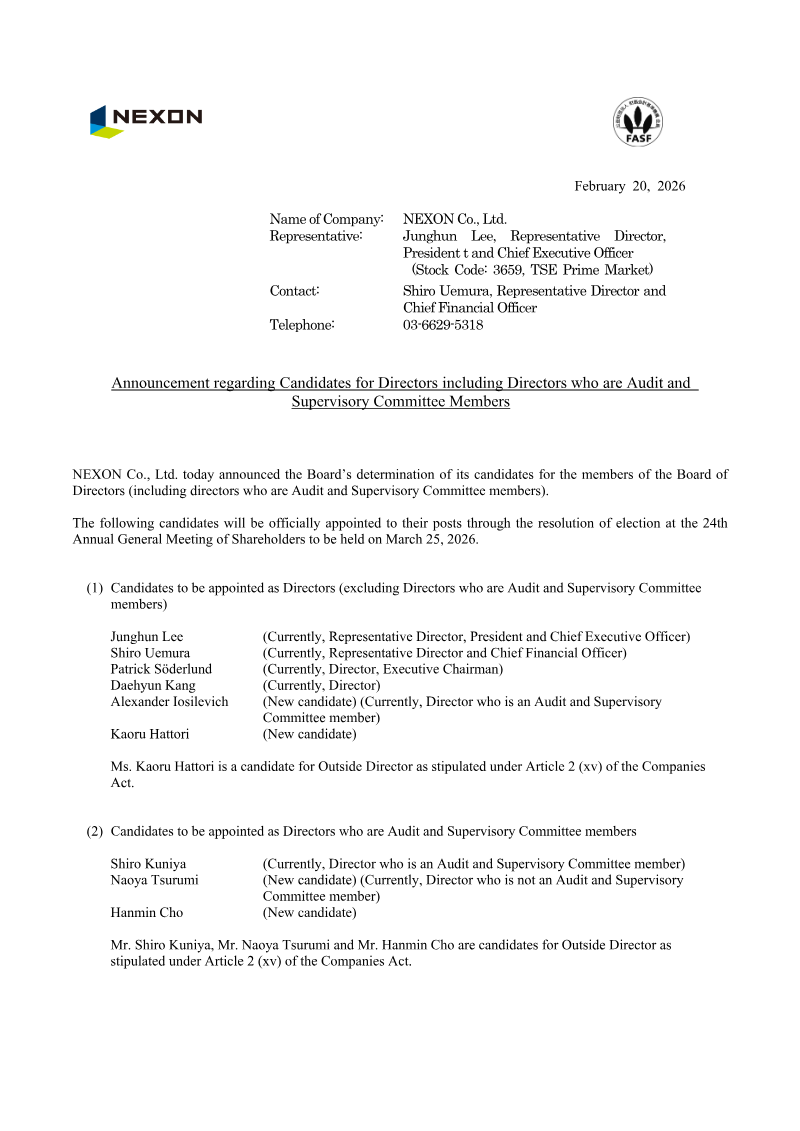
2026.02.20 Announcement regarding Candidates for Directors including Directors who are Audit and Supervisory Committee Members
NEXON Co., Ltd. announced the Board’s selection of candidates for its 24th Annual General Meeting on March 25, 2026. The slate includes six directors, among them two new outside directors and three individuals who will serve concurrently on the Audit and Supervisory Committee. Current executives Junghun Lee, Shiro Uemura, Patrick Söderlund and Daehyun Kang are retained. New appointments comprise Alexander Iosilevich, a seasoned investment‑banking executive with no shareholding in NEXON, and Kaoru Hattori, a Japanese lawyer and partner at Nagashima Ohno & Tsunematsu who also holds trustee and board roles in Toyo Seikan Group Holdings. The Audit and Supervisory Committee will be strengthened by Shiro Kuniya, Naoya Tsurumi—an experienced Sega executive with extensive leadership roles across SEGA subsidiaries—and Hanmin Cho, a private‑equity professional who has led investment divisions at NXC Corporation and holds directorships in NXMH B.V. and Bitstamp Limited. The announcement details each candidate’s career trajectory, concurrent positions, and share ownership (all new candidates hold zero shares). The selection aligns with Korean Companies Act provisions for outside directors and reflects NEXON’s strategy to blend internal leadership continuity with external expertise in finance, gaming operations, and regulatory oversight. The candidates’ diverse backgrounds—spanning global investment banking, legal practice, gaming industry leadership, and private‑equity management—are intended to enhance governance, strategic direction, and risk oversight for the company’s operations in South Korea and its international markets.
Akatsuki
Report
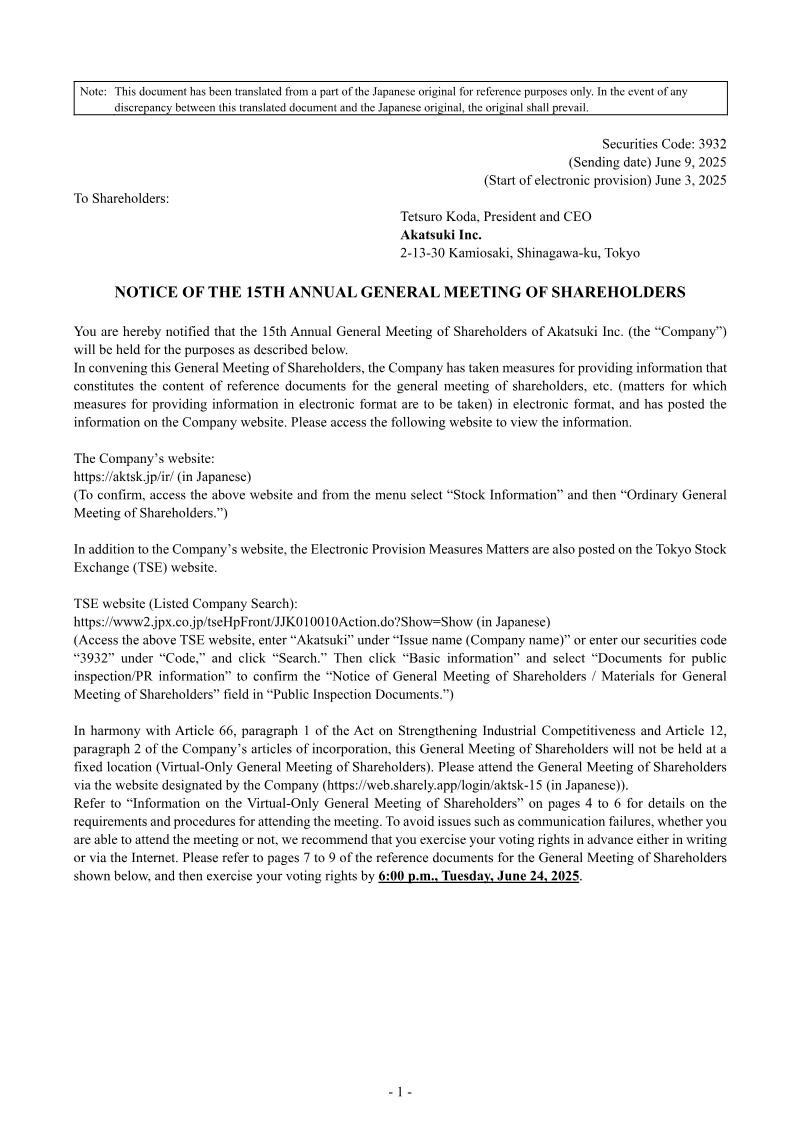
Notice of the 15th Annual General Meeting of Shareholders: Akatsuki Inc.
Note: This document has been translated from a part of the Japanese original for reference purposes only. In the event of any discrepancy between this translated document and the Japanese original, the original shall prevail. (Start of electronic provision) June 3, 2025 Tetsuro Koda, President and CEO 2-13-30 Kamiosaki, Shinagawa-ku, Tokyo NOTICE OF THE 15TH ANNUAL GENERAL MEETING OF SHAREHOLDERS You are hereby notified that the 15th Annual General Meeting of Shareholders of Akatsuki Inc.
Akatsuki
Report
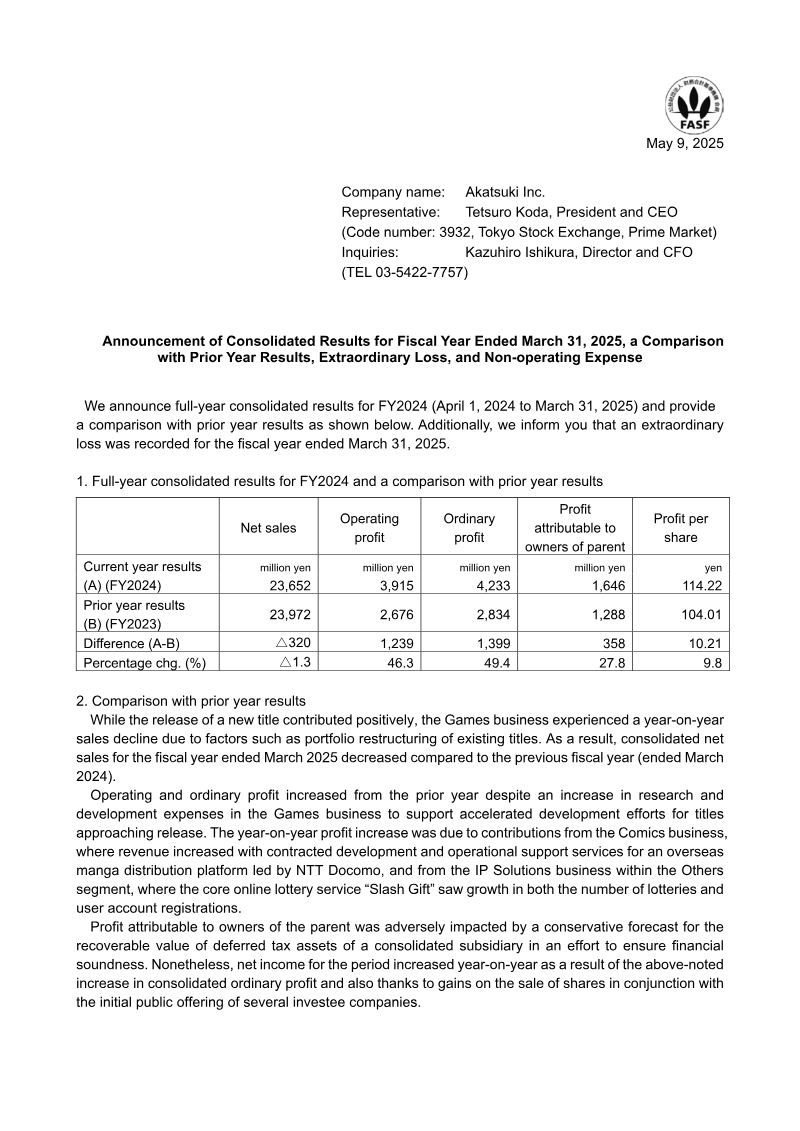
Announcement of Consolidated Results for Fiscal Year Ended March 31, 2025, a Comparison with Prior Year Results, Extraordinary Loss, and Non-operating Expense
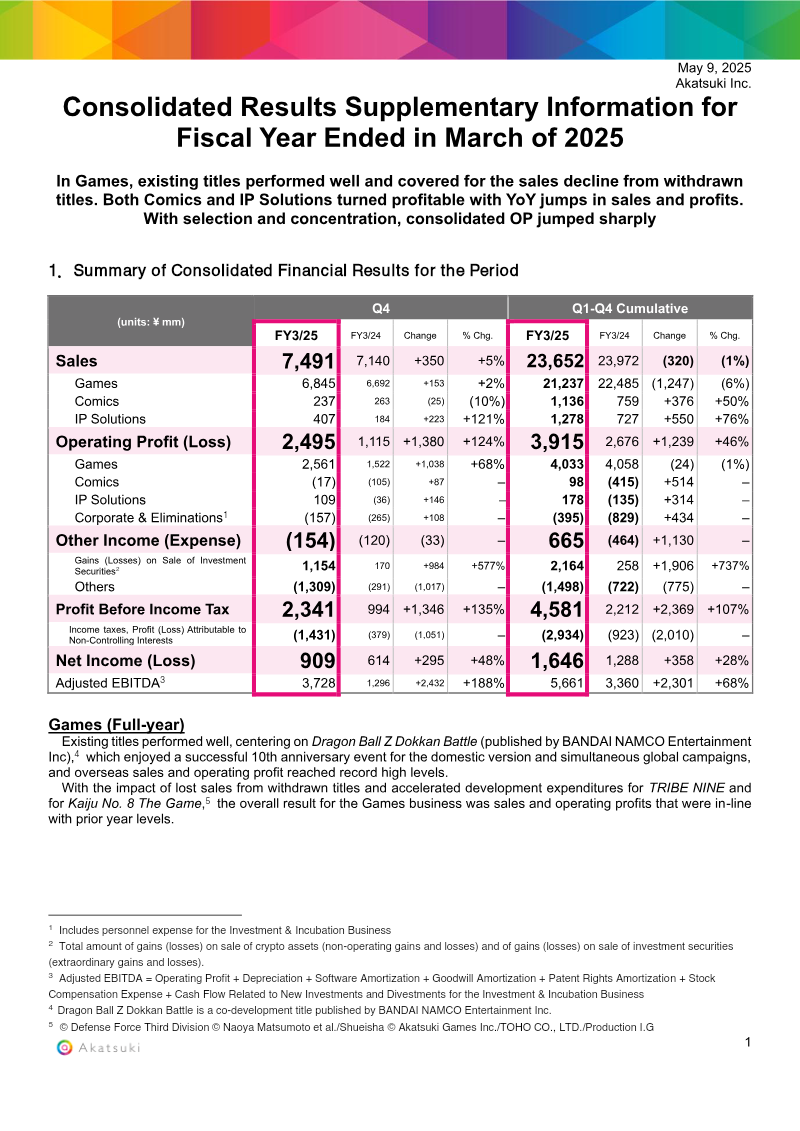
Akatsuki Inc. reported consolidated financial results for the fiscal year ending March 31, 2025 (April 1 2024–March 31 2025). Net sales fell by 1.3 % to ¥23,652 million from ¥23,972 million in FY2023, reflecting a decline in the Games segment despite a new title launch. Operating ordinary profit rose by ¥1,239 million (46.3 %) to ¥3,915 million, driven largely by gains in the Comics and IP Solutions businesses; the former benefited from contracted services for an overseas manga platform, while the latter saw growth in its online lottery service “Slash Gift.” Ordinary profit attributable to parent shareholders increased by ¥1,399 million (49.4 %) to ¥4,233 million, and net income attributable to owners of the parent grew by ¥358 million (27.8 %) to ¥1,646 million, aided by gains on share sales from IPOs of investee companies. A conservative write‑down of deferred tax assets reduced the profit attributable to owners, yet overall net income still improved. An extraordinary loss of ¥593 million was recorded on the valuation of investment securities held by the group, reflecting a conservative assessment of recoverable value amid market uncertainty. On a non‑consolidated basis, the company recorded a ¥5,776 million provision for doubtful accounts and a ¥2,454 million loss on valuation of shares in affiliated companies; these items are largely confined to consolidated subsidiaries and have a minor impact on the consolidated results. The report covers Japan‑based operations for FY2025, with data derived from internal financial statements and market assessments.
Akatsuki
Report
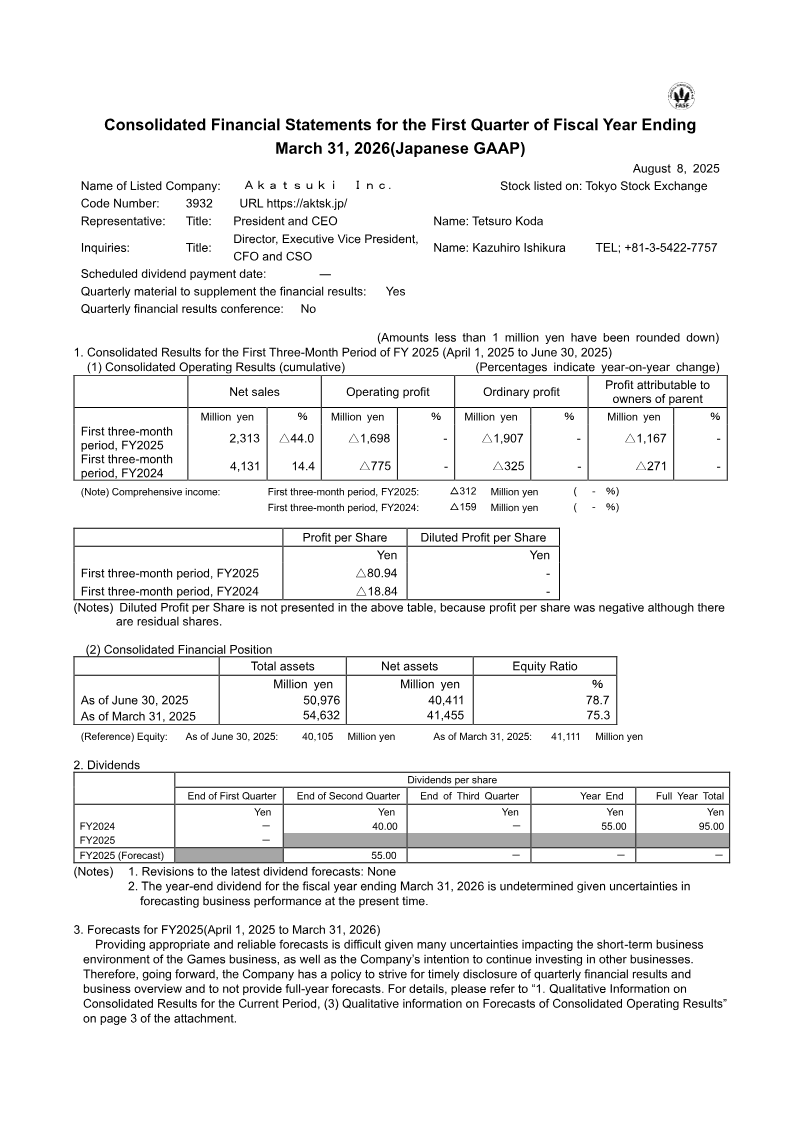
Consolidated Financial Statements: Q1 Fiscal Year 2026 (Japan)
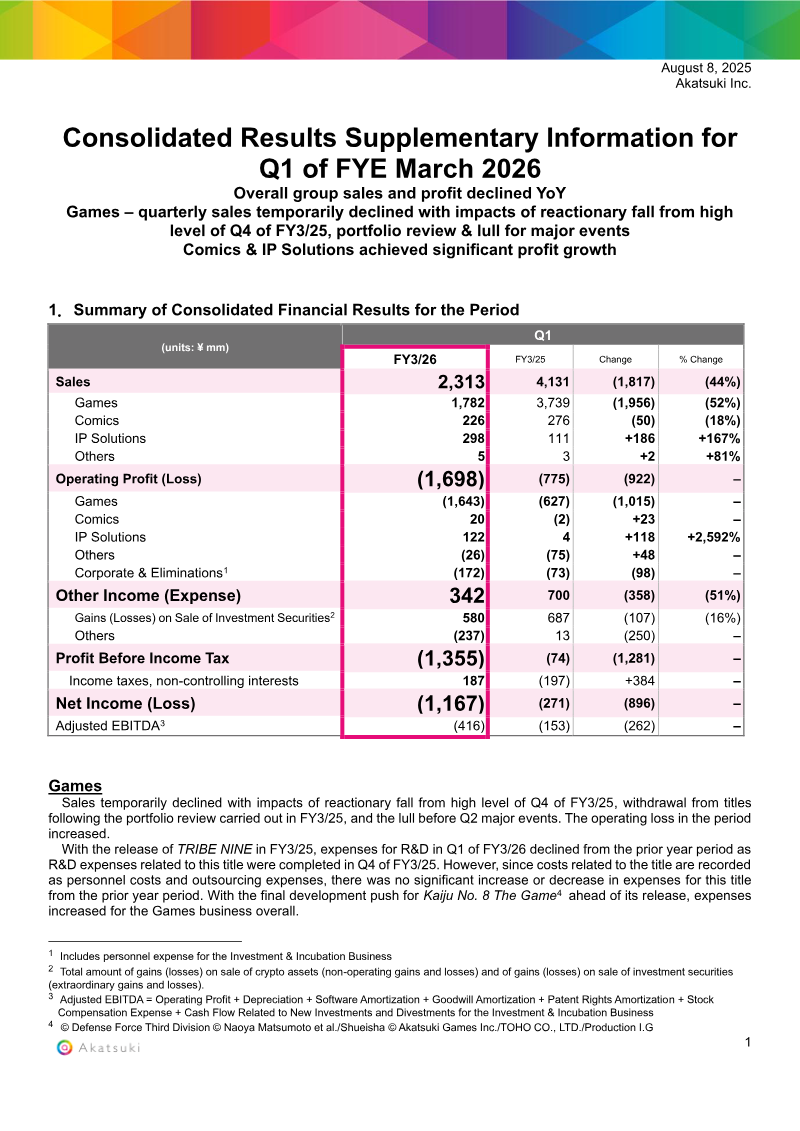
Akatsuki Inc. reports a first‑quarter fiscal 2025 performance that reflects a sharp contraction in its core gaming and comics businesses amid a challenging macro‑environment. Net sales fell 44 % YoY to ¥2,313 million, while operating loss widened to ¥1,698 million from a prior‑year loss of ¥775 million. The company’s consolidated equity ratio improved to 78.7 % from 75.3 %, but total assets declined by ¥3,656 million to ¥50,976 million. Net loss attributable to parent shareholders reached ¥1,167 million, a significant increase from the prior‑year loss of ¥271 million. Comprehensive income deteriorated to ¥312 million in losses versus ¥159 million previously. Segment analysis shows the Games unit suffered a 52.3 % sales decline and an operating loss of ¥1,643 million; the Comics unit posted a modest profit of ¥20 million after an 18.3 % sales drop; the newly standalone IP Solutions unit grew sales by 167 % and generated a ¥122 million profit, largely driven by the inclusion of subsidiary CRAYON, Inc. The Others segment recorded a small profit after an 80.9 % sales increase. Geographically, the report focuses on Japan with no disclosed overseas revenue breakdown. Methodologically, figures are based on Japanese GAAP quarterly consolidation; no full‑year forecasts are provided due to market uncertainty. The company maintains a policy of timely quarterly disclosure while withholding FY2026 forecasts, citing volatile gaming and investment conditions.
Akatsuki
Report
Consolidated Results Supplementary Information: Fiscal Year Ended March 2025
Akatsuki Inc. reported consolidated financial results for fiscal year ended March 2025, showing a modest 5 % increase in sales to ¥23.652 billion compared with the prior year, driven primarily by strong performance of existing games such as Dragon Ball Z Dokkan Battle. Games sales rose 2 % to ¥21.237 billion, while comics and IP Solutions segments returned to profitability with 10 % and 121 % year‑over‑year sales gains, respectively. Operating profit surged 124 % to ¥3.915 billion, largely due to a sharp rise in operating profit from games (68 % increase) and significant gains on the sale of investment securities, which contributed ¥1.154 billion to profit before tax. Net income increased 48 % to ¥1.646 billion, supported by a 28 % rise in adjusted EBITDA (¥5.661 billion). The company’s balance sheet remained solid, with total assets of ¥54.632 billion and net assets of ¥41.455 billion, while total liabilities decreased to ¥13.177 billion. Cash balances were maintained at ¥33.300 billion, reflecting disciplined working‑capital management. The results cover the Japanese market and global operations for games, comics, and IP solutions. Methodology includes consolidated financial statements with adjustments for investment and incubation business personnel expenses, and gains on crypto asset sales are classified as non‑operating. Overall, Akatsuki’s selective focus on high‑performing titles and profitable IP solutions has driven a sharp improvement in operating profitability despite the withdrawal of some titles.
Akatsuki
Report
Consolidated Financial Statements: Second Quarter and First Half-Year Period of Fiscal Year Ending March 31, 2026
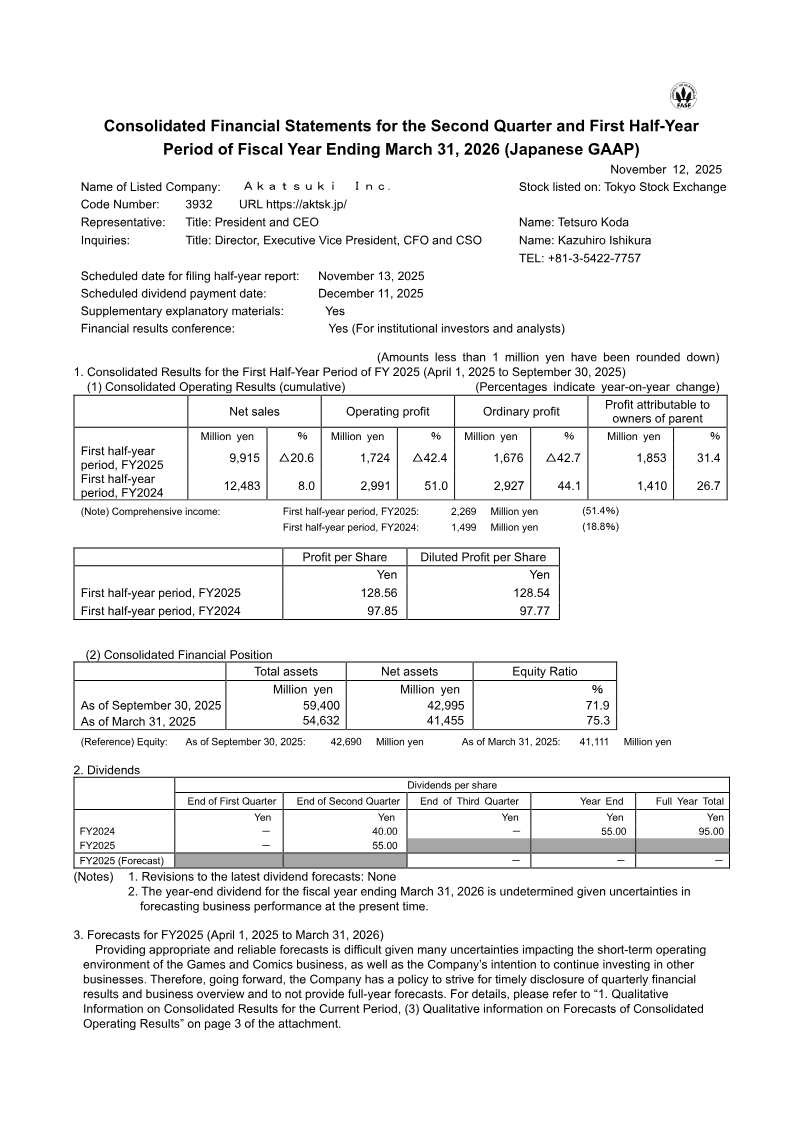
Akatsuki Inc. reports consolidated financial results for the first half of fiscal year ending March 31, 2026 (April 1–September 30, 2025). Net sales fell 20.6 % YoY to ¥9,915 million, while operating profit declined 42.4 % to ¥1,724 million; ordinary profit dropped 42.7 % to ¥1,676 million, yet net income attributable to parent rose 31.4 % to ¥1,853 million, driven by a higher comprehensive income of ¥2,269 million versus ¥1,499 million the prior year. Profit per share diluted increased from ¥97.85 to ¥128.56. Total assets grew to ¥59,400 million, with net assets rising to ¥42,995 million and equity ratio improving to 71.9 %. Cash flows from operating activities were modest at ¥369 million, while investing cash outflows of ¥5,433 million reflected significant purchases of investment securities and intangible assets. Financing activities generated net inflows of ¥1,775 million, offset by dividends paid of ¥795 million. Segment analysis shows the Games and Comics business experienced a 23.2 % sales decline to ¥9,257 million and a 41.2 % profit drop, whereas the Entertainment and Lifestyle segment grew sales by 76.1 % to ¥649 million, achieving a 90.7 % profit increase. The Others segment recorded a sharp sales decline and continued losses. The report notes significant consolidation changes: six new subsidiaries, including CRAYON Inc., were added; Akatsuki Fukuoka was liquidated. Goodwill increased by ¥4,316 million due to acquisitions of Natee and PAPABUBBLE JAPAN. No full‑year forecasts are provided, reflecting uncertainty in the Games and Comics market and ongoing investment plans.
Akatsuki
Report
Consolidated Results Supplementary Information: Q1 FYE March 2026
Akatsuki Inc. reported a sharp decline in consolidated sales and operating results for Q1 of the fiscal year ending March 2026, with total group sales falling 44% YoY to ¥2,313 million. The Games segment suffered the largest hit, dropping 52% to ¥1,782 million and recording an operating loss of ¥1,643 million, largely due to a post‑Q4 portfolio review withdrawal and the absence of high‑profile releases. R&D spending for the Games business fell from the previous year as development on “TRIBE NINE” concluded, but costs for the upcoming title “Kaiju No. 8 The Game” increased personnel and outsourcing expenses. In contrast, the Comics division saw a modest 18% sales decline to ¥226 million but improved profitability, with operating profit rising from a loss of ¥2 million to ¥20 million. The division’s focus on original works and continued service provision to the overseas platform MANGA MIRAI contributed to this turnaround. The IP Solutions unit experienced explosive growth, with sales up 167% to ¥298 million and operating profit soaring 2,592% to ¥122 million, driven by the successful online lottery “Slash Gift” and the inclusion of CRAYON, Inc. in consolidation. Other income sources shifted, with gains on investment securities decreasing by ¥107 million to ¥580 million. Net income swung from a loss of ¥271 million in FY3/25 to a larger loss of ¥1,167 million in FY3/26, reflecting the combined impact of segment downturns and higher operating losses. Adjusted EBITDA also deteriorated from ¥153 million to a loss of ¥416 million. The financial data cover the Japanese market, covering all core segments—Games, Comics, IP Solutions, and ancillary services—from Q1 FY3/24 through Q1 FY3/26. The analysis relies on consolidated financial statements, trend tables, and explanatory notes detailing segment performance, expense composition, and investment activity.
Akatsuki
Report
Consolidated Results Supplementary Information: Q2 of FYE March 2026
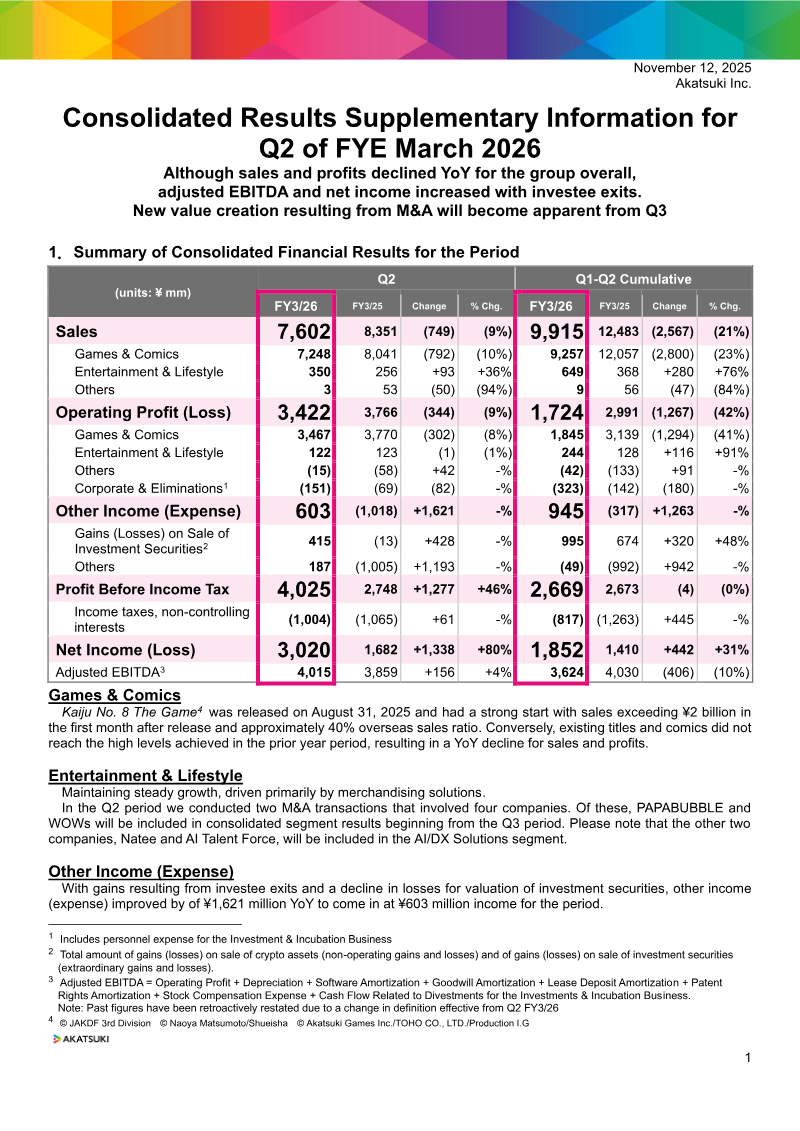
Akatsuki Inc. reported consolidated financial results for the second quarter of fiscal year ending March 2026, noting a 9 % decline in sales to ¥7,602 million and a 21 % drop in cumulative year‑to‑date sales of ¥9,915 million versus the prior year. The Games & Comics segment led the decline with a 10 % YoY fall to ¥7,248 million, while Entertainment & Lifestyle grew 36 % to ¥350 million, and the Others segment contracted sharply by 94 %. Operating profit fell 9 % to ¥3,422 million, largely due to weaker performance in the core Games & Comics unit; however, net income rose 80 % to ¥3,020 million, driven by gains from investee exits and reduced valuation losses on investment securities. Adjusted EBITDA increased modestly by 4 % to ¥4,015 million, reflecting a recovery in operating profitability after the release of new titles. Key drivers include the launch of “Kaiju No. 8 The Game” on 31 August 2025, which generated over ¥2 billion in first‑month sales with a 40 % overseas share, partially offsetting declines from legacy titles. Two M&A transactions in Q2 added PAPABUBBLE and WOWs to the consolidated segment from Q3, while Natee and AI Talent Force will join the AI/DX Solutions segment. The company’s balance sheet shows a net asset base of ¥42,995 million and cash equivalents of ¥33,272 million, with current liabilities at ¥6,954 million. Methodologically, the report aggregates data from all operating subsidiaries, restating prior figures to align with revised definitions effective Q2 FY3/26. The analysis covers Japan and international markets, focusing on the Games & Comics, Entertainment & Lifestyle, and AI/DX Solutions segments over a two‑quarter period.
Akatsuki
Report
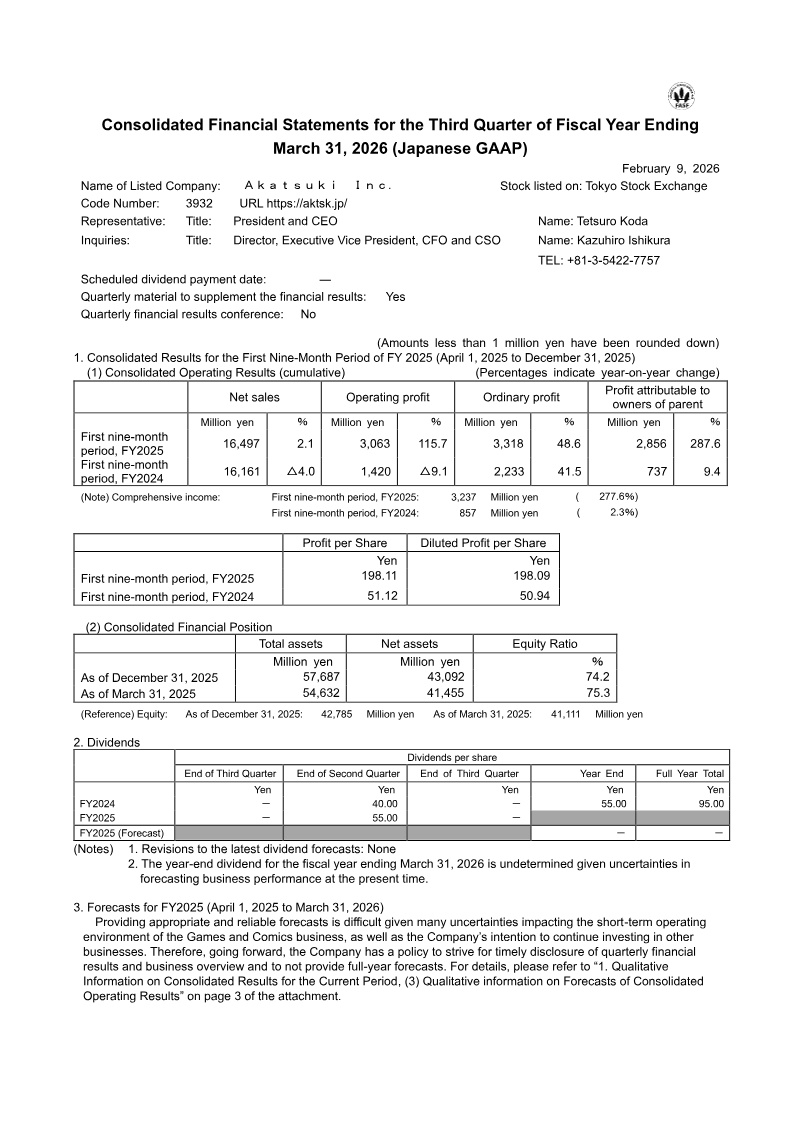
Consolidated Financial Statements for the Third Quarter of Fiscal Year Ending March 31, 2026
Akatsuki Inc. reports consolidated financial results for the first nine months of fiscal year 2025, ending December 31 2025. Net sales rose modestly by 2.1 % to ¥16,497 million, while operating profit surged 115.7 % to ¥3,063 million and ordinary profit increased 48.6 % to ¥3,318 million. Net profit attributable to parent shareholders climbed 287.6 % to ¥2,856 million, yielding diluted earnings per share of ¥198.11 versus ¥51.12 in the prior year. Total assets reached ¥57,687 million, up ¥3,054 million from March 31 2025, with net assets at ¥43,092 million and an equity ratio of 74.2 %. The company’s liquidity remained solid, with cash and deposits at ¥28,377 million and current liabilities down to ¥4,462 million. Segment performance varied: the Games and Comics business posted a 5.3 % decline in sales but doubled operating profit through cost reductions; Entertainment and Lifestyle achieved a 76.1 % sales increase to ¥1,400 million but saw a modest profit decline; the newly reported AI/DX Solutions segment generated ¥600 million in sales and incurred a ¥112 million loss. The Others segment recorded a sharp 83.1 % sales drop and a ¥51 million loss. The company added five subsidiaries to its consolidation scope, including CRAYON Inc. and PAPABUBBLE, while excluding Akatsuki Fukuoka after liquidation. No changes to accounting policies were noted. Forecasts for FY 2026 are withheld due to market uncertainties, and the company maintains a policy of not providing full‑year guidance.
Akatsuki
Report
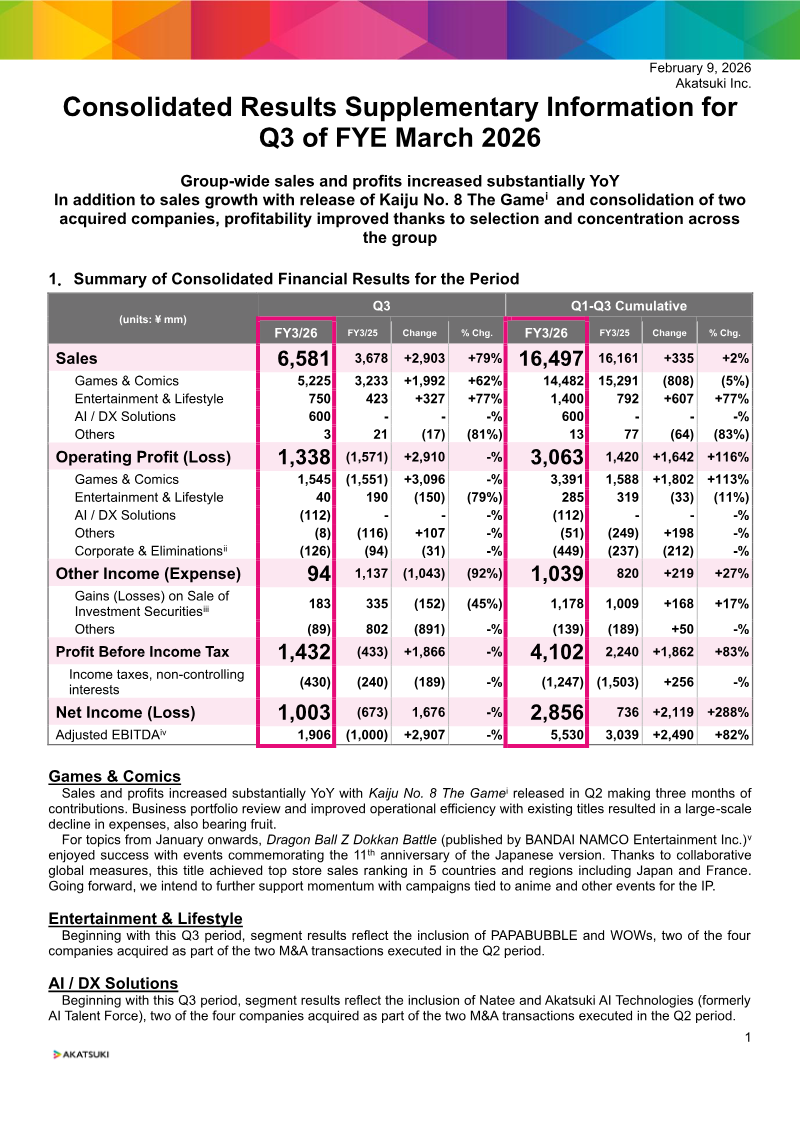
Consolidated Results Supplementary Information: Q3 FY3/26
Akatsuki Inc. reported a dramatic turnaround in Q3 FY3/26, with group‑wide sales surging 79 % YoY to ¥6,581 million and operating profit turning from a loss of ¥1,571 million to a gain of ¥1,338 million. The rebound is largely attributed to the Q2 release of “Kaiju No. 8 The Game,” which contributed three months’ worth of revenue, and the consolidation of two acquired entities that broadened the Games & Comics portfolio. Within this segment, sales climbed 62 % to ¥5,225 million and operating profit rose 113 % to ¥1,545 million. The Entertainment & Lifestyle segment also grew 77 % in sales to ¥750 million, driven by the inclusion of PAPABUBBLE and WOWs following Q2 acquisitions. AI/DX Solutions, newly integrated through Natee and Akatsuki AI Technologies, generated ¥600 million in sales but recorded a loss of ¥112 million. Net income for the quarter reached ¥1,003 million, a 288 % increase from the prior year’s loss of ¥673 million. Adjusted EBITDA expanded 82 % to ¥1,906 million, reflecting strong operating performance and effective cost management. Cash balances rose to ¥33,266 million, while total assets stood at ¥57,687 million. The company’s balance sheet remained solid with net assets of ¥43,092 million and total liabilities of ¥14,595 million. Methodologically, figures are presented in Japanese yen (millions) and include retroactive restatements from Q2 FY3/26 due to prior period errors. The report covers the entire Japanese market and global operations, focusing on Q3 FY3/26 with cumulative data for FY3/26 versus FY3/25.
KLab
Report
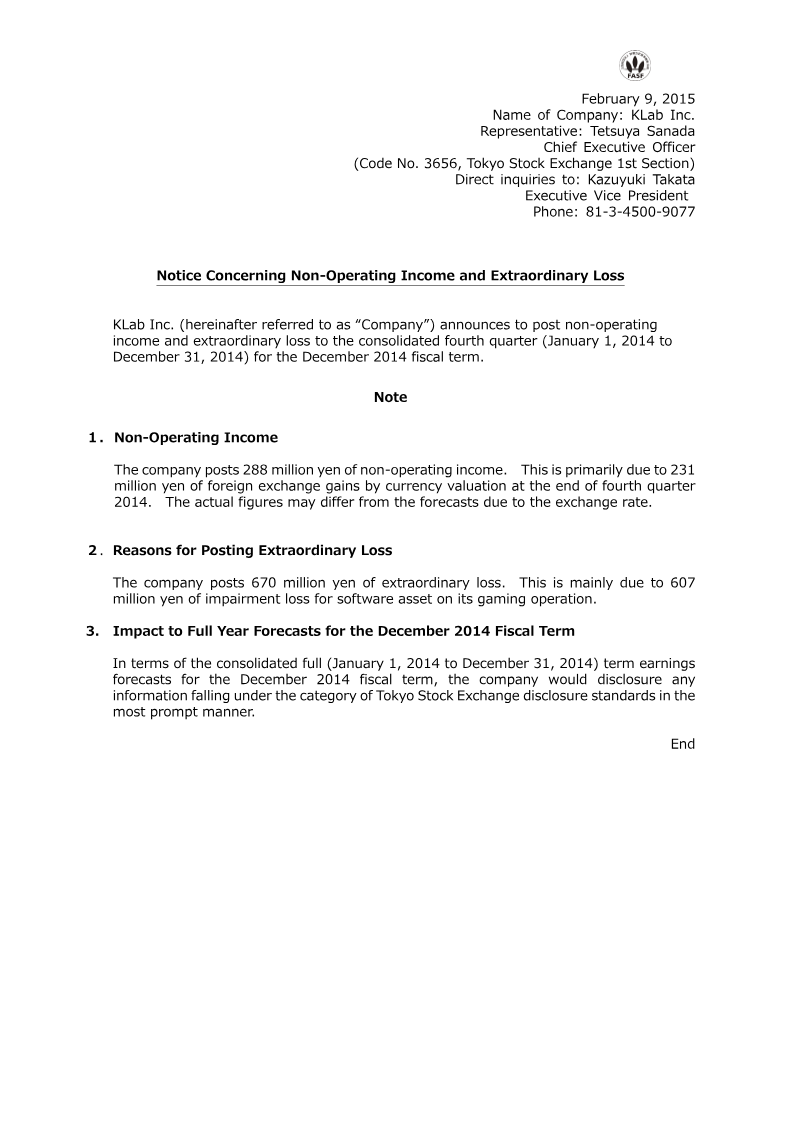
Notice Concerning Non-Operating Income and Extraordinary Loss: Japan
KLab Inc. disclosed a net non‑operating income of 288 million yen for the consolidated fourth quarter of its December 2014 fiscal year, driven largely by a 231 million yen foreign‑exchange gain from currency valuation at quarter‑end. The company also reported an extraordinary loss of 670 million yen, primarily attributable to a 607 million yen impairment charge on software assets related to its gaming operations. These figures represent the company’s first quarterly disclosure of such items for the year, indicating a significant impact on its overall profitability. The announcement clarifies that the non‑operating income and extraordinary loss will affect the company’s full‑year earnings forecasts for the 2014 fiscal period. KLab commits to providing any additional information required under Tokyo Stock Exchange disclosure standards promptly, ensuring transparency for investors and regulators. The notice is limited to the Japanese market, covering a single fiscal year (January 1–December 31, 2014) and focusing on the gaming segment of KLab’s operations. No survey or external data sources are cited; the figures derive from internal financial statements and accounting adjustments made during the reporting period.
KLab
Report
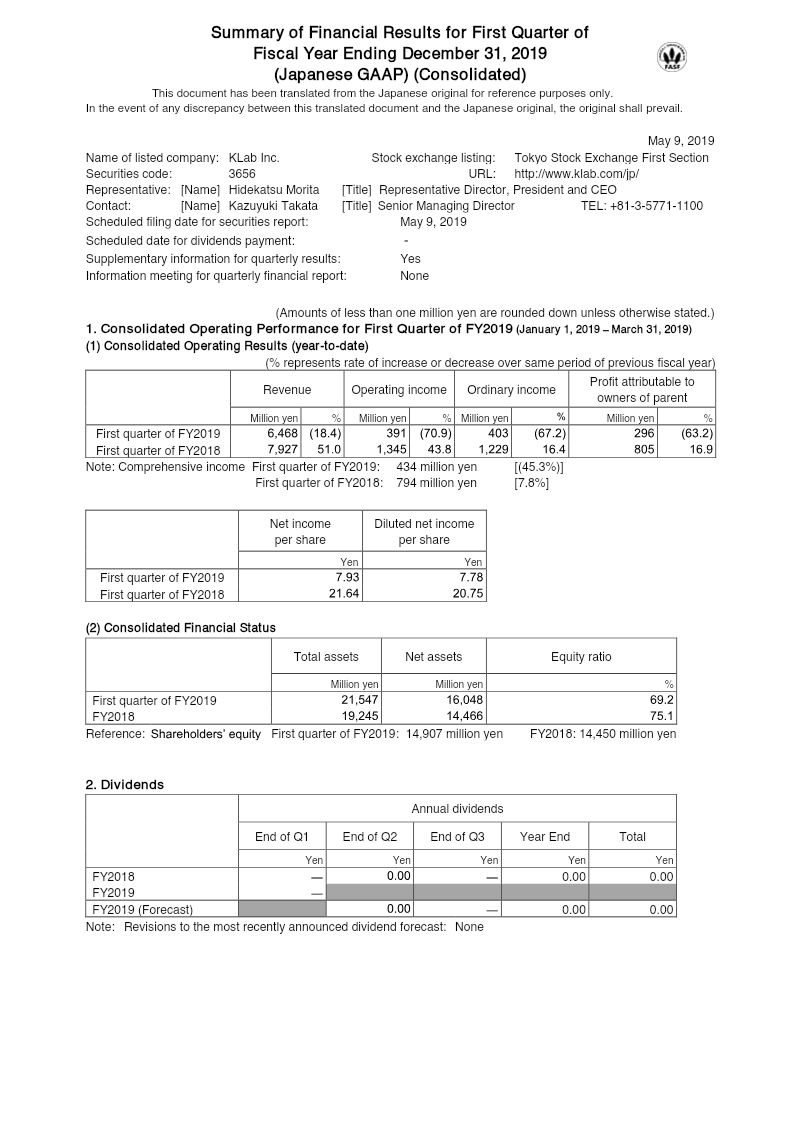
Consolidated Financial Statement: Q1 2019
KLab Inc. reported consolidated financial results for the first quarter of fiscal year 2019 (January 1–March 31, 2019). Revenue declined 18.4 % to ¥6,468 million compared with the same period in FY2018, largely due to a drop in sales of the Love Live! School Idol Festival title. Operating income fell 70.9 % to ¥391 million, ordinary income decreased 67.2 % to ¥403 million, and profit attributable to owners of parent contracted 63.2 % to ¥296 million. Net income for the quarter was ¥303 million, a 65 % reduction from ¥805 million in FY2018. Comprehensive income also fell sharply, from ¥794 million to ¥435 million, reflecting a 45.3 % increase in other comprehensive income components. Total assets rose to ¥21,547 million, up ¥2.3 billion from the prior year’s end, driven by increases in operating investment securities and software in progress. Net assets increased to ¥16,048 million, an addition of ¥1.58 billion, largely due to equity in a newly consolidated subsidiary. The equity ratio declined from 75.1 % to 69.2 %. Current liabilities decreased, while long‑term debt increased, contributing to the shift in leverage. KLab forecasted FY2019 revenue between ¥32 billion and ¥40 billion, operating income between ¥1 billion and ¥4.5 billion, ordinary income in the same range, and profit attributable to owners between ¥700 million and ¥3.1 billion. The company noted that future results will depend heavily on the success of new game releases and market conditions, and it applied a range‑based presentation for forecasts. No dividends were declared for FY2019, and no significant changes in shareholders’ equity or accounting policies occurred during the quarter.
Previous
1
2
3
4
…
27
Next