Udonis
Technology44 documents
Documents
Article
Mobile Game Genres Explained
The mobile gaming landscape has matured into a sophisticated ecosystem defined by a vast array of mechanics, engagement styles, and monetization strategies. Spanning over 20 distinct categories, the market encompasses everything from high-intensity action and strategy titles to accessible puzzle and social casino games. This diversity is further enriched by specialized niches, including augmented reality, educational software, and horror experiences, all of which contribute to the industry's broad appeal and sustained growth.
A defining trend in contemporary mobile development is the emergence of hybrid models, where developers integrate disparate mechanics—such as combining role-playing elements with gacha systems or blending strategy with tower defense—to foster deeper player engagement. This trend reflects a broader industry shift toward innovation, as developers continuously refine their offerings to meet evolving player preferences. By leveraging these multifaceted gameplay loops, studios are successfully increasing retention and creating more complex, varied experiences that transcend traditional genre boundaries.
These insights are grounded in extensive industry experience, drawing from a track record of acquiring over 300 million users since 2018. The analysis emphasizes the critical importance of performance metrics, such as Cost Per Acquisition, and provides strategic guidance for navigating the competitive landscape of indie and strategy game marketing. Ultimately, the strength of the mobile market lies in its inherent accessibility and the ongoing ability of developers to adapt to shifting consumer behaviors, ensuring that the ecosystem remains a dynamic and profitable space for both established publishers and independent creators.
- The mobile gaming market has matured into a diverse ecosystem comprising over 20 distinct categories, ranging from high-intensity action and strategy to accessible puzzle and social casino games.
- A primary development trend involves the use of hybrid models that integrate disparate mechanics, such as combining RPG elements with gacha systems or strategy with tower defense, to improve player retention.
- The analysis is based on a track record of acquiring over 300 million users since 2018, providing a foundation for understanding current industry performance metrics.
- Developers are increasingly prioritizing multifaceted gameplay loops to create complex experiences that transcend traditional genre boundaries and cater to evolving consumer preferences.
- Success in the current competitive landscape requires a focus on performance metrics like Cost Per Acquisition and strategic marketing approaches for both indie and strategy titles.
+2
UdonisNov 2025
Article
How Royal Kingdom Reached $145M in Less Than a Year
Royal Kingdom, developed by Dream Games, has established itself as a major commercial force in the mobile gaming sector, generating $145 million in revenue and securing 55 million downloads within its first year following a November 2024 launch. The title distinguishes itself from its predecessor, Royal Match, by integrating a narrative-driven, fantasy-themed structure while adhering to a non-intrusive monetization model centered exclusively on in-app purchases. This strategic pivot, combined with a consistent biweekly content update cadence, has allowed the game to maintain a polished, snackable gameplay loop that effectively maximizes player retention.
The game’s financial success is underpinned by robust engagement metrics, including a 32.8% DAU/MAU ratio and a 9.5% retention rate at Day 30. These figures are supported by an aggressive, high-volume user acquisition strategy that leverages celebrity endorsements and creative advertising tactics to drive massive scale. By maintaining a $0.15 ARPDAU, the studio successfully converts this high-volume traffic into sustainable long-term revenue. The rapid growth of the title demonstrates the efficacy of balancing high-frequency content delivery with a refined core loop that appeals to a broad mobile audience.
Ultimately, the performance of Royal Kingdom highlights the continued viability of the match-3 genre when paired with sophisticated marketing and iterative development cycles. By prioritizing player retention through constant updates and utilizing high-impact acquisition channels, the game has solidified its position as a top-tier mobile product. The success of this launch underscores the importance of data-driven user acquisition and the ability to scale effectively in a competitive global market, providing a clear blueprint for modern mobile game monetization and growth.
- Dream Games' Royal Kingdom generated $145 million in revenue and reached 55 million downloads within its first year following its November 2024 launch.
- The game maintains strong player engagement with a 32.8% DAU/MAU ratio and a 9.5% Day 30 retention rate.
- Monetization is driven by a non-intrusive model focused solely on in-app purchases, resulting in an ARPDAU of $0.15.
- The studio sustains growth through a biweekly content update cadence that supports a polished, snackable match-3 gameplay loop.
- High-volume user acquisition is achieved through aggressive marketing tactics, including celebrity endorsements and creative advertising campaigns.
+4
UdonisAug 2025
Article
ASO vs Paid UA: What Drives More Installs?
The primary objective of this analysis is to evaluate the comparative effectiveness of App Store Optimization (ASO) and paid user acquisition (UA) in driving mobile game installs. The central thesis posits that while ASO is essential for long-term visibility and conversion optimization, paid UA is the superior strategy for achieving rapid, scalable growth. Rather than viewing these as competing methods, the analysis advocates for a synergistic approach where paid UA acts as the primary engine for volume, while ASO serves to maximize the efficiency and conversion rates of that incoming traffic.
Paid UA is identified as the most effective tool for immediate impact, offering precise audience targeting, measurable data, and the ability to iterate quickly based on real-time performance metrics. Conversely, ASO is characterized as a long-term, iterative process that relies on store algorithms and organic discovery. While ASO is often perceived as free, the analysis notes that it requires significant investment in time, creative assets, and ongoing maintenance to achieve meaningful results.
The findings emphasize a flywheel effect between the two strategies: paid UA drives the install velocity and engagement metrics that improve organic store rankings, while a well-optimized store page ensures that paid traffic converts at a higher rate. This integration reduces the overall cost per install (CPI) and improves return on ad spend (ROAS). Ultimately, the analysis concludes that for mobile game developers, the most effective growth strategy involves prioritizing paid UA for immediate scale while simultaneously implementing ASO to build sustainable, long-term momentum.
- Paid user acquisition is the most effective strategy for achieving immediate, scalable growth due to its precise targeting and real-time performance metrics.
- ASO functions as a long-term, iterative process that maximizes conversion rates for incoming traffic rather than acting as a primary driver of rapid volume.
- A synergistic approach creates a flywheel effect where paid UA increases install velocity, which in turn improves organic store rankings.
- Integrating ASO with paid UA reduces the overall cost per install (CPI) and improves return on ad spend (ROAS) by ensuring higher conversion rates for paid traffic.
- ASO is not a free strategy; it requires significant investment in time, creative assets, and ongoing maintenance to achieve meaningful results.
+2
UdonisJul 2025
Article
Gaming Industry Report: Market Size & Trends
The global gaming industry is experiencing a period of sustained expansion, with revenues reaching $187.7 billion in 2024 and a projected trajectory toward $205 billion by 2026. This growth is underpinned by a massive global player base of 3.3 billion individuals, heavily influenced by the accessibility of mobile gaming in emerging markets such as India, Mexico, and Turkey. Mobile platforms currently command 49% of total revenue, cementing their position as the primary driver of industry scale. While the market remains consolidated under major entities like Tencent, Sony, and Microsoft, the broader ecosystem is increasingly defined by a cross-platform development philosophy that prioritizes accessibility and long-term engagement through hybrid monetization models, including battle passes and subscription services.
Despite this financial growth, the industry is navigating a complex period of maturation and economic adjustment. Large-scale layoffs and a pivot toward risk-averse, franchise-focused AAA production reflect broader economic headwinds. Simultaneously, the esports sector is undergoing a significant financial correction, moving away from speculative investment toward sustainable, cost-efficient operational models. While cloud gaming and virtual reality remain in nascent stages of adoption, the integration of generative AI is emerging as a critical tool for enhancing development efficiency.
The industry is also contending with an evolving regulatory landscape, as increased scrutiny regarding data privacy, labor practices, and antitrust concerns necessitates greater operational transparency. The creator economy continues to serve as a vital pillar of industry health, with live-streaming viewership growing by 12% in 2024. Ultimately, the sector is transitioning from a phase of rapid, unchecked growth into a more stable, mainstream environment characterized by heightened regulatory oversight, a focus on operational sustainability, and a permanent shift toward digital-first, live-service experiences.
- The global gaming industry reached $187.7 billion in 2024 and is projected to grow to $205 billion by 2026, supported by a player base of 3.3 billion.
- Mobile gaming is the primary industry driver, accounting for 49% of total revenue and seeing significant expansion in emerging markets like India, Mexico, and Turkey.
- The industry is shifting toward a risk-averse, franchise-focused AAA production model, characterized by large-scale layoffs and a transition toward sustainable, live-service experiences.
- Market dominance remains concentrated among major entities such as Tencent, Sony, and Microsoft, while the broader ecosystem increasingly adopts cross-platform development and hybrid monetization models like battle passes.
- The esports sector is undergoing a financial correction, pivoting away from speculative investment toward cost-efficient, sustainable operational models.
+4
UdonisMar 2025
Article
Hearthstone Player Count, Revenue & Stats
This analysis examines the performance, player engagement, and financial trajectory of the digital card game Hearthstone through early 2026. Utilizing data from the mobile intelligence platform AppMagic, the findings highlight a title that remains a significant player in the digital card game genre, though it faces challenges regarding long-term user retention and consistent growth outside of major content cycles.
The game’s performance is characterized by high volatility tied to content updates. While monthly active users (MAU) and daily active users (DAU) remained relatively stable throughout early 2024, the game experienced a substantial surge in late 2024, with MAUs peaking at over 3.3 million and DAUs reaching approximately 503,000 in October. This spike correlates with a similar peak in revenue, which hit $19 million in October 2024. However, these figures typically decline significantly in the months following major releases, with revenue experiencing an 80% drop from the October peak by early 2025.
Demographically, the player base is primarily composed of individuals aged 18 to 34, with a notable 25% female representation. Geographically, the United States leads the player distribution at 18.3%, followed by Russia and Brazil. Engagement metrics remain strong for a strategy-based game, with an average session length of 38 minutes and a frequency of three sessions per day. Despite these engagement levels, long-term retention remains a hurdle; while Day 1 retention sits at 38%, it drops to 5% by Day 30, with only 0.6% of players remaining after one year.
With over 100 million lifetime downloads and $950 million in total revenue, the game maintains a high average revenue per daily active user (ARPDAU) of 1.03. The analysis concludes that while Hearthstone continues to thrive as a top-tier digital card game, its future stability depends on mitigating seasonal churn and improving long-term retention through more consistent engagement incentives.
- Hearthstone’s revenue is highly volatile, peaking at $19 million in October 2024 before suffering an 80% decline by early 2025.
- Long-term player retention is a critical challenge, with Day 1 retention at 38% plummeting to 5% by Day 30 and only 0.6% after one year.
- The game’s player base fluctuates significantly with content cycles, reaching a peak of 3.3 million monthly active users and 503,000 daily active users in October 2024.
- Hearthstone has achieved significant scale with over 100 million lifetime downloads and $950 million in total revenue to date.
- The game maintains a strong average revenue per daily active user (ARPDAU) of 1.03, supported by an average session length of 38 minutes.
+5
UdonisMar 2025
Article
Among Us Player Count, Revenue & Stats
The provided analysis examines the performance and lifecycle of the mobile game Among Us as of early 2026. The primary objective is to evaluate the game’s transition from a viral, hypergrowth phenomenon in 2020 to a mature, evergreen social title. By analyzing metrics such as player counts, revenue, and retention, the assessment illustrates how the game maintains a significant, albeit stabilized, user base through community-focused engagement rather than aggressive monetization.
Key findings indicate that while the game remains a prominent mobile title, it has experienced a substantial decline from its peak performance. Lifetime mobile downloads have reached 908.6 million, with 2025 contributing 70.2 million. Revenue has similarly cooled, totaling $60.4 million lifetime, with annual figures dropping from a 2020 high of $41.6 million to $1.8 million in 2025. Current engagement metrics show approximately 25.3 million monthly active users and an average session length of roughly 20 minutes. The monetization model remains intentionally lightweight, relying on optional cosmetic purchases and ad rewards rather than high-pressure gacha or progression mechanics, resulting in an average revenue per daily active user of less than $0.01.
The analysis utilizes data sourced from AppMagic, Sensor Tower, and Similarweb to track global performance trends from the game's 2018 launch through the first quarter of 2026. The methodology emphasizes the role of creator-led virality as the primary driver of the game's initial success, noting that the product’s inherent social design and "watchability" served as its most effective user acquisition strategy. The conclusion highlights that the game has successfully pivoted to a maintenance phase, utilizing live operations, cross-brand collaborations, and seasonal content to sustain long-term brand visibility and retain its core audience.
- Among Us has transitioned from a 2020 viral phenomenon to a mature title with 25.3 million monthly active users as of early 2026.
- Lifetime mobile downloads reached 908.6 million by early 2026, with 70.2 million of those occurring in 2025.
- Annual revenue dropped significantly from a peak of $41.6 million in 2020 to $1.8 million in 2025, totaling $60.4 million lifetime.
- The game maintains a lightweight monetization strategy, resulting in an average revenue per daily active user of less than $0.01.
- Current player engagement remains stable with an average session length of approximately 20 minutes.
+3
UdonisFeb 2025
Article
Honkai: Star Rail Player Count, Revenue & Statistics
Honkai: Star Rail maintains a significant presence in the global mobile gacha RPG market as of early 2026. While the title has transitioned from its initial launch-period peak in 2023, it continues to demonstrate robust monetization and stable engagement levels. The analysis, which utilizes data from AppMagic and Similarweb, focuses on the game’s performance across global mobile markets, highlighting its evolution from a high-growth launch phase to a mature, live-ops-driven product.
Key performance indicators for 2026 include 66.7 million lifetime mobile downloads and $1.76 billion in cumulative revenue. Although monthly active users (MAU) have declined from a peak of 18.5 million to approximately 7.3 million, the game retains a dedicated player base with an average of 2.1 million daily active users. Monetization remains highly efficient, characterized by an average revenue per download of $26.44 and a revenue per MAU of $4.29. Retention metrics show a 23.7% day-one rate, tapering to 2.5% by day 30.
The game’s success is attributed to a strategic combination of strong brand equity, effective character-focused creative marketing, and consistent live-ops content updates. User acquisition strategies have shifted from broad-reach campaigns to targeted efforts aimed at reactivation and content-driven engagement. Demographically, the audience leans male (68.8%) and is concentrated in the 18 to 24 age bracket, with significant interest in regions including Russia, the United States, Japan, South Korea, and Taiwan. The findings conclude that the game is currently in a mature growth phase, where long-term sustainability is supported by high-value player spending and ongoing community-focused marketing initiatives.
- Honkai: Star Rail has generated $1.76 billion in cumulative mobile revenue from 66.7 million lifetime downloads as of early 2026.
- The game has transitioned to a mature phase, with monthly active users (MAU) stabilizing at 7.3 million, down from a peak of 18.5 million.
- Daily active users (DAU) currently average 2.1 million, supported by a 23.7% day-one retention rate that settles to 2.5% by day 30.
- Monetization remains highly efficient, yielding an average revenue per download of $26.44 and a revenue per MAU of $4.29.
- The player base is primarily male (68.8%) and concentrated in the 18–24 age demographic, with key market presence in Russia, the U.S., Japan, South Korea, and Taiwan.
+3
UdonisFeb 2025
Article
Mobile Advertising Market: Size, Share & Growth
The global mobile advertising market is undergoing a period of robust expansion, with total expenditure reaching $402 billion in 2024 and an anticipated climb to $492 billion by 2026. This growth is primarily fueled by the ubiquity of smartphone usage and the increasing prevalence of short-form video content. Within this ecosystem, in-app advertising maintains a dominant position, representing more than 80 percent of mobile ad spend in the United States. Simultaneously, in-game advertising is experiencing consistent revenue gains as brands increasingly leverage immersive environments to capture consumer attention.
Technological advancements, particularly the integration of generative artificial intelligence and augmented reality, are fundamentally reshaping how brands engage with audiences. These tools allow for the creation of hyper-personalized experiences that help mitigate the challenges of rising ad fatigue. Furthermore, the industry is navigating a complex regulatory environment characterized by stricter privacy standards, which has necessitated a strategic shift toward advanced cross-channel attribution models. These methodologies are essential for maintaining precision in performance measurement while respecting evolving data protection requirements.
To remain competitive through 2026, market participants must prioritize operational agility and data-driven optimization. The convergence of game development and digital advertising requires a sophisticated approach to user acquisition, where user-friendly ad formats are balanced against the need for high-impact engagement. As the landscape continues to mature, success will depend on the ability to synthesize emerging AI capabilities with traditional marketing strategies to deliver seamless, relevant content across increasingly fragmented mobile platforms.
- The global mobile advertising market is projected to grow from $402 billion in 2024 to $492 billion by 2026.
- In-app advertising currently dominates the U.S. market, accounting for over 80 percent of total mobile ad expenditure.
- In-game advertising is seeing consistent revenue growth as brands increasingly utilize immersive environments to engage consumers.
- Generative AI and augmented reality are being integrated to create hyper-personalized content, specifically to combat rising consumer ad fatigue.
- Stricter global privacy regulations are forcing a strategic transition toward advanced cross-channel attribution models to maintain measurement precision.
+3
UdonisJan 2025
Article
AI in Game Development: How Studios Are Using It Today
Artificial intelligence has become a central component of modern game development, functioning primarily as a collaborative co-pilot rather than a replacement for human labor. Based on a 2024 survey of over 650 game developers, 73% of studios currently utilize AI tools, with 88% planning future integration. While leadership and executives show high adoption rates at 85%, creative roles such as artists report lower usage at 58%, reflecting ongoing concerns regarding job security and creative integrity.
The primary benefits of AI adoption are productivity gains rather than immediate cost reductions. Nearly 40% of studios report productivity increases exceeding 20%, while only 25% have achieved similar cost savings. Studios currently prioritize AI for design inspiration, storyboarding, and narrative generation. Conversely, adoption in areas like music generation and quality assurance remains limited due to concerns over technical accuracy and emotional depth. The most significant barrier to broader implementation is model quality and consistency, cited by 53% of respondents as a primary obstacle.
To address these challenges, 54% of studios express a preference for training or fine-tuning proprietary AI models to ensure artistic cohesion, protect intellectual property, and maintain narrative control. Looking forward, the industry is shifting toward runtime AI, with over half of studios exploring AI-driven non-player characters and real-time content generation. As AI models evolve, the role of human developers is expected to transition toward curation and high-level creative direction, balancing technical efficiency with the need for human oversight to maintain professional standards and original creative vision.
- 73% of game studios currently use AI tools, with 88% of organizations planning for future integration.
- AI adoption is primarily driving productivity, with nearly 40% of studios reporting efficiency gains exceeding 20%, while only 25% have achieved comparable cost savings.
- Model quality and consistency remain the primary barriers to implementation, cited by 53% of the 650 surveyed developers as the main obstacle.
- To protect intellectual property and ensure artistic cohesion, 54% of studios prefer training or fine-tuning their own proprietary AI models.
- While leadership adoption is high at 85%, creative roles like artists report lower usage at 58% due to concerns regarding job security and creative integrity.
+2
UdonisJan 2025
Article
Top 50 Biggest Gaming Companies in 2026 by Revenue
The global gaming industry is currently undergoing a period of robust expansion, with total market revenue projected to reach $363.2 billion by 2027. This growth is primarily fueled by a consolidation of market power among industry titans, strategic acquisitions, and the widespread adoption of subscription-based models and live-service titles. Sony, Tencent, and Microsoft remain the dominant forces, leveraging their massive infrastructure and intellectual property portfolios to maintain leadership positions within the competitive landscape.
The market hierarchy is characterized by a diverse ecosystem ranging from massive multinational conglomerates to specialized indie-focused studios. Established franchises such as Grand Theft Auto and Genshin Impact continue to serve as primary revenue drivers, underscoring the enduring value of high-quality, long-term content support. While mobile-first developers and MMORPG specialists occupy a significant portion of the mid-tier rankings, the industry remains highly stratified. Companies ranked between 32 and 50 demonstrate the breadth of this sector, with annual revenues spanning from $671 million down to $135 million, reflecting a healthy, albeit competitive, environment for international developers.
Geographically and operationally, the industry is increasingly defined by its reliance on recurring revenue streams and the strategic integration of mobile gaming platforms. The current landscape suggests that success is increasingly tied to a company's ability to sustain player engagement through live services rather than relying solely on one-time software sales. As the market approaches its 2027 revenue targets, the interplay between major publishers and niche developers continues to shape the trajectory of global gaming, highlighting a shift toward platform-agnostic growth and the persistent importance of established, high-performing intellectual property.
- The global gaming industry is projected to reach $363.2 billion in total revenue by 2027.
- Sony, Tencent, and Microsoft maintain their positions as the dominant industry leaders through massive infrastructure and extensive intellectual property portfolios.
- Market growth is primarily driven by the industry-wide shift toward subscription-based models and live-service titles that prioritize long-term player engagement over one-time sales.
- High-performing, established franchises like Grand Theft Auto and Genshin Impact remain the primary revenue engines for the sector.
- The industry remains highly stratified, with companies ranked 32 through 50 generating annual revenues ranging from $671 million down to $135 million.
+3
UdonisJul 2024
Article
Monetizing Magic: Insights from Harry Potter: Magic Awakened
Harry Potter: Magic Awakened represents a sophisticated evolution in mobile gaming, successfully synthesizing role-playing, real-time strategy, and collectible card game mechanics within a distinct storybook aesthetic. By leveraging the immense global appeal of the Harry Potter intellectual property, the title has achieved significant financial milestones, generating over $300 million in Asian markets and nearly $10 million globally. The core thesis driving this success is the integration of character collection as a primary meta-layer, a strategy that consistently proves effective in deepening player engagement and maximizing long-term retention across the mobile sector.
The monetization framework relies on a diversified approach that balances aggressive revenue generation with sustained player activity. By combining controversial gacha mechanics with more traditional revenue streams such as tiered battle passes, monthly subscriptions, and cosmetic vanity items, the game effectively captures value from a wide spectrum of player spending habits. This financial structure is bolstered by a robust live operations system, which utilizes both permanent and time-limited events to foster a sense of urgency. These recurring engagement loops ensure the gameplay experience remains dynamic, preventing stagnation while encouraging consistent daily participation.
Ultimately, the game serves as a benchmark for modern mobile development, demonstrating how complex monetization can be harmonized with high-quality design to maintain a competitive edge. The industry-wide trend toward character-driven progression models remains a critical pillar for developers seeking to optimize both user retention and lifetime value. By aligning narrative-driven content with structured task systems and exclusive reward cycles, the title establishes a sustainable model for long-term growth in the highly saturated global mobile gaming market.
- Harry Potter: Magic Awakened has generated over $300 million in Asian markets and nearly $10 million globally.
- The game utilizes a hybrid monetization model that combines gacha mechanics with tiered battle passes, monthly subscriptions, and cosmetic vanity items to capture diverse player spending habits.
- The core gameplay strategy integrates character collection as a primary meta-layer to deepen player engagement and maximize long-term retention.
- A robust live operations system featuring both permanent and time-limited events is used to create urgency and maintain consistent daily participation.
- The title demonstrates that harmonizing complex monetization with high-quality design and narrative-driven content is an effective strategy for growth in saturated mobile markets.
+2
UdonisFeb 2024
Article
How Many Downloads Does Subway Surfers Have?
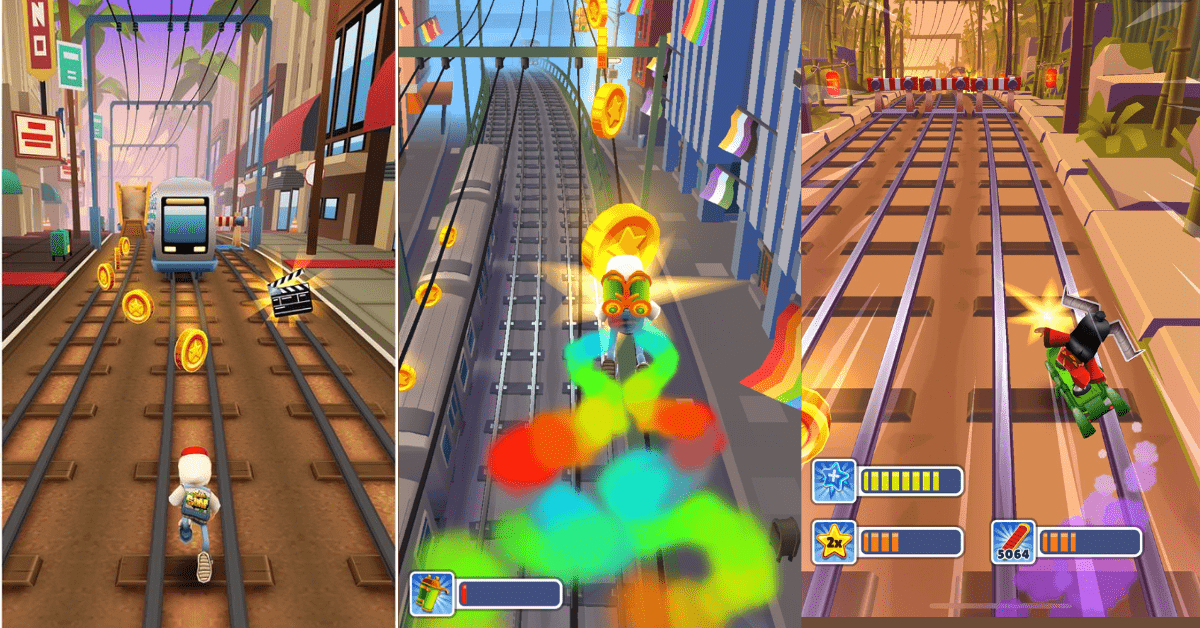
Subway Surfers stands as a landmark achievement in the mobile gaming industry, having secured over 4 billion lifetime downloads since its 2012 release. The title maintains a robust global presence with 20 million daily active users, driven by its accessible endless-runner mechanics and a sophisticated meta-layer of missions and social features. This enduring success is rooted in a design philosophy that balances intuitive gameplay with progressive difficulty, ensuring the title remains engaging for both casual participants and dedicated long-term players.
The game’s longevity is supported by a multifaceted engagement strategy that leverages over 160 collectible characters and frequent, time-limited events such as the recurring World Tour. By integrating a hybrid monetization model, the developers effectively combine rewarded video advertisements with in-app purchases, including currency bundles and permanent upgrades. This financial framework is bolstered by a dynamic marketing approach that utilizes TikTok, user-generated content, and vibrant ad creatives to sustain high acquisition rates and community growth.
Beyond core gameplay, the title utilizes consistent live operations and cross-promotion for spin-off projects to foster deep player loyalty. The integration of non-intrusive customization options and physical merchandise further extends the brand’s reach. These efforts are complemented by professional industry resources that emphasize the importance of strategic media buying, user acquisition, and platform-specific marketing solutions. Collectively, these elements demonstrate how a mobile title can maintain relevance and profitability for over a decade through continuous innovation and a deep understanding of player behavior.
- Subway Surfers has achieved over 4 billion lifetime downloads since its initial release in 2012.
- The game sustains a consistent player base of 20 million daily active users.
- Retention is driven by a content library featuring over 160 collectible characters and frequent, time-limited events like the World Tour.
- The title utilizes a hybrid monetization model that combines rewarded video advertisements with in-app purchases for currency and upgrades.
- Marketing strategy relies heavily on TikTok, user-generated content, and vibrant ad creatives to maintain high user acquisition rates.
+1
UdonisDec 2023