Pullup Entertainment
Game Co.14 documents
French game publisher (formerly Focus Entertainment). A Plague Tale, Warhammer: Vermintide, SnowRunner, Hardspace: Shipbreaker.
Documents

Financial53 pages
Semi-Annual Financial Report 2021-22: France
Focus Home Interactive’s financial performance for the first half of the 2021-22 fiscal year reflects a period of strategic transition characterized by a contraction in immediate earnings alongside aggressive structural expansion. Between April and September 2021, the company recorded €85.1 million in revenue, representing an 18% decline compared to the previous year, while operating profit fell by 60% to €7.3 million. This downturn was primarily attributed to pandemic-related development delays and the underperformance of certain titles, though the success of SnowRunner and a strong reliance on digital sales—which accounted for 88% of total revenue—provided essential stability.
To offset these headwinds, the company executed a comprehensive growth strategy focused on inorganic expansion and capital fortification. By acquiring Streum On Studio, Dotemu, and a majority stake in Douze-Dixièmes, the group significantly broadened its development pipeline and intellectual property portfolio. These acquisitions, coupled with a €140 million bank financing package and successful capital increases, bolstered the company’s cash position to €82.5 million. Management utilized these resources to secure long-term partnerships, such as the collaboration with Saber Interactive, and to invest heavily in future game development, evidenced by a rise in gross intangible assets to €130.9 million.
Despite the decline in profitability and a €2.9 million fine paid to the European Commission to resolve antitrust investigations, the company maintains a positive outlook. With a strengthened equity base and a clear commitment to its annual revenue target of €120–150 million, the organization is positioning itself for long-term scalability. The integration of new studios and a workforce expansion to 244 employees underscore a shift toward internalizing production capabilities, ensuring the company remains competitive within the French and broader international gaming markets.
- Focus Home Interactive reported an 18% revenue decline to €85.1 million and a 60% drop in operating profit to €7.3 million for the first half of the 2021-22 fiscal year.
- The company aggressively expanded its development capabilities through the acquisitions of Streum On Studio, Dotemu, and a majority stake in Douze-Dixièmes.
- Digital sales remained a critical revenue driver, accounting for 88% of total turnover during the April to September 2021 period.
- A €140 million financing package and capital increases bolstered the company's cash position to €82.5 million, supporting a rise in gross intangible assets to €130.9 million.
- Despite a €2.9 million antitrust fine paid to the European Commission, the company maintains an annual revenue target of €120–150 million.
+1
Pullup Entertainment

Financial31 pages
Rapport Financier Semestriel S1 2024/2025: France
PULLUP Entertainment achieved a significant financial turnaround during the first half of the 2024/2025 fiscal year, reporting a record revenue of €234.3 million compared to €85 million in the prior year. This growth was primarily driven by the commercial success of Warhammer 40,000: Space Marine 2, which propelled digital sales to account for 89% of total revenue. The company successfully transitioned to a net profit of €22.1 million, bolstered by a strategic capital increase of approximately €23 million and a comprehensive organizational restructuring that included the filialization of its publishing division.
The group’s financial health is supported by a diversified funding structure, including senior loans and BPI financing, alongside €20 million in undrawn credit lines. Operational stability is maintained through rigorous accounting practices, such as the amortization of development costs over 12 to 36 months and the consolidation of various studios under both full integration and equity methods. Despite these gains, the company maintains a net debt of €127.2 million and remains subject to specific risks, including a high dependency on partner studio SABER Interactive, which accounts for nearly 30% of projected investments. Exposure to currency fluctuations remains a factor, as 60% of revenue is generated in U.S. dollars.
Strategic portfolio management remains a priority, evidenced by recent minority stake acquisitions in Rundisc and Uppercut Games, contrasted with the divestment from Streum On Studio. While the company faces inherent industry challenges—such as intense competition and the volatility of development cycles—the current financial position is stable, with auditors confirming the accuracy of the consolidated accounts as of September 30, 2024. Future growth is supported by ongoing contractual options for the acquisition of minority interests in subsidiaries like Dovetail Games and Carpool Studio, ensuring a continued focus on long-term expansion within the global video game market.
- PULLUP Entertainment achieved a record revenue of €234.3 million in H1 2024/2025, a significant increase from €85 million in the prior year, driven primarily by the success of Warhammer 40,000: Space Marine 2.
- The company transitioned to a net profit of €22.1 million, supported by a €23 million capital increase and an organizational restructuring that included the filialization of its publishing division.
- Digital sales now account for 89% of total revenue, though the company remains exposed to currency fluctuations with 60% of its revenue generated in U.S. dollars.
- Despite improved profitability, the group carries a net debt of €127.2 million and maintains a high dependency on partner studio SABER Interactive, which represents nearly 30% of projected investments.
- Financial stability is bolstered by a diversified funding structure, including senior loans, BPI financing, and €20 million in undrawn credit lines.
+1
Pullup Entertainment
Financial1 pages
PulluP Entertainment FY25 Earnings Release
PulluP Entertainment reported full‑year earnings for FY 2025/26, ending March 31 2026. Revenue fell 27.8 % to €281.4 million, largely due to a sharp decline in new‑release sales (down 68 % to €82.3 million). Back‑catalogue revenue, however, surged 52.9 % to €189.0 million, representing 67 % of total sales and reflecting the group’s shift toward recurring revenue streams and live‑service operations. Adjusted EBIT contracted 79 % to €12.6 million, while the group recorded a net loss of €12.9 million (diluted earnings per share –€1.62). EBITDA fell 43 % to €79.6 million, and operating cash flow dropped sharply to €6.5 million from €52.1 million the prior year, driven by higher working‑capital requirements and disciplined CAPEX of €84.4 million.
Net debt increased to €85.7 million, up from €70.1 million, as the company maintained a solid balance sheet to support future growth. The FY 2026/27 line‑up will feature more than ten titles across the group’s publishing divisions, including new releases such as Resonance: A Plague Tale Legacy, Road Kings, and Gallipoli WW1 Game Series, alongside continued live‑service content for Warhammer 40,000: Space Marine 2 and Marvel Cosmic Invasion. Beyond FY 2026/27, the pipeline contains roughly 15 core projects, notably Warhammer 40,000: Space Marine 3 and two in‑house IPs from Carpool Studio and Deck13.
Geographically, the group operates across Europe with a workforce of over 600 employees. The financial data derive from consolidated statements prepared under French accounting standards, with adjustments for goodwill amortisation, tax credits, and restructuring impacts. The report underscores a strategic pivot toward IP strengthening, live‑service monetisation, and disciplined capital allocation to sustain long‑term value creation.
- PulluP Entertainment reported a 27.8% revenue decline to €281.4 million for FY 2025/26, driven by a 68% drop in new-release sales to €82.3 million.
- The company recorded a net loss of €12.9 million and an adjusted EBIT contraction of 79% to €12.6 million, while operating cash flow plummeted from €52.1 million to €6.5 million.
- Back-catalogue revenue grew 52.9% to €189.0 million, now accounting for 67% of total sales as the company shifts focus toward recurring revenue and live-service operations.
- Net debt increased to €85.7 million, supported by €84.4 million in capital expenditures as the firm maintains its balance sheet for future growth.
- The FY 2026/27 release slate includes over ten titles, such as 'Resonance: A Plague Tale Legacy' and 'Road Kings', alongside ongoing live-service support for 'Warhammer 40,000: Space Marine 2'.
+2
Pullup Entertainment
Report83 pages
Annual Financial Report: 2019/20
1. FOCUS HOME INTERACTIVE presentation pages 5 to 9 2. Declaration by the person responsible page 11 3. Management Board’s report pages 15 to 33 4. Supervisory Board’s report pages 37 to 41 5.
- Focus Home Interactive's gross profit grew 20% to €36.6M, with a gross margin of 31% (up from 29% last year), and operating profit increased 36% to €19.2M for the year ended March 31, 2020.
- The Group held a net cash position of €18M on March 31, 2020.
- Focus Home Interactive has established new collaborations with Saber (for new projects and porting existing titles to Nintendo Switch and mobile) and Sumo Digital (for a new multiplayer game developed by Sumo Newcastle).
- The company successfully released "World War Z" in April 2019, developed with Saber and based on the Paramount film.
- Focus Home Interactive held 8,295 of its own shares valued at €148,978 as part of a liquidity contract and an additional 151,759 shares under its stock buyback program as of March 31, 2020.
+1
Pullup Entertainment
Report106 pages
Annual Financial and Corporate Social Responsibility Report: 2020/21
ANNUAL FINANCIAL REPORT AT 31 MARCH 2021 1. Introduction pages 5 to 9 2. Declaration by the person responsible page 11 3. Management Board’s report pages 13 to 34 4. Supervisory Board’s report pages 35 to 43 5.
- Focus Home Interactive's revenue increased significantly from €137.8M in 2020 to €166.5M in 2021, with net income totaling €14.7M for the year ended March 31, 2021.
- The company's balance sheet assets grew from €90.9M in March 2020 to €122M in March 2021, and equity increased from €57.7M to €72.4M during the same period.
- Focus Home Interactive bought back 127,753 shares in 2020/21, down from 151,759 shares the previous year, and sold 36,015 shares, with 27,099 used to acquire Deck 13 Interactive.
- The Supervisory Board saw significant changes, with Fabrice Larue appointed Chairman on July 27, 2020, replacing Denis Thébaud, and new members Louise Tingström and Thaima Samman appointed on April 16, 2021.
- Focus Home Interactive faces currency risks, particularly with the US dollar and British pound, and uses hedging strategies to mitigate potential impacts on profitability.
Pullup Entertainment
Report97 pages
Annual Financial Report and CSR Report: 2021/2022
ANNUAL FINANCIAL REPORT AS OF 31 MARCH 2022 1. INTRODUCTION pages 3 to 7 2. DECLARATION BY THE PERSON RESPONSIBLE page 8 3. MANAGEMENT REPORT pages 9 to 24 4. BOARD REPORT ON CORPORATE GOVERNANCE pages 25 to 33 5. AUDITOR’S REPORT ON THE CONSOLIDATED FINANCIAL STATEMENTS FOR YEAR ENDED 31 MARCH 2022 pages 34 to 36 6.
- Focus Entertainment acquired 77.5% of Dotemu for €53.5M on September 30, 2021, resulting in goodwill of €60.7M and significantly increasing the gross value of goodwill from €6.257M to €72.747M.
- The company's commitments to studios and right holders dramatically increased from €39.290M in 2021 to €120.786M in 2022, with €59.183M due within one year.
- Focus Entertainment paid a €2.9M fine to the European Commission on July 12, 2021, related to an investigation into alleged technical and contractual restrictions on PC game circulation in Europe.
- The proportion of sales billed in US dollars was 55% of consolidated revenue as of March 31, 2022, exposing the company to currency risk, though game sales in USD can partially offset USD-denominated costs.
- The company bought back 181,643 shares by March 31, 2022, as part of a program authorizing the buyback of up to 250,000 shares, and held 299,365 of its own shares at that date.
+2
Pullup Entertainment
Report97 pages
Annual Financial Report and CSR Report: 2022/2023
ANNUAL FINANCIAL REPORT AS OF 31 MARCH 2023 1. INTRODUCTION pages 3 to 7 2. DECLARATION BY THE CHIEF EXECUTIVE OFFICER page 8 3. MANAGEMENT REPORT pages 9 to 24 4. REPORT ON CORPORATE GOVERNANCE pages 25 to 34 5. STATUTORY AUDITORS’ REPORT ON THE CONSOLIDATED FINANCIAL STATEMENTS AS OF 31 MARCH 2023 pages 35 to 37 6.
- On June 16, 2022, Dotemu successfully launched Teenage Mutant Ninja Turtles: Shredder’s Revenge, selling over 1 million copies within one week of its release for PC, Nintendo Switch, PlayStation 4, and Xbox One.
- On September 5, 2022, FOCUS ENTERTAINMENT acquired 66.67% of WW1 Game Series B.V. (renamed BlackMill Games B.V.) for €5.5 million, making it the sixth development studio to join the Group.
- The company changed its name from Focus Home Interactive to FOCUS ENTERTAINMENT on April 1, 2022, to better reflect its main business lines and values.
- Goodwill increased by €3,151 from March 31, 2022, to March 31, 2023, reaching €71,826, though Dotemu's goodwill decreased by €8,886 during the same period.
- The average workforce increased from 307 on March 31, 2022, to 398 on March 31, 2023, with significant growth in production roles (201 to 269) and administration (52 to 85).
+2
Pullup Entertainment
Report106 pages
Annual Financial Report and CSR Report: 2023-2024
ANNUAL FINANCIAL REPORT AS OF 31 MARCH 2024 1. INTRODUCTION pages 3 to 6 2. DECLARATION BY THE CHIEF EXECUTIVE OFFICER page 7 3. MANAGEMENT REPORT pages 8 to 26 4. REPORT ON CORPORATE GOVERNANCE pages 27 to 38 ON THE CONSOLIDATED FINANCIAL STATEMENTS AS OF 31 MARCH 2024 pages 39 to 40 6.
- PULLUP Entertainment (formerly FOCUS ENTERTAINMENT) reported a consolidated net loss of €19,244K for the financial year ended March 31, 2024, a significant decrease from the €10,261K net profit in the previous year, representing a 288% decline.
- Revenue decreased by 3% to €187,334K as of March 31, 2024, from €194,104K in the prior year, while game development costs nearly doubled, increasing by 99% to €64,726K from €32,509K.
- The company acquired UK studio Dovetail Games, known for simulation franchises like Train Simulator Classic and Train Sim World, with the acquisition consolidated into PULLUP Entertainment's accounts from April 20, 2023, and expected to have a slightly accretive impact on profit margin.
- PULLUP Entertainment drew an additional €20M on its credit line for the Dovetail Games acquisition and pledged 50.1% of Dotemu shares and 98% of Dovetail Games Holding shares to creditors.
- The company's net debt increased significantly from €27,260K to €132,646K as of March 31, 2024, primarily due to new bank loans totaling €70,500K.
+1
Pullup Entertainment
Report36 pages
Half-Year Financial Report: S1 2025/2026
RAPPORT FINANCIER SEMESTRIEL S1 2025/2026 1. ATTESTATION DE LA PERSONNE RESPONSABLE page 3 2. RAPPORT DE GESTION pages 4 à 10 3. RAPPORT D’EXAMEN LIMITÉ DES COMMISSAIRES AUX COMPTES SUR LES COMPTES CONSOLIDÉS SEMESTRIELS page 11 4.
- PULLUP Entertainment refinanced its senior debt on July 30, 2025, securing €168 million in new bank financing, replacing an existing syndicated credit of €117.5 million that was due in 2028.
- The company's equity (Capitaux propres) decreased from €166,475k on March 31, 2025, to €156,808k on September 30, 2025.
- PULLUP Entertainment expanded its executive committee with the appointment of Geoffroy Sardin as Deputy CEO for operational management (effective April 1, 2025) and Marion Dufour as HR Director.
- The Group's workforce increased from 606 employees on March 31, 2025, to 623 employees on September 30, 2025, with notable growth in Focus Entertainment Publishing (166 to 174), Deck13 (83 to 87), and Dovetail (182 to 186).
- Commitments to studios and rights holders decreased from €111,806k on March 31, 2025, to €86,490k on September 30, 2025, with the majority (€81,077k) owed to studios.
Pullup Entertainment
Financial36 pages
Rapport Financier Semestriel S1 2025/2026
PULLUP Entertainment’s financial performance for the first half of the 2025/2026 fiscal year, ending September 30, 2025, reflects a transitional period characterized by a lack of major new releases compared to the previous year’s record-breaking results. Revenue declined 43% to €132.6 million, while net income dropped 91% to €2.1 million. Despite the absence of a blockbuster launch comparable to the prior year, the back-catalogue achieved record revenues of €93.7 million, a 44.4% increase. This shift toward digital dominance is evident, with digital sales now accounting for 94% of total turnover.
The strategic focus remains on long-term stability and portfolio diversification to mitigate operational risks. A significant portion of the Group’s projected investments over the next three years is tied to Saber Interactive, representing a 30% dependency that the company is addressing through internal studio acquisitions and partnerships, such as the ongoing collaboration with Games Workshop. To support this growth and manage liquidity, the Group secured a new €168 million syndicated loan in July 2025. This financing package, combined with €48 million in undrawn credit lines, positions the company to pursue external growth and meet its €86.5 million in outstanding commitments to studios and rights holders.
Operational adjustments include the appointment of a new Deputy CEO and the consolidation of ownership in key subsidiaries like Dotemu, Blackmill Games, and Carpool Studio. While net debt rose to €84.8 million due to a decrease in cash reserves, the Group maintains a robust asset base with €181.3 million in net intangible assets, primarily driven by ongoing game development. Despite the first-half downturn, the Group confirms its outlook to exceed the 2022/2023 record performance for the full fiscal year, supported by a disciplined capitalization strategy and a stable international studio network.
- PULLUP Entertainment reported a 43% revenue decline to €132.6 million and a 91% drop in net income to €2.1 million for H1 2025/2026, primarily due to the absence of major new releases.
- The company’s back-catalogue achieved record revenues of €93.7 million, a 44.4% increase, with digital sales now accounting for 94% of total turnover.
- To support growth and manage liquidity, the Group secured a €168 million syndicated loan in July 2025, supplementing €48 million in undrawn credit lines to cover €86.5 million in outstanding commitments.
- The company is actively working to reduce its 30% dependency on Saber Interactive through internal studio acquisitions and partnerships, including a collaboration with Games Workshop.
- Net debt rose to €84.8 million, while the Group maintains a strong asset base of €181.3 million in net intangible assets driven by ongoing game development.
Pullup EntertainmentSept 2025
Financial101 pages
Annual Financial Report and Non-Financial Performance Statement 2024-2025
PULLUP Entertainment, formerly Focus Entertainment, achieved a transformative financial recovery during the 2024/25 fiscal year, characterized by record-breaking growth and a strategic corporate reorganization. The Group reported a 108% year-over-year revenue increase to €390.0 million, swinging from a €19.9 million loss in the previous period to a consolidated net profit of €19.4 million. This performance was primarily catalyzed by the massive commercial success of Warhammer 40,000: Space Marine 2, which reached over 7 million players, alongside a resilient back-catalogue strategy where digital sales now account for 91% of total turnover.
The Group’s financial position strengthened significantly, with net debt nearly halved from €132.6 million to €70.1 million. This deleveraging was supported by a €23.1 million capital increase and robust cash generation, leaving the company with €61.7 million in available liquidity. Strategically, the period marked a transition to an operational holding model following the spin-off of its publishing business. The Group is now organized into three core divisions—Publishing, Dotemu, and Development Studios—supported by ten acquisitions since 2020. While the company faces risks from a 30% investment dependency on Saber Interactive and reliance on digital platforms like Steam, it has mitigated these through increased ownership of internal intellectual property and a multi-year partnership with Mattel.
Geographically, the Americas remains the dominant market, representing 53% of sales following a 137% regional surge. Beyond financial metrics, the Group improved its social and governance performance, reducing employee attrition from 17.2% to 9.8% and maintaining a 100% implementation rate for player safety systems in multiplayer titles. Despite an increase in total greenhouse gas emissions to 9,889.3 TeqCO2 due to expanded reporting and physical product success, the Group remains committed to its CSR strategy focusing on talent retention, climate action, and cybersecurity. With the announcement of Warhammer 40,000: Space Marine 3 and a proposed dividend of €1 per share, the Group has positioned itself for long-term sustainable growth.
- PULLUP Entertainment achieved a financial turnaround in 2024/25, reporting a 108% revenue increase to €390.0 million and a net profit of €19.4 million, compared to a €19.9 million loss the previous year.
- The commercial success of Warhammer 40,000: Space Marine 2, which attracted over 7 million players, served as the primary catalyst for the company's record-breaking growth.
- The company significantly improved its balance sheet by nearly halving net debt from €132.6 million to €70.1 million, supported by a €23.1 million capital increase and strong cash generation.
- PULLUP transitioned to an operational holding model structured into three core divisions—Publishing, Dotemu, and Development Studios—following the spin-off of its publishing business.
- The Americas region remains the company's largest market, accounting for 53% of total sales after experiencing a 137% year-over-year surge.
+1
Pullup EntertainmentJan 2025
Financial5 pages
Pullup Entertainment Reports 2024/25 Full-Year Revenue
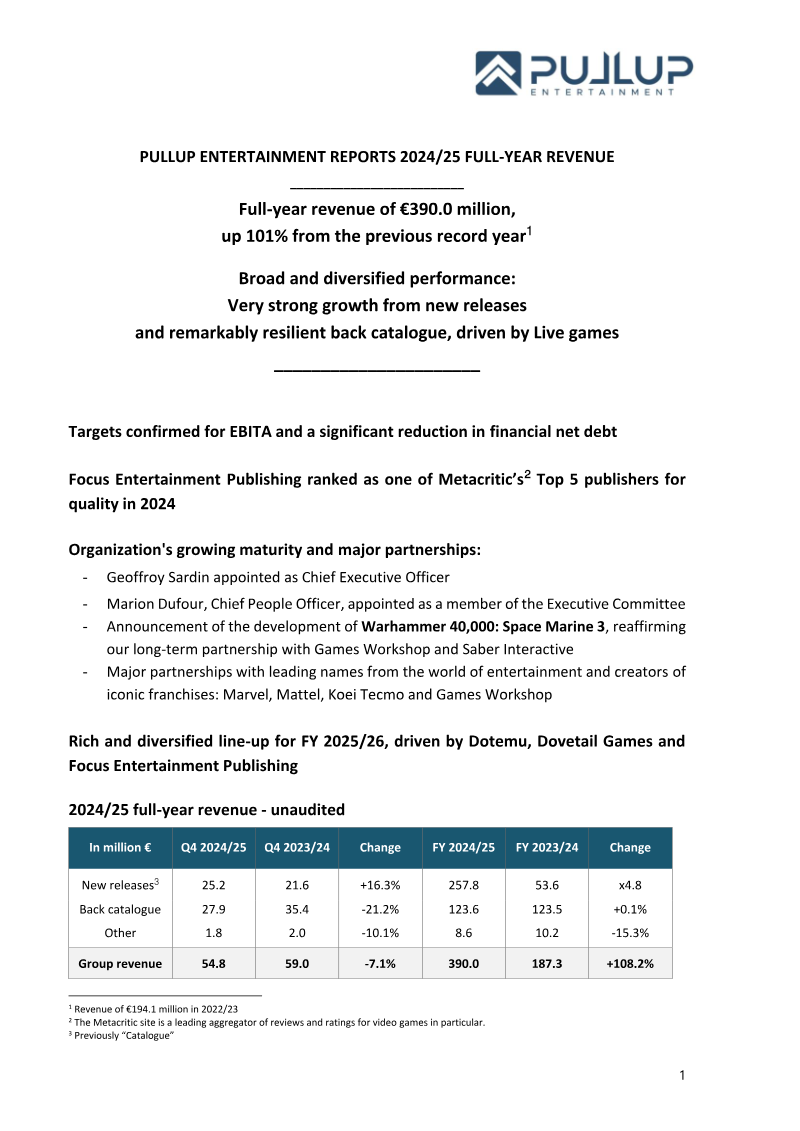
Pullup Entertainment announced a full‑year revenue of €390 million for FY 2024/25, representing a 108 % increase over the prior year and a 101 % rise compared with the previous record of €194 million in 2022/23. The surge was driven primarily by new releases, which generated €257.8 million—four‑fold growth year‑on‑year—while the back‑catalogue remained stable at €123.6 million, underscoring the resilience of live‑service titles such as SnowRunner and Insurgency: Sandstorm. Quarterly revenue fell 7.1 % to €54.8 million, reflecting a modest dip in Q4 sales despite strong performance from recent launches like Warhammer 40,000: Space Marine 2 and Train Sim World 5.
The company confirmed EBITA targets of €55‑60 million, roughly doubling the best result from FY 2022/23, and highlighted a significant reduction in net debt achieved through robust operational cash flow. Strategic positioning in the AA and independent segments, coupled with high‑quality, distinctive titles, was cited as the foundation of the growth, while partnerships with marquee brands—including Marvel, Mattel, Koei Tecmo and Games Workshop—expanded the pipeline of licensed and original IPs. Leadership changes reinforced governance, with Geoffroy Sardin appointed CEO and Marion Dufour joining the executive committee as Chief People Officer.
Looking ahead to FY 2025/26, the firm outlined a diversified slate of upcoming releases across its Focus Entertainment Publishing and Dotemu divisions, featuring new IPs such as Memories in Orbit, Roadcraft, Ninja Gaiden: Ragebound and Marvel Cosmic Invasion, alongside continued live‑service support. The outlook emphasizes exceeding the record revenue and EBITA levels set in 2022‑23, leveraging both fresh titles and the enduring strength of its back‑catalogue. The report covers Pullup’s European operations, encompassing over 600 employees and six development studios, and reflects data drawn from unaudited financial statements for the fiscal year ending 31 March 2025.
- Pullup Entertainment reported record FY 2024/25 revenue of €390 million, a 108% increase year-on-year and a 101% rise over the previous 2022/23 record.
- New releases were the primary growth driver, generating €257.8 million—a four-fold increase—while the back-catalogue remained stable at €123.6 million, supported by titles like SnowRunner and Insurgency: Sandstorm.
- The company projects EBITA of €55–60 million for the fiscal year, approximately doubling its previous best result from 2022/23, while simultaneously reducing net debt.
- Q4 revenue saw a 7.1% decline to €54.8 million, despite contributions from recent launches including Warhammer 40,000: Space Marine 2 and Train Sim World 5.
- Strategic growth is anchored in partnerships with brands such as Marvel, Mattel, Koei Tecmo, and Games Workshop to expand the pipeline of licensed and original IPs.
+1
Pullup EntertainmentJan 2025