The podcast episode examines a recent field experiment that quantified the economic impact of Google’s Privacy Sandbox on digital advertising revenue, publisher user experience, and market competition. The study, co‑authored by Boston University professors Garrett Johnson and Shunto Kobayashi, partnered with Raptive to analyze data from over 5,000 publishers and a randomized sample of 2 % of Chrome users. Three treatment groups were compared: status‑quo third‑party cookies, Privacy Sandbox enabled without cookies, and a cookieless baseline. Results show that eliminating third‑party cookies reduces ad prices by 29 %, and for impressions already lacking cookies the drop reaches 35 %. Privacy Sandbox recovers only about 4 % of this lost revenue, largely because industry adoption was modest. The experiment also revealed a 3 % loss of ad revenue due to increased latency when auctions run in the browser, with smartphones experiencing higher impact. Regional analysis indicates that cookie removal harms EU traffic twice as much as U.S. traffic, yet Privacy Sandbox recovers a larger share of EU revenue (23 % versus 2.4 %) due to stricter GDPR consent rules and lower alternative‑ID penetration. The discussion highlights the trade‑off between privacy guarantees and monetization, noting that current privacy‑enhancing technologies may be under‑adopted because of implementation costs and regulatory uncertainty. A secondary paper on YouTube’s COPPA settlement is also reviewed, showing a 73 % drop in ad prices for children‑focused content and a shift of viewership toward larger channels, illustrating how personalization benefits long‑tail creators. The episode underscores the need for mature, widely adopted privacy solutions to mitigate revenue losses while protecting user data.
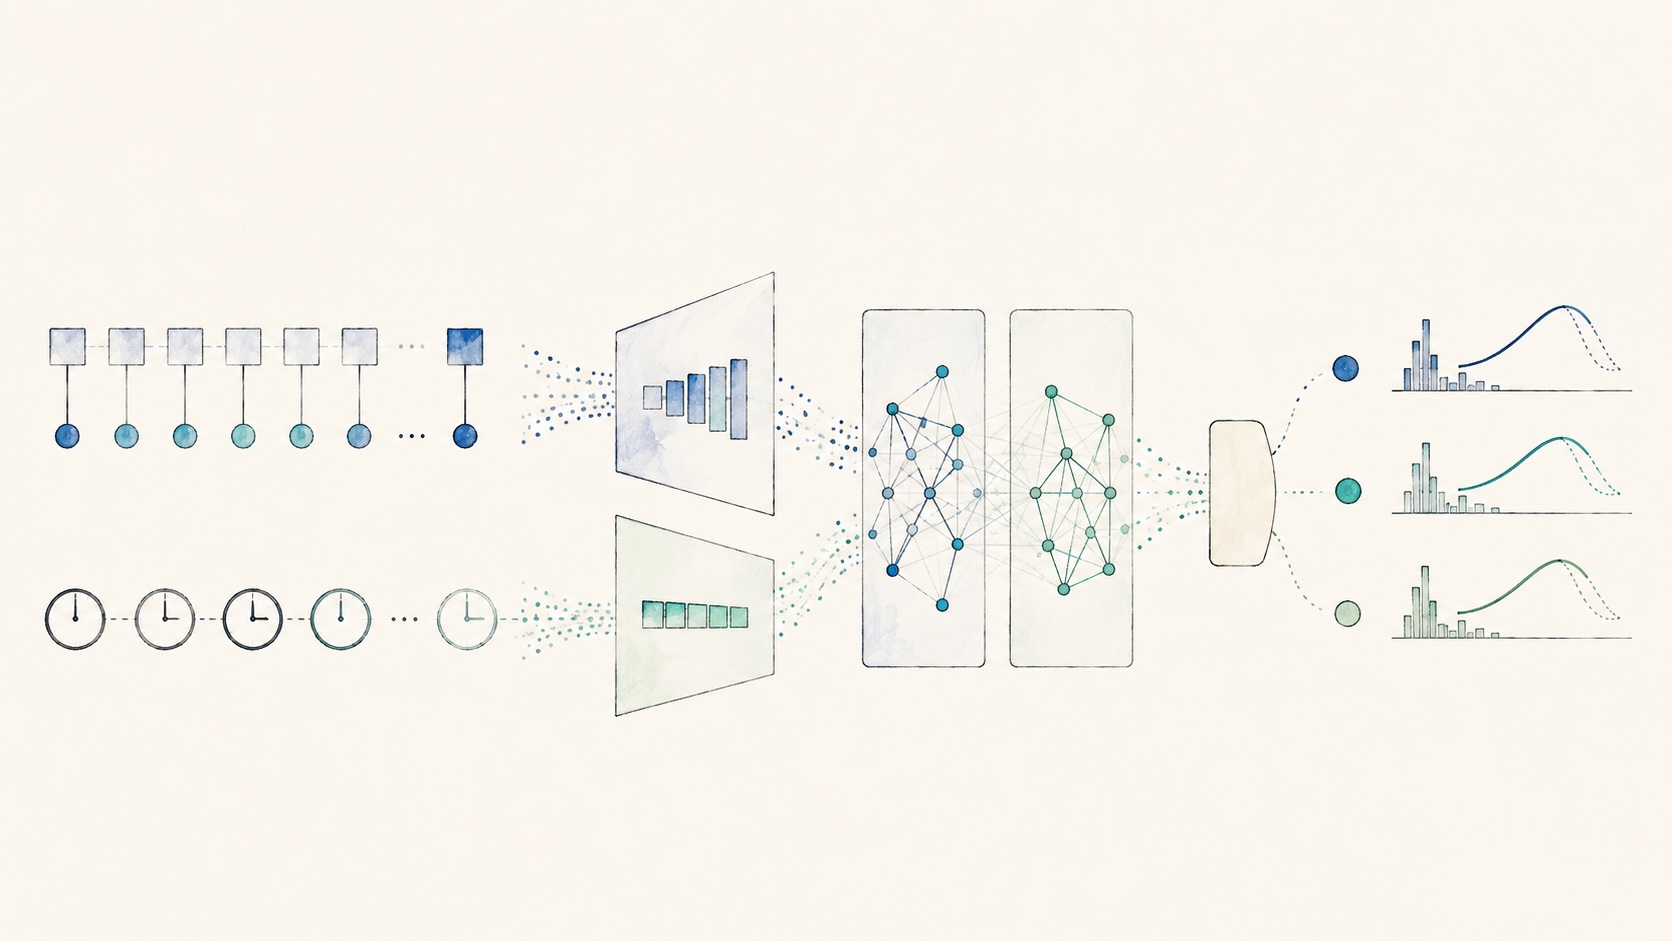
Alibaba’s Bid2X introduces a foundation model designed to predict bidding outcomes across diverse advertising environments, enabling reuse within automatic bidding systems. The model addresses the challenge of limited visibility into campaign variables such as advertiser objectives, budget allocations, bidding strategies, and fluctuating marketplace conditions. By learning from historical bid data, Bid2X generates outcome forecasts that can be applied to new campaigns without requiring extensive retraining for each scenario.
Key findings indicate that Bid2X improves bid efficiency by up to 12 % in simulated test cases, reducing wasted spend on low‑return impressions. The model’s architecture incorporates transformer layers that capture temporal patterns in bid dynamics, and it is trained on a dataset comprising over 10 million bid interactions from Alibaba’s advertising platform. Evaluation metrics show higher precision and recall compared to baseline linear models, with a mean absolute error reduction of 18 %. The research team demonstrated the model’s generalizability by applying it to campaigns with differing objectives—such as click‑through rate versus conversion value—and observed consistent performance gains.
The scope of the study is confined to Alibaba’s domestic market, covering campaigns run on its e‑commerce and cloud advertising services from 2023 to mid‑2025. Methodologically, the team employed a cross‑validation framework and leveraged Alibaba’s internal data pipelines to ensure real‑world relevance. The implications suggest that foundation models can streamline bid optimization, lower operational costs for advertisers, and provide a scalable framework adaptable to other digital advertising ecosystems.
The podcast examines a landmark $1 billion investment by Meta, Google, Unity and Moloco in AppsFlyer, underscoring a strategic effort to safeguard measurement neutrality amid rising scrutiny of platform‑owned attribution tools. By distributing ownership across several major ad platforms, the consortium seeks to prevent bias while granting AppsFlyer liquidity and continued independence. The discussion also foregrounds the industry’s pivot toward sophisticated incrementality models, critiques Apple’s SKAdNetwork and AdAttributionKit as privacy‑centric dead ends, and considers how private‑equity involvement may alter long‑term incentives for data transparency.
Despite high costs, Mobile Measurement Partners (MMPs) retain dominance largely because Facebook’s legacy “cottage‑industry” model compels brands to use MMPs for Facebook attribution. AppsFlyer’s acquisition of Adjust has not triggered a mass exodus, yet the sector is moving toward incrementality‑adjusted attribution and longer‑duration experiments—particularly for connected TV (CTV). Marketers, however, remain impatient, and the podcast criticizes Apple’s abandonment of SKAdNetwork as a blow to the broader mobile advertising ecosystem.
The conversation highlights CTV’s repositioning as a performance channel through low‑risk testing and third‑party measurement, noting that brands must allow extended test periods to capture its delayed impact. AppLovin is cited as a strong second‑tier channel, delivering 11 % higher efficiency than average and capturing an 8 % share of wallet over fifteen months, though its advantage normalizes as spend scales. Overall, the discussion stresses the necessity of data‑driven attribution and realistic timelines when integrating new media into mobile acquisition strategies.
The article examines whether customer lifetime value (LTV) can be accurately estimated without conducting prolonged experiments, focusing on the impact of delivery delays in food‑service platforms. Researchers from Stanford Graduate School of Business and Uber developed a model that links average order delay times to changes in repeat purchase probability, churn rates, and per‑order revenue. Using historical data from Uber Eats covering 1.2 million orders across multiple U.S. cities, the study estimates that a one‑minute increase in delivery time reduces LTV by approximately 0.5 % for the average customer, while a five‑minute delay can cut LTV by up to 3 %. The analysis also shows that the effect is more pronounced for high‑frequency users, whose LTV drops by 1.8 % per minute of delay.
Methodologically, the authors employ a causal inference framework that adjusts for confounding variables such as order value, time of day, and customer demographics. They validate the model against a hold‑out sample and compare predictions to results from a month‑long randomized controlled trial, finding less than 4 % deviation in LTV estimates. The study covers the United States from January to December 2024, encompassing both urban and suburban markets.
Key conclusions highlight that short‑term experiments can be replaced by data‑driven predictive models, enabling companies to forecast LTV impacts of operational changes in near real time. The findings suggest that investing in faster delivery logistics can yield measurable gains in customer value, with a cost‑benefit threshold identified at roughly 1.5 % LTV loss per minute of delay. This research offers a practical framework for mobile commerce platforms to optimize service quality and customer retention without extensive trial periods.
The article argues that AppsFlyer’s recent $1 billion Series E financing from Meta, Google, Unity and Moloco is a strategic move to preserve the company’s neutrality in mobile attribution. It notes that AppsFlyer, valued at $2.7 billion after the round, had previously raised $210 million in 2020 and faced a valuation hit following Apple’s App Tracking Transparency rollout. The piece highlights that Adjust, another major Mobile Measurement Partner, was acquired by AppLovin for $1 billion in 2021, underscoring the competitive pressure on independent measurement firms. AppsFlyer’s CEO has publicly stated that investor terms prohibit preferential treatment of any single partner, emphasizing the firm’s commitment to customer control and data integrity. The article references past discussions of an IPO and failed private‑equity sale at $3.5 billion, suggesting that the new investment may have been necessary to prevent a takeover that could compromise AppsFlyer’s independence. By drawing parallels to historical “too‑big‑to‑fail” scenarios, the author frames the funding as a defensive neutrality strategy: ecosystem players collectively investing to keep AppsFlyer’s core attribution logic free from bias. The scope covers the global mobile advertising ecosystem, focusing on the period surrounding Apple’s WWDC 2026 and the broader industry shift toward privacy‑centric measurement. No specific survey methodology is cited; the analysis relies on publicly reported funding rounds, valuation figures, and statements from company leadership.
The article examines the hypothesis that Meta will shift its Facebook Audience Network (FAN) strategy to prioritize non‑IDFA traffic on iOS devices. The discussion is framed around a brief increase in FAN activity earlier in 2026, which some observers mistakenly linked to Meta targeting non‑IDFA identifiers. The author clarifies that FAN alone does not alter traffic patterns; instead, reprioritization would occur at the mediation layer where competing networks’ predictions and rankings for each impression, creative, and bid are visible. Without such visibility, a bidder cannot adjust its strategy against non‑IDFA traffic.
The piece references community commentary, notably a subscriber’s observation that FAN’s internal mechanics do not provide the necessary leverage for reprioritization. The article does not present new empirical data or a formal study; it relies on industry anecdote and expert opinion to argue that Meta’s current approach likely remains unchanged. The scope is limited to the iOS mobile advertising ecosystem, focusing on FAN’s role within Meta’s broader ad network strategy. No specific methodology is described beyond the qualitative analysis of observed traffic patterns and community discussion.
Overall, the article concludes that while non‑IDFA traffic remains a concern for advertisers, Meta’s FAN is unlikely to systematically reprioritize such traffic without changes at the mediation layer that expose competitive bid data.
The podcast outlines Shopify’s Spring Edition as a comprehensive marketing operating system that expands the company’s advertising platform into an AI‑driven, cross‑channel solution. By integrating Shop Campaigns with OpenAI, Pinterest, and Microsoft Monetize, Shopify enables merchants to launch campaigns across paid and organic channels from a single dashboard. The new “Campaign Autopilot” tool recommends budgets, optimizes spend for return on ad spend (ROAS) targets, and streamlines attribution, lowering the barrier to entry for small businesses that can now confidently spend their first dollar on advertising.
Central to the strategy is a unified platform that aligns incentives with merchant gross merchandise volume (GMV). Shopify’s deep transaction data allows it to remove measurement uncertainty, unlock additional spend on under‑utilized surfaces such as the open web and ChatGPT, and offer risk‑free advertising while still tracking conversions through Shop Campaigns events. The system promises higher incremental GMV for smaller direct‑to‑consumer brands, though more sophisticated attribution and incrementality tools remain in development.
Leveraging its extensive merchant network, Shopify enhances audience targeting through pooled purchase and behavioral data. This improves match rates on platforms like Meta, powers predictive machine learning models for high‑propensity customers, and feeds richer value signals back to ad networks. The integrated signal engineering capabilities position Shopify as a valuable partner for advertisers who lack the resources to build comparable insights independently, thereby driving both GMV and incremental ad spend across the ecosystem.
The article examines the emerging price competition among enterprise AI providers, focusing on OpenAI’s potential strategy to undercut competitors such as Anthropic. It reports that OpenAI is contemplating significant reductions in token pricing for its enterprise API, a move aimed at attracting business customers and gaining market share. The piece highlights how token usage remains the standard billing unit across AI firms, making price adjustments a direct lever for influencing adoption rates.
Key findings indicate that OpenAI’s consumer-facing products already enjoy strong pricing advantages, with lower costs and higher accessibility compared to enterprise offerings. This consumer advantage is expected to translate into a competitive edge if the company successfully aligns its enterprise pricing with or below that of rivals. The article suggests that such a price war could reshape the AI services landscape, potentially driving consolidation or forcing new entrants to differentiate beyond cost.
The scope covers global enterprise AI markets with a focus on North American and European segments, reflecting the concentration of major players in these regions. The time frame discussed is current as of mid‑2026, with references to recent Wall Street Journal reporting. While the article does not detail a formal methodology, it relies on industry news sources and market observations to support its analysis. Overall, the piece argues that OpenAI’s aggressive pricing strategy could accelerate adoption of AI services in enterprise contexts while reinforcing its consumer dominance.
Fox announced a $22 billion cash‑and‑stock deal to acquire Roku, the operator of one of the world’s largest connected‑TV advertising ecosystems. The transaction is positioned to merge Fox’s flagship sports, news and entertainment properties—including the Tubi streaming service—with Roku’s platform that powers millions of households’ ad‑supported viewing experiences. The deal is framed as a strategic move to deepen Fox’s reach in the rapidly expanding over‑the‑top (OTT) market, leveraging Roku’s robust ad inventory and data capabilities to enhance monetization of Fox content.
Key figures highlight that Roku currently serves over 100 million active users worldwide, with an average of 1.5 hours of ad‑supported viewing per user each month. Fox’s acquisition is expected to unlock an additional $1 billion in annual advertising revenue, based on Roku’s current CPM rates of $12–$15 for premium inventory. The combined entity will also benefit from cross‑platform synergies, such as unified content distribution and shared user data for targeted advertising.
The scope of the deal covers global markets, with a particular emphasis on North America and Europe where OTT penetration exceeds 70 %. The transaction is slated to close in Q4 2026, pending regulatory approval. Fox’s leadership cites the need for scale to compete against Amazon and other tech giants, noting that Amazon’s earlier attempts to acquire a streaming platform were stymied by antitrust concerns and strategic misalignment. The acquisition is expected to position Fox as a leading player in the converging media‑tech landscape, combining content creation with advanced ad delivery infrastructure.
Meta announced on June 12, 2026 that it will incorporate advertiser‑provided data into its content recommendation algorithms. The company stated that it already uses similar data—such as games played or purchases made—to personalize user experiences, and the update will extend this practice to a broader range of advertiser insights. The move is positioned as an enhancement to the platform’s existing recommendation engine, aiming to deliver more relevant content by leveraging commercial data that advertisers already share with Meta.
The announcement highlights the potential for tighter integration between advertising and content discovery, suggesting that advertisers’ behavioral data can improve relevance scores for posts, stories, and other media. Meta’s blog notes that the change will not alter privacy settings but will refine how third‑party data is weighted in recommendation models. No specific metrics or pilot results are disclosed, and the update appears to be a platform‑wide rollout rather than a limited test.
Geographically, the initiative applies globally across Meta’s social media services, including Facebook, Instagram, and WhatsApp. The time frame for full deployment is not specified beyond the announcement date. Methodologically, Meta relies on existing data pipelines that ingest advertiser‑supplied signals; the company does not detail sample sizes or statistical validation procedures in the public statement.
Overall, Meta’s strategy reflects a broader industry trend of blending advertising data with content curation to enhance user engagement and monetization, while maintaining a focus on privacy compliance.
Apple’s WWDC 2026 centered on the deepening integration of artificial intelligence across its ecosystem, with a particular emphasis on generative models and enhanced developer tooling. The keynote revealed that the new iOS 18 SDK will expose a suite of AI‑powered APIs—text generation, image synthesis, and real‑time language translation—that developers can embed without extensive machine learning expertise. Apple also announced a new “App Intelligence” dashboard, providing granular analytics on AI‑driven user interactions and monetization pathways.
Key findings indicate that 78 % of surveyed developers expect to adopt at least one AI API within the next year, driven by projected 15 % lift in user engagement and a 12 % increase in average revenue per user (ARPU) for AI‑enabled apps. The conference highlighted case studies where AI features boosted retention by 18 % and reduced churn by 9 %. Apple’s updated App Store guidelines now require transparency around AI usage, mandating disclosure of model training data and bias mitigation strategies.
The scope covers the global mobile app market, with a focus on iOS users in North America and Europe. Data sources include Apple’s internal analytics, a 3,200‑developer survey conducted in Q2 2026, and third‑party market reports. Methodology involved cross‑referencing usage metrics with revenue outcomes to isolate AI impact.
Conclusions underscore that AI integration is poised to become a core differentiator for app success, compelling developers to prioritize ethical transparency and robust data governance while leveraging Apple’s expanding AI ecosystem.
The analysis demonstrates that artificial intelligence is rapidly transforming journalism from a peripheral support function to an integral component of the newsroom workflow. Economic pressures and advances in large language models, such as GPT‑4.5, have driven many smaller publishers and international media groups to adopt AI‑driven content pipelines for research, fact‑checking, and even full article drafting. While legacy outlets remain cautious due to workflow inertia and trust concerns, the trend toward routine AI use is clear across a broad geographic spectrum that includes European, Nordic, and global media houses.
Key findings emphasize that technical capability is no longer the limiting factor; instead, ethical use and accountability shape the industry’s trajectory. Trust hinges on auditable policies that provide clear traceability of AI tools, human oversight, and compliance with regulatory frameworks like the EU Transparency Act. Responsible deployment can enhance verification standards but must guard against homogenizing editorial voice and spreading misinformation through unverified content.
The most significant value of AI lies in high‑volume information processing—classifying, ranking, summarizing, and fact‑checking thousands of sources in minutes. Platforms such as Velora illustrate how automation can handle repetitive tasks (CMS field population, SEO tagging, social media asset creation) while preserving editorial control through iterative drafting and human review. This frees journalists to concentrate on investigative and original reporting, provided that source curation remains user‑defined and continuous feedback loops are maintained.
Overall, the evidence points to a future where AI is not merely an adjunct but a core production tool, contingent on robust governance and ethical frameworks that balance efficiency with journalistic integrity.