GREE
Game Co.192 documents
Documents
Financial4 pages
FY2020 Fourth Quarter Financial Results Briefing
GREE, Inc. reported its financial results for the fiscal year ending June 2020, highlighting a period of strategic restructuring and global expansion. Full-year net sales reached ¥62.7 billion with an operating income of ¥3.2 billion. While the fourth quarter saw a slight operating loss of ¥0.07 billion, this was primarily attributed to ¥0.83 billion in one-time restructuring costs, including office consolidations and employee work-from-home benefits. Adjusted for these factors, the profit generation base remained stable at approximately ¥0.8 billion for the quarter.
The company’s operations are centered on three pillars: games, live entertainment, and advertising and media. The game business remains the primary driver, focusing on long-term title management and global distribution. Significant growth was noted in overseas sales, supported by the expansion of titles like Another Eden and the successful July 2020 launch of SINoALICE in 139 countries. Future growth is anticipated through a robust pipeline of new titles and a strategic push into the Chinese market via partnerships with local distributors such as bilibili.
The live entertainment segment continues to invest in the REALITY platform, focusing on both consumer functionality and B2B support for virtual events. Meanwhile, the advertising and media business faced headwinds due to COVID-19, leading to a focus on making the segment leaner and more vertically integrated.
Looking toward FY2021, the strategy emphasizes aggressive investment across all three pillars. Management expects the media business to return to profitability through restructuring, while the game segment is projected to see an immediate boost in operating income to over ¥1 billion in the first quarter. Shareholder returns remain a priority, evidenced by a ¥2.5 billion stock repurchase program and a commitment to a 20% consolidated dividend payout ratio.
- GREE reported FY2020 net sales of ¥62.7 billion and an operating income of ¥3.2 billion, with a stable underlying quarterly profit base of ¥0.8 billion after adjusting for one-time restructuring costs.
- The game segment is the primary revenue driver, with growth fueled by the international performance of 'Another Eden' and the July 2020 global launch of 'SINoALICE' across 139 countries.
- Management projects a significant rebound in the game segment for Q1 FY2021, forecasting operating income to exceed ¥1 billion.
- Future growth strategy includes expanding into the Chinese market through distribution partnerships with companies such as bilibili.
- The company is prioritizing shareholder returns through a ¥2.5 billion stock repurchase program and a commitment to a 20% consolidated dividend payout ratio.
GREE Inc.Jan 2020
Financial28 pages
FY2020 First Quarter Financial Results
GREE’s financial results for the first quarter of fiscal year 2020 reflect a period of steady profitability driven by strategic cost management and the global expansion of its gaming portfolio. During this period, the company reported net sales of ¥15.8 billion and an operating income of ¥1.2 billion. While net sales saw a reactive decline following previous anniversary events, operating income surpassed internal forecasts. This stability was supported by a significant reduction in total costs, which fell by ¥1.5 billion quarter-on-quarter to ¥14.6 billion, primarily through lower advertising expenses and reduced outsourcing.
The gaming segment remains the primary revenue driver, characterized by the stable operation of existing titles such as Another Eden and SINoALICE through major storyline updates and IP collaborations. A key growth milestone was the October launch of DanMachi in 27 European countries and territories. The company is maintaining a robust development pipeline with two major third-party IP titles scheduled for release later in the fiscal year. Beyond gaming, GREE is diversifying through its Live Entertainment business, specifically expanding original programming for the REALITY virtual live distribution platform, and strengthening its advertising and media reach via platforms like LIMIA and aumo.
Geographically, the company is focused on transitioning from a domestic-centric model to a global operator, with active distribution agreements in North America, Europe, and Mainland China. Financial health remains strong, with cash and cash equivalents totaling ¥84.9 billion and a total net asset value of ¥111.8 billion. The workforce remained relatively stable at 1,729 employees. Moving forward, the strategic thesis emphasizes leveraging game engines and global IP to ensure firm profit margins across international markets.
- GREE reported Q1 FY2020 net sales of ¥15.8 billion and an operating income of ¥1.2 billion, the latter of which exceeded internal forecasts.
- Total costs were reduced by ¥1.5 billion quarter-on-quarter to ¥14.6 billion, primarily driven by lower advertising spend and decreased outsourcing.
- The gaming segment remains the primary revenue driver, supported by stable performance from titles like Another Eden and SINoALICE and the October launch of DanMachi in 27 European territories.
- The company maintains a strong financial position with ¥84.9 billion in cash and cash equivalents and a total net asset value of ¥111.8 billion.
- GREE is diversifying its revenue streams through the REALITY virtual live distribution platform and advertising/media platforms LIMIA and aumo.
+1
GREEOct 2019

Financial2 pages
Summary of Main Supplementary Explanations Questions and Answers at the FY2020 First Quarter GREE Results Briefing
GREE’s financial performance for the first quarter of fiscal year 2020 reflects a transitional period characterized by strategic portfolio adjustments and a shift toward global distribution. The quarter experienced a sequential decline in sales, primarily attributed to a reactive drop following major anniversary events in the previous quarter and the strategic transfer of specific titles intended to streamline the game operation business. Despite these headwinds, the outlook for the second quarter remains cautiously optimistic, with projected operating income of approximately 0.5 billion yen. While browser game revenue continues to trend downward, mainstay titles are expected to perform strongly, supported by increased advertising investment in high-potential assets.
The strategic focus has shifted toward improving profitability through cost-cutting measures and the expansion of the title lineup. This includes a robust commitment to international markets, supported by a newly developed system capable of simultaneous global releases. However, the timing for specific overseas launches, such as the distribution of SINoALICE, remains contingent on local partnerships and regulatory approvals, particularly in China. Challenges persist in media-mix strategies, as evidenced by the underperformance of AFTERLOST - Shoumetsu Toshi, which failed to meet expectations in attracting new users while maintaining the existing fan base.
Future growth is increasingly tied to the development of the REALITY platform and the advancement of 5G technology. Rather than pursuing aggressive immediate growth, the current strategy emphasizes the steady expansion of the content portfolio and the enhancement of platform functionality to prepare for a more robust infrastructural environment. This long-term approach aims to increase product lifetime value while navigating the evolving landscape of mobile gaming and virtual platforms. Overall, the findings indicate a focus on operational efficiency and global readiness as the primary drivers for upcoming fiscal periods.
- GREE projects an operating income of approximately 0.5 billion yen for the second quarter of fiscal year 2020.
- Q1 sales experienced a sequential decline due to a post-anniversary revenue drop and the strategic transfer of specific game titles.
- The company is prioritizing long-term growth through the development of the REALITY platform and preparations for 5G infrastructure, rather than pursuing immediate aggressive expansion.
- International market strategy is centered on a new system for simultaneous global releases, though the launch of SINoALICE remains delayed by regulatory approvals and partnership requirements in China.
- Browser game revenue is in a sustained downward trend, forcing a strategic shift toward increased advertising investment in high-potential mainstay titles.
+2
GREEOct 2019
Financial4 pages
FY2019 3Q Presentation
The third quarter of fiscal year 2019 for this Japanese mobile gaming and live entertainment firm was characterized by a strategic shift toward overseas distribution and the restructuring of unprofitable business segments. Financial results for the period included net sales of ¥17.6 billion and an operating income of ¥1.6 billion, which exceeded internal forecasts. While a one-off event impacted these figures, the underlying organic performance remained stable as the company successfully reduced fixed costs and improved operational efficiency across its existing game portfolio.
A primary driver of growth during this period was the international expansion of first-party and licensed intellectual properties. The global launch of Another Eden marked a significant milestone as the company’s first self-distributed title in eight overseas regions, with international performance reaching a scale comparable to domestic operations. Additionally, global collaboration events for titles such as DanMachi and SINoALICE proved highly effective, with the former seeing a 1.5-fold increase in daily active users following a cross-media partnership. While the browser game segment continued a gradual decline, the growth in native mobile games and overseas revenue successfully offset these losses.
Looking ahead to the fourth quarter, the company projected net sales between ¥17 billion and ¥18 billion. Growth is expected to be fueled by anniversary events for mainstay titles and the launch of AFTERLOST, the latest entry in the Shoumetsu Toshi series. Beyond gaming, the company is investing in its live entertainment business through the VTuber viewing app REALITY, focusing on expanding original program lineups. The overall strategy emphasizes strengthening three core earnings pillars while utilizing successful new product launches as potential upside for future fiscal years.
- The firm reported FY2019 3Q net sales of ¥17.6 billion and an operating income of ¥1.6 billion, both exceeding internal forecasts due to fixed cost reductions and operational efficiencies.
- International expansion served as a primary growth driver, highlighted by the global self-distribution of 'Another Eden' across eight regions, which achieved performance levels comparable to domestic operations.
- Cross-media collaboration events proved effective for user acquisition, notably driving a 1.5-fold increase in daily active users for the 'DanMachi' title.
- Growth in native mobile games and international revenue successfully offset the ongoing, gradual decline of the company’s browser game segment.
- The company projects FY2019 4Q net sales to remain steady between ¥17 billion and ¥18 billion, supported by anniversary events and the launch of 'AFTERLOST'.
+2
GREESept 2019
Financial39 pages
FY2019 Fourth Quarter Financial Results
Fiscal year 2019 concluded with net sales of ¥70.9 billion and operating income of ¥5.5 billion, driven primarily by the successful transition to a long-term operating system and the aggressive expansion of overseas distribution. Performance remained steady through the fourth quarter, yielding ¥17.4 billion in net sales as global partnerships and self-distribution efforts bolstered titles such as Another Eden and DanMachi. While domestic coin consumption experienced a slight year-over-year decline to 10.9 billion, the core games business maintained stability through large-scale anniversary events and strategic multi-platform expansions onto the Nintendo Switch and Facebook Instant Games.
The strategic framework for future growth rests on three pillars: stabilizing the games division as a financial foundation, scaling advertising and media through vertical portfolios, and investing heavily in the REALITY VTuber platform. Global reach has become a central priority, evidenced by Another Eden’s expansion into 34 regions and SINoALICE securing over one million pre-registrations across 150 countries. These international efforts are complemented by a focus on the Chinese market and the development of two major third-party IP titles scheduled for release in the coming fiscal year.
Financial health remains robust, characterized by a strong cash position of ¥84.5 billion and a successful reduction in total costs to ¥16.07 billion. Although total net assets saw a minor contraction, the overall trajectory emphasizes a shift toward high-growth emerging sectors like virtual live streaming and community-driven media. By leveraging strategic alliances and community engagement, the objective is to offset fluctuations in traditional mobile gaming consumption with diversified revenue streams across the global digital entertainment landscape.
- The company concluded FY2019 with ¥70.9 billion in net sales and ¥5.5 billion in operating income, supported by a cash position of ¥84.5 billion.
- Q4 performance reached ¥17.4 billion in net sales, driven by global partnerships and self-distribution efforts for titles including Another Eden and DanMachi.
- The company is pivoting toward high-growth sectors, specifically prioritizing the REALITY VTuber platform and the expansion of advertising and media portfolios.
- International growth is a core strategy, highlighted by the expansion of Another Eden into 34 regions and over one million pre-registrations for SINoALICE across 150 countries.
- Domestic coin consumption saw a year-over-year decline to 10.9 billion, prompting a strategic shift toward multi-platform releases on Nintendo Switch and Facebook Instant Games.
GREEAug 2019
Financial1 pages
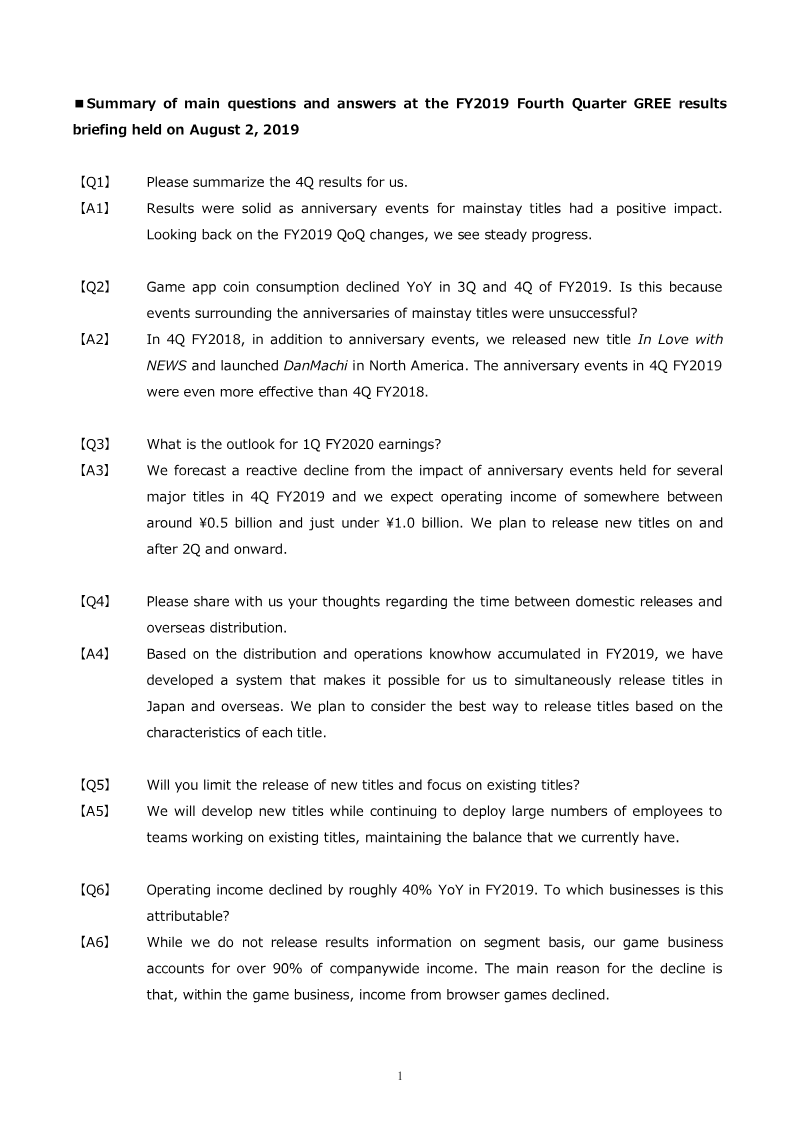
Summary of Main Questions and Answers at the FY2019 Fourth Quarter GREE Results Briefing
The fiscal year 2019 fourth quarter results for GREE indicate a period of solid performance driven primarily by successful anniversary events for mainstay titles. While game app coin consumption showed a year-over-year decline in the second half of the fiscal year, this is attributed to a high baseline in the previous year caused by specific new title launches and international expansions. The fourth quarter of 2019 actually saw more effective anniversary event engagement than the same period in 2018, suggesting that core titles remain resilient despite broader market shifts.
The financial outlook for the first quarter of fiscal year 2020 anticipates a reactive decline in earnings following the surge from recent anniversary events, with operating income projected between 0.5 billion and 1.0 billion yen. New title releases are scheduled to begin in the second quarter and continue thereafter. A significant strategic shift involves the development of a system for simultaneous domestic and international releases, leveraging distribution and operations expertise gained throughout 2019. This approach will be applied selectively based on the specific characteristics of each title.
Regarding the overall corporate structure, the game business remains the dominant driver of performance, accounting for over 90% of companywide income. The 40% year-over-year decline in operating income for fiscal year 2019 is largely attributed to diminishing returns from the browser game segment rather than the mobile app portfolio. To address this, the company intends to maintain a balanced resource allocation, continuing to support existing high-performing titles with large teams while simultaneously investing in the development of new intellectual properties.
- GREE's fiscal year 2019 operating income declined 40% year-over-year, primarily driven by diminishing returns in the browser game segment.
- The game business remains the company's primary revenue driver, accounting for over 90% of total companywide income.
- Operating income for the first quarter of fiscal year 2020 is projected to be between 0.5 billion and 1.0 billion yen, reflecting a reactive decline following Q4 anniversary events.
- GREE is shifting its strategy toward a system for simultaneous domestic and international title releases, utilizing operational expertise gained throughout 2019.
- While game app coin consumption declined in the second half of fiscal year 2019, Q4 anniversary events showed stronger engagement than the same period in 2018.
+2
GREEAug 2019
Financial29 pages
FY 2019 Third Quarter Financial Results
GREE’s financial results for the third quarter of fiscal year 2019 reflect a period of strategic transition, characterized by a shift toward overseas self-distribution and improved operational efficiency. The company reported net sales of ¥17.6 billion and an operating income of ¥1.6 billion, which surpassed internal forecasts. While overall net sales saw a slight year-over-year decline, operating income grew significantly compared to the previous quarter. This profitability was driven by a reduction in fixed costs, specifically through the streamlining of outsourcing and operational expenses, which offset a decline in legacy web-based games.
The geographic scope of the results highlights a successful push into international markets. The self-distribution of first-party intellectual property, notably Another Eden, saw a strong start in eight countries and regions. Additionally, global simultaneous collaboration events for DanMachi contributed to increased daily active users and revenue. The company’s mobile game segment remains the primary revenue driver, accounting for ¥13.65 billion of total sales, while the advertising and media segment contributed ¥3.99 billion.
Looking ahead to the fourth quarter of FY2019, the company forecasts net sales between ¥17.0 billion and ¥18.0 billion. This outlook is supported by a development pipeline of five mobile titles and the planned launch of AFTERLOST in the Shoumetsu Toshi series. Beyond gaming, the company is expanding its live entertainment ecosystem through the REALITY VTuber app and strengthening its media potential via its LIMIA and ARINE platforms. As of March 31, 2019, the company maintains a strong balance sheet with ¥86.3 billion in cash and equivalents and a consolidated headcount of 1,693 employees.
- GREE reported Q3 FY2019 net sales of ¥17.6 billion and an operating income of ¥1.6 billion, with the latter showing significant growth over the previous quarter due to reduced fixed costs.
- Mobile gaming remains the primary revenue driver at ¥13.65 billion, while the advertising and media segment contributed ¥3.99 billion.
- International expansion is a core strategic focus, highlighted by the successful self-distribution of 'Another Eden' in eight regions and strong performance from 'DanMachi' collaboration events.
- The company maintains a robust financial position with ¥86.3 billion in cash and equivalents as of March 31, 2019.
- Management forecasts Q4 FY2019 net sales to range between ¥17.0 billion and ¥18.0 billion, supported by a pipeline of five new mobile titles including 'AFTERLOST'.
GREEApr 2019

Financial1 pages
Summary of Main Questions and Answers at the FY2019 Third Quarter GREE Results Briefing Held on April 26, 2019
The financial performance for the third quarter of fiscal year 2019 reflects a period of stabilization and strategic investment, with operating income exceeding initial forecasts when excluding one-time events. This outperformance was primarily driven by the international success of Another Eden, which saw overseas sales surpass expectations, alongside improved operational cost efficiencies within the game business. While advertising expenses remained consistent with internal projections, the optimization of fixed costs contributed significantly to the bottom line during this period.
Looking toward the fourth quarter, projections indicate a substantial increase in net sales and a positive outlook for operating income. The strategic focus remains on balancing current profitability with aggressive investment in future growth drivers. Management anticipates that the launch of new titles in the upcoming fiscal year will provide significant upside potential. The company maintains a commitment to funding development and promotional activities to ensure long-term sustainability while generating stable profits from its existing portfolio.
In the emerging VTuber and live-streaming sector, the REALITY platform is identified as a core area for expansion. Current business progress is measured through key performance indicators such as installation numbers and user retention rates, both of which are trending positively. Although this segment requires ongoing upfront investment, the favorable trajectory of these metrics justifies continued financial backing. The overarching goal is to scale the REALITY business significantly by fostering a service that maintains high user engagement over the long term.
- GREE's Q3 FY2019 operating income exceeded initial forecasts, driven by the international performance of the game 'Another Eden' and improved operational cost efficiencies.
- Management projects a substantial increase in net sales and positive operating income for the fourth quarter of fiscal year 2019.
- The company is prioritizing aggressive investment in future growth drivers while maintaining profitability through its existing game portfolio.
- The 'REALITY' platform, focused on the VTuber and live-streaming sector, is a core expansion area with positive trends in installation numbers and user retention rates.
- GREE plans to launch new titles in the upcoming fiscal year to generate significant upside potential for the company.
GREEApr 2019
Financial4 pages
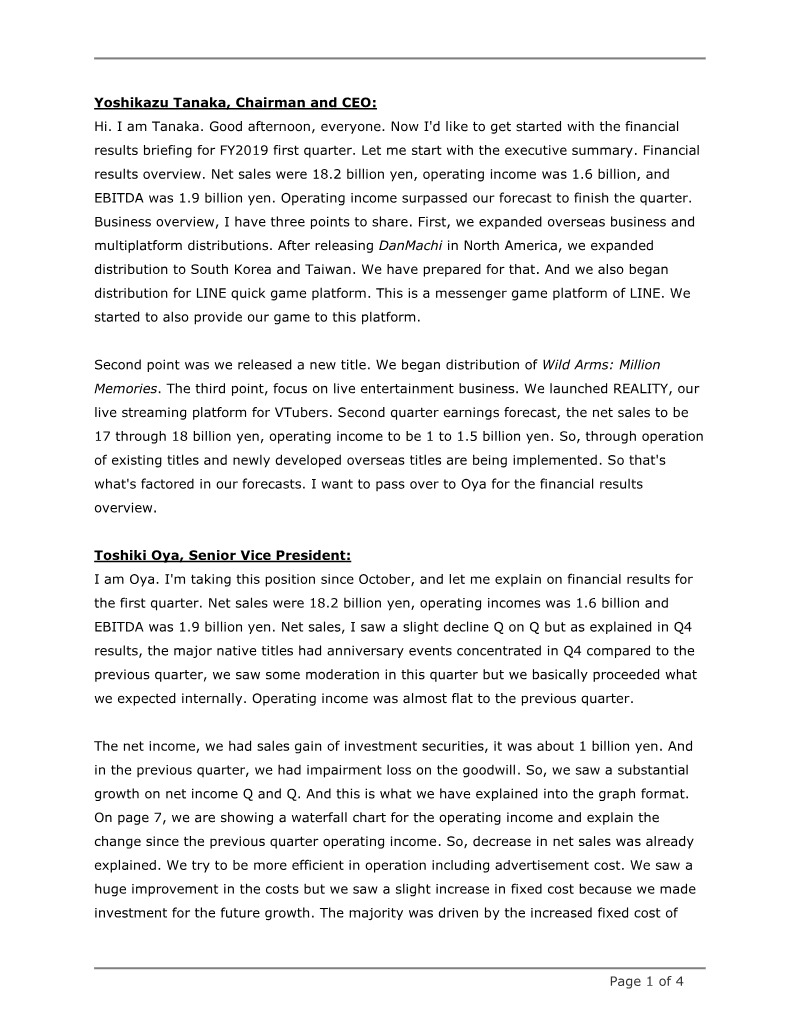
Financial Results Briefing for FY2019 First Quarter Transcript
This financial briefing outlines the performance and strategic direction of GREE, Inc. for the first quarter of fiscal year 2019. The company reported net sales of 18.2 billion yen and an operating income of 1.6 billion yen, which exceeded internal forecasts despite a slight quarter-on-quarter decline in sales. This decline was attributed to a high baseline in the previous quarter driven by major title anniversaries. Net income saw substantial growth due to the sale of investment securities and the absence of previous impairment losses.
The strategic focus centers on three pillars: game business expansion, live entertainment, and advertising media. In the gaming sector, the company is prioritizing global distribution and multi-platform reach. Key activities include the North American, South Korean, and Taiwanese launches of DanMachi via self-distribution, which aims to improve profit margins compared to partner-led models. The company also released Wild Arms: Million Memories and expanded into messenger-based gaming via the LINE Quick Game platform. Future growth is supported by a pipeline of four titles in development and a push into the Nintendo Switch market.
The live entertainment segment highlights the full launch of REALITY, a dedicated live-streaming platform for VTubers. This ecosystem is being bolstered by the VTuber Fund and strategic partnerships with King Records and Idea Factory to develop music projects and live events. In the advertising and media segment, the company is focusing on strengthening the community potential of its LIMIA and MINE platforms. Looking ahead to the second quarter, the company issued a range-based forecast of 1 to 1.5 billion yen in operating income to account for the inherent volatility of new overseas self-distribution efforts and fluctuating user transactions in existing titles like Another Eden.
- GREE reported Q1 FY2019 net sales of 18.2 billion yen and an operating income of 1.6 billion yen, exceeding internal forecasts despite a quarter-on-quarter sales decline caused by the absence of previous major title anniversaries.
- Net income grew significantly compared to the previous period, driven by the sale of investment securities and the lack of recurring impairment losses.
- The company is shifting its gaming strategy toward self-distribution in North America, South Korea, and Taiwan for titles like DanMachi to improve profit margins compared to partner-led models.
- GREE is diversifying its gaming portfolio by expanding into the Nintendo Switch market and developing four new titles, alongside its existing push into messenger-based gaming via the LINE Quick Game platform.
- The live entertainment segment is centered on the full launch of the VTuber platform REALITY, supported by the VTuber Fund and strategic partnerships with King Records and Idea Factory.
+2
GREE Inc.Mar 2019
Financial2 pages
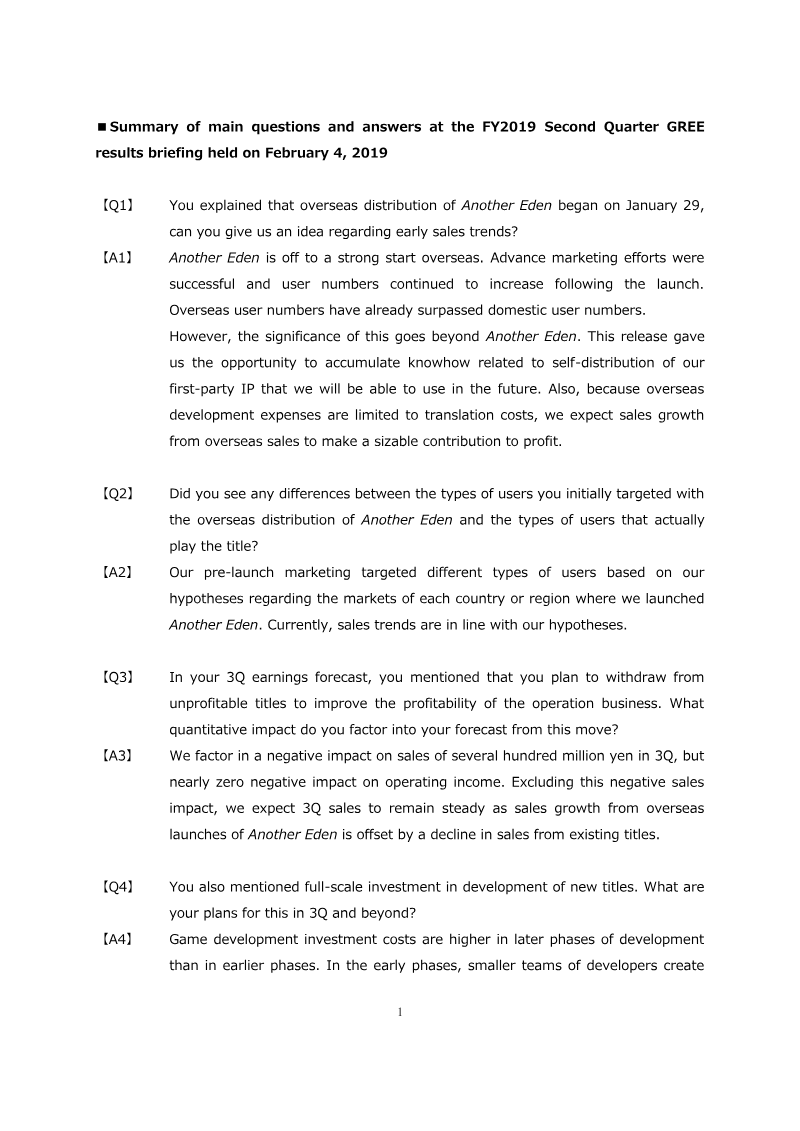
Summary of Main Questions and Answers at the FY2019 Second Quarter GREE Results Briefing Held on February 4, 2019
The financial performance and strategic direction for the second quarter of fiscal year 2019 center on the successful international expansion of first-party intellectual property and a rigorous optimization of the existing game portfolio. A primary driver of recent growth is the overseas launch of Another Eden, which has seen rapid adoption, with international user counts already surpassing domestic Japanese figures. Because international expansion costs are largely limited to translation and localized marketing, these global revenues are expected to contribute significantly to profit margins. This expansion serves as a foundational case study for the company, providing essential data on self-distribution and cross-border marketing hypotheses that will inform future global releases.
Operational efficiency is being addressed through the planned withdrawal from several unprofitable titles. While this strategic contraction is expected to reduce third-quarter sales by several hundred million yen, the impact on operating income is projected to be negligible, effectively streamlining the business for better long-term profitability. Overall sales for the upcoming quarter are expected to remain steady, as the growth from new international markets offsets the natural lifecycle decline of older domestic titles.
Future growth is being supported by a robust development pipeline, with multiple titles currently in the late stages of production. This transition into high-volume content creation necessitates an increase in outsourcing costs and development investment. Marketing expenditures for the third quarter are projected to remain stable within the Japanese market, though several hundred million yen has been allocated specifically for overseas advertising to sustain the momentum of recent launches. Additionally, a one-time correction of variable cost transactions related to the misclassification of domestic and overseas expenses was completed in the second quarter, with no further impact expected on future financial reporting.
- The international launch of 'Another Eden' has become a primary growth driver, with overseas user counts now exceeding domestic Japanese figures.
- Global expansion is highly profitable because costs are primarily limited to translation and localized marketing, providing a scalable model for future self-distributed releases.
- The company is streamlining its portfolio by withdrawing from unprofitable titles, which will reduce third-quarter sales by several hundred million yen but have a negligible impact on operating income.
- Overall sales are projected to remain steady in the upcoming quarter as international growth offsets the natural lifecycle decline of older domestic titles.
- The company is increasing development investment and outsourcing costs to support a robust pipeline of titles currently in the late stages of production.
+2
GREEFeb 2019
Financial32 pages
FY2019 Second Quarter Financial Results
GREE reported second-quarter net sales of ¥17.7 billion and operating income of ¥1.0 billion for the fiscal year ending June 2019. While these figures represent a year-over-year decline in profitability, they align with internal forecasts and reflect a deliberate period of reinvestment. The company is currently prioritizing long-term growth through increased fixed costs associated with full-scale development for new titles and the expansion of overseas distribution for core intellectual properties such as DanMachi and Another Eden. This strategic shift includes a transition toward self-distribution in international markets and the diversification of the portfolio across multiple platforms, exemplified by the release of Fishing Star on the Nintendo Switch.
The financial landscape is characterized by a robust net cash position of ¥86.9 billion, providing the necessary liquidity to fund the development of the REALITY Avatar livestreaming platform and the growth of the award-winning media app aumo. Despite a projected dip in third-quarter operating income to between ¥0.3 and ¥0.8 billion, the organization is streamlining operations by withdrawing from unprofitable titles and optimizing its workforce. As of December 2018, the group employed 1,701 personnel, with the vast majority concentrated in the Game and Entertainment segment to support its multiplatform and global expansion initiatives.
Ultimately, the current fiscal performance underscores a transition from domestic mobile dominance toward a global, multi-faceted entertainment model. By leveraging first-party IPs and expanding into the VTuber and advertising media sectors, the strategy aims to stabilize future earnings through a broader geographic and platform reach. Although development investments and overseas marketing costs currently weigh on margins, the focus remains on strengthening media potential and establishing a sustainable international presence across Asia and other global markets.
- GREE reported Q2 FY2019 net sales of ¥17.7 billion and operating income of ¥1.0 billion, reflecting a year-over-year decline in profitability due to deliberate reinvestment strategies.
- The company maintains a strong liquidity position with ¥86.9 billion in net cash, which is being deployed to fund the development of the REALITY Avatar platform and the growth of the media app aumo.
- GREE is shifting its business model from domestic mobile dominance toward a global, multi-platform strategy, including self-distribution in international markets and the release of titles like Fishing Star on Nintendo Switch.
- Operating income is projected to decline further in Q3 to between ¥0.3 billion and ¥0.8 billion as the company continues to absorb high development and overseas marketing costs.
- To offset investment costs, the organization is streamlining operations by withdrawing from unprofitable titles and optimizing its workforce, which totaled 1,701 employees as of December 2018.
GREEFeb 2019
Financial6 pages
Financial Results for the Second Quarter of FY2019: Transcript
The financial results for the second quarter of fiscal year 2019 reflect a strategic pivot toward overseas self-distribution and the nurturing of first-party intellectual property. Net sales reached ¥17.7 billion with an operating income of ¥1 billion, figures that largely aligned with internal forecasts. While the operating margin stood at 5.4%, results were slightly impacted by a ¥160 million accounting revision related to prior variable costs. Excluding this adjustment, operating income would have reached ¥1.13 billion. The company maintains a strong financial position, noting that its investment securities, valued at ¥17 billion on the books, have a fair market value estimated at over ¥25 billion.
A primary driver of recent performance is the successful international expansion of titles like DanMachi, which performed stronger than expected in North America and Asian markets. This success serves as a blueprint for the global launch of first-party IP, specifically Another Eden and Shoumestu Toshi. Management emphasizes that while self-distribution requires significant upfront marketing investment to build user communities from scratch, the long-term profitability is higher because development costs for localized versions are minimized. To streamline operations, the subsidiary funplex is withdrawing from unprofitable titles to improve the overall portfolio health.
Beyond mobile gaming, the strategy includes multi-platform expansion and diversification into live entertainment and media. The launch of Fishing Star on Nintendo Switch demonstrates a commitment to cross-platform IP utilization, while the REALITY Avatar app marks an entry into the VTuber livestreaming market. The development pipeline remains active with five titles currently under development, including a new first-party IP scheduled for release by the end of the fiscal year. Looking ahead to the third quarter, the company forecasts net sales between ¥16.5 and ¥17.5 billion, factoring in continued investment in new titles and global marketing initiatives.
- The company reported Q2 FY2019 net sales of ¥17.7 billion and an operating income of ¥1 billion, aligning with internal forecasts despite a ¥160 million accounting revision.
- Strategic focus has shifted toward overseas self-distribution to improve long-term profitability, leveraging the successful international performance of titles like DanMachi as a blueprint for Another Eden and Shoumestu Toshi.
- The company holds a strong financial position with investment securities valued at ¥17 billion on the books, which carry an estimated fair market value exceeding ¥25 billion.
- Subsidiary funplex is currently optimizing its portfolio by withdrawing from unprofitable titles to improve overall operational health.
- Diversification efforts include cross-platform expansion, such as the release of Fishing Star on Nintendo Switch, and entry into the VTuber livestreaming market via the REALITY Avatar app.
+1
GREEJan 2019