GamesIndustry.biz
Media21 documents
Documents
Article
Why Xbox Took Call of Duty out of Game Pass
Microsoft’s decision to remove Call of Duty from day-one Game Pass availability stems from data indicating that the franchise failed to drive subscription growth while simultaneously cannibalizing premium game sales. Analysis of market intelligence from Newzoo reveals that while the inclusion of Black Ops 6 in the service generated a temporary 71% surge in monthly active users on Xbox, this engagement did not translate into sustained revenue growth. Conversely, the platform observed flat-to-negative revenue performance during the same period, suggesting that subscription access directly substituted for individual unit purchases.
The scope of this analysis covers the United States, United Kingdom, Italy, France, Germany, and Spain, tracking revenue and player engagement across the Call of Duty HQ ecosystem from late 2023 through early 2026. Data shows that the subsequent release, Black Ops 7, failed to replicate the engagement gains of its predecessor, with Xbox monthly active users falling 52% from the Black Ops 6 peak. This reversion to previous engagement levels, coupled with a sharp decline in overall franchise revenue, prompted Microsoft to adjust its strategy.
In response to these findings, Microsoft has opted to delay the inclusion of new Call of Duty titles in Game Pass by approximately one year and has implemented a reduction in subscription pricing. This strategic pivot aims to protect premium sales revenue and improve the financial health of the brand. While the franchise maintains a significant player base, the data confirms that the majority of revenue and engagement remains concentrated on the PlayStation platform, reinforcing the necessity for a more traditional sales model to bolster the Xbox bottom line.
- Microsoft shifted Call of Duty to a delayed Game Pass release model after data showed day-one availability cannibalized premium unit sales without driving sustained subscription revenue growth.
- While Black Ops 6 generated a 71% surge in Xbox monthly active users, the platform experienced flat-to-negative revenue performance during the same period.
- The release of Black Ops 7 saw monthly active users on Xbox drop 52% from the Black Ops 6 peak, indicating that engagement gains from subscription access were not sustainable.
- Microsoft is now delaying the inclusion of new Call of Duty titles in Game Pass by approximately one year to protect premium sales and improve brand financial health.
- Market analysis across the US and major European markets from 2023 to 2026 confirms that the majority of Call of Duty revenue and engagement remains concentrated on the PlayStation platform.
+1
GamesIndustry.bizApr 2026
Article
The Year in Numbers 2025: Year in Review
The Year in Numbers 2025 serves as a comprehensive annual summary of the global video game industry, consolidating key performance metrics and market trends from the 2025 calendar year. The primary objective is to provide a high-level overview of the industry’s health through a synthesis of financial data, consumer behavior, and media engagement statistics. By aggregating information from specialized industry partners, the summary offers a multi-faceted view of the gaming landscape, covering major regional markets and various industry segments.
The analysis incorporates data from several prominent industry sources to ensure a broad scope. Global market valuation is provided by Newzoo, while regional sales performance is tracked through Nielsen GfK for the UK, Circana for the US, and Famitsu for Japan. Mobile sector insights, including revenue and download rankings, are sourced from Sensor Tower. Furthermore, the report measures media and social influence using data from ICO’s Footprints—which tracks coverage across over 18,000 websites—and Fancensus, which monitors influencer activity, trailer engagement, and TikTok trends.
Key findings focus on the intersection of commercial success and digital visibility. The data highlights the most influential companies and titles of the year, alongside shifts in consumer engagement across platforms. By combining these diverse data streams, the summary provides a snapshot of the industry’s current trajectory, reflecting both the economic realities of the global market and the evolving patterns of audience interaction with gaming content. This annual review functions as a benchmark for stakeholders to assess the year's commercial outcomes and cultural impact within the interactive entertainment sector.
- The 2025 global video game industry performance was evaluated through a synthesis of financial data, consumer behavior, and media engagement metrics across major regional markets.
- Global market valuation data was provided by Newzoo, with regional sales performance tracked by Circana for the US, Nielsen GfK for the UK, and Famitsu for Japan.
- Mobile sector performance, including revenue and download rankings, was sourced from Sensor Tower data.
- Media and social influence analysis utilized ICO’s Footprints, which tracked coverage across more than 18,000 websites.
- Influencer activity, trailer engagement, and TikTok trends were monitored through Fancensus to measure the digital visibility of industry titles and companies.
GamesIndustry.bizDec 2025
Article
Over 26% of European Game Professionals Were Laid Off in the Past Year: A Employment Analysis
The Big Games Industry Employment Survey, conducted between March and June 2025, provides a comprehensive analysis of the labor market within the European gaming sector. With 1,650 respondents across 85 countries, the research highlights a period of significant instability, revealing that over 26% of industry professionals experienced layoffs during the 2024–2025 period. The findings indicate that creative roles, including game designers, artists, and QA specialists, were the most heavily impacted, while those in management and analytics reported higher levels of job security.
The data underscores a challenging environment for job seekers, as 10.4% of those laid off remain unemployed, and many professionals report that finding new roles now takes significantly longer. This instability has led to a 13% industry exit rate, with junior-level staff particularly affected, as 39% of that demographic left the field within the past year. Furthermore, salary has emerged as the primary motivator for job seekers, replacing previous priorities like project excitement or professional growth. This shift is compounded by reports of stagnant wages and, in some technical roles, a decline in compensation due to a scarcity of open positions.
Beyond employment metrics, the survey identifies persistent structural issues, including a gender pay gap and a notable decline in diversity and inclusion initiatives, with 67% more companies lacking dedicated D&I specialists compared to 2023. Conversely, the adoption of artificial intelligence has doubled, with a majority of developers now viewing the technology as a practical tool rather than a threat. Ultimately, the industry is characterized by widespread fatigue, diminished employee engagement, and a growing sense of insecurity driven by perceived lack of transparency from leadership.
- Over 26% of European game industry professionals were laid off between 2024 and 2025, with creative roles like designers, artists, and QA specialists facing the highest impact.
- Junior-level staff have been disproportionately affected, resulting in a 39% exit rate from the industry within the past year.
- The industry faces a 13% overall exit rate, and 10.4% of those laid off remain unemployed as the time required to secure new roles continues to increase.
- Salary has replaced project interest and professional growth as the primary motivator for job seekers, driven by stagnant wages and compensation declines in certain technical roles.
- Diversity and inclusion initiatives are in decline, with 67% fewer companies employing dedicated D&I specialists compared to 2023.
+1
GamesIndustry.bizOct 2025
Article
Nintendo to Discontinue Switch Game Voucher Service
Nintendo is officially discontinuing its Switch Game Voucher service, a long-standing perk available to Nintendo Switch Online subscribers. The program, which allowed members to purchase pairs of vouchers at a discounted rate to redeem for eligible eShop titles, will cease operations on January 30, 2026. After this date, users will no longer be able to purchase new vouchers.
While the company has not provided a specific reason for the service's termination, it has confirmed that the existing expiration policy remains in effect. All vouchers purchased on or before the final cutoff date will remain valid for 12 months from the date of purchase, meaning the program will be fully phased out by January 30, 2027. Despite the discontinuation of the purchase service, Nintendo intends to continue adding new titles to the eligible Game Voucher catalogue throughout the remainder of 2026.
The decision arrives amidst broader industry discussions regarding Nintendo’s future hardware strategy and pricing models. Although the vouchers were never applicable to upcoming Switch 2 software, the move marks a significant shift in the digital storefront incentives currently offered to the Nintendo Switch user base. The company continues to manage the transition of its digital ecosystem as it navigates ongoing market concerns regarding hardware pricing and supply chain dynamics.
- Nintendo will discontinue its Switch Game Voucher service for Nintendo Switch Online subscribers on January 30, 2026.
- Vouchers purchased on or before the January 30, 2026 cutoff date will remain valid for 12 months, resulting in the program's total phase-out by January 30, 2027.
- Nintendo will continue to add new titles to the eligible Game Voucher catalogue throughout the remainder of 2026 despite the cessation of new voucher sales.
- The Game Voucher program, which allowed members to buy pairs of vouchers at a discount for eligible eShop titles, will no longer be available for new purchases after the January 2026 deadline.
- This policy change marks a shift in Nintendo's digital storefront incentives as the company navigates its broader hardware strategy and ecosystem transition.
+1
GamesIndustry.bizJul 2025
Article
Black Friday Video Game Sales Dip in the UK: UK Monthly Charts 2024
The UK video game market experienced a significant contraction in November 2024, with total software sales reaching just over three million units, representing a 33% decline compared to the same period in 2023. This downturn is primarily attributed to two structural factors: the absence of a major blockbuster release comparable to the previous year’s Call of Duty launch and the exclusion of Black Friday sales from the November data window. During the specific week of Black Friday, sales reached 1.53 million units, an 8% decrease year-over-year.
Hardware and accessory segments also faced downward pressure, with console sales dropping 45% compared to November 2023, despite an 85% increase over October 2024. While the launch of the PlayStation 5 Pro accounted for 26% of all PS5 units sold during the month, the overall hardware decline reflects the shift in the Black Friday promotional calendar. Accessory sales followed a similar trend, falling 18% year-over-year to 1.05 million units.
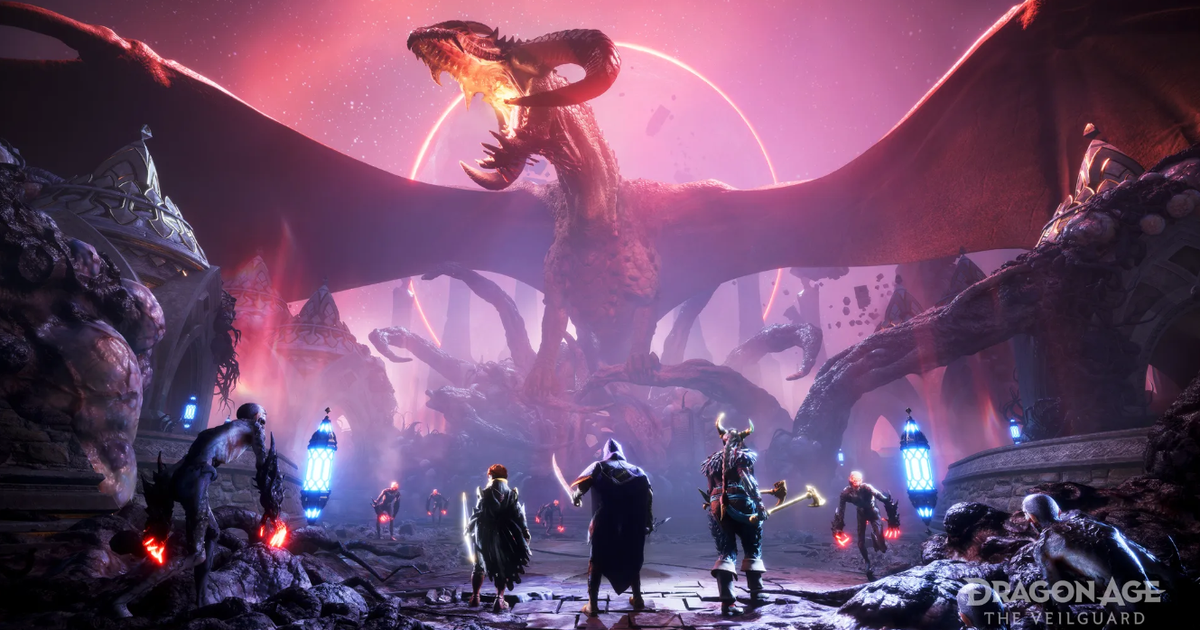
Market performance for new software releases was mixed. Dragon Age: The Veilguard debuted as the highest-charting new title at number three, though its initial sales trajectory has been slower than several other major releases from earlier in the year. Similarly, Mario & Luigi: Brothership underperformed relative to recent Mario RPG titles, with physical sales trailing both Paper Mario: The Thousand Year Door and Super Mario RPG. Call of Duty: Black Ops 6 maintained the top position in the monthly charts, followed by EA Sports FC 25, which saw a 22% decline in November sales compared to the prior year. Data for these findings was sourced from GSD and GfK, covering both physical and digital sales where available.
- UK video game software sales dropped 33% year-over-year in November 2024 to just over three million units, driven by the absence of a major blockbuster release and the exclusion of Black Friday from the monthly data window.
- Console hardware sales fell 45% compared to November 2023, though the PlayStation 5 Pro launch accounted for 26% of all PS5 units sold during the month.
- Black Friday week sales reached 1.53 million units, representing an 8% year-over-year decline.
- Call of Duty: Black Ops 6 held the top spot in the monthly charts, while EA Sports FC 25 sales declined 22% compared to the same period in 2023.
- New releases underperformed, with Dragon Age: The Veilguard debuting at number three with a slower sales trajectory than other major 2024 titles, and Mario & Luigi: Brothership trailing the physical sales of recent Mario RPG entries.
GamesIndustry.bizDec 2024
Article
Dragon Ball and Undisputed Sales: UK Monthly Report October 2024
The UK video game market experienced a modest growth in software sales during October 2024, with 2.9 million units sold, representing a 3.2% increase compared to the same period in 2023. This performance was driven by several high-profile releases, though the hardware sector continued to face significant headwinds. Data for this analysis is provided by GSD, which tracks both digital and physical sales across major platforms, and NielsenIQ/GfK for hardware and accessory metrics.
Call of Duty: Black Ops 6 secured the top spot in the monthly charts. While premium sales were 11% lower than the previous year's entry, this decline is attributed to the title’s inclusion in the Game Pass subscription service. Notably, premium sales on PlayStation platforms, where the subscription service is unavailable, rose by 24% year-on-year. Other notable performers included Dragon Ball: Sparkling! Zero, which saw sales 80% higher than the franchise's previous best, and the boxing title Undisputed, which emerged as a significant commercial success. Conversely, Silent Hill 2 and EA Sports FC 25 underperformed relative to their respective benchmarks or prior iterations.
Hardware sales remain a point of concern, with total console volume down 18% compared to October 2023, despite a 14% month-on-month increase to 144,000 units. All major platforms—PlayStation 5, Nintendo Switch, and Xbox Series—recorded year-on-year declines ranging from 17% to 18%. While the broader software market shows resilience through strong new releases, the hardware segment continues to struggle with year-over-year contraction, reflecting a challenging environment for console manufacturers in the UK market.
- UK software sales reached 2.9 million units in October 2024, a 3.2% year-on-year increase driven by high-profile new releases.
- Console hardware sales declined by 18% year-on-year, with PlayStation 5, Nintendo Switch, and Xbox Series all recording double-digit drops.
- Call of Duty: Black Ops 6 topped the monthly charts, with a 24% year-on-year increase in premium PlayStation sales offsetting an 11% decline in overall premium sales attributed to Game Pass availability.
- Dragon Ball: Sparkling! Zero achieved significant commercial success, recording sales 80% higher than the franchise's previous best performance.
- Despite a 14% month-on-month increase to 144,000 units, total console volume remains down compared to October 2023 levels.
GamesIndustry.bizNov 2024
Article
Around 21% of European Games Professionals Have Been Laid Off in the Past Year
The Big Games Industry Employment Survey, conducted by Values Value and InGame Job, reveals significant instability within the European gaming sector. Between 2023 and 2024, approximately 21% of industry professionals in Europe experienced layoffs. Of those affected, 15% successfully transitioned into new roles within the industry, while 6.2% remained unemployed at the time of the survey. Furthermore, 10% of displaced workers opted to leave the games industry entirely for employment in other sectors.
The research, which gathered data from 1,832 respondents across more than 50 European countries between March and June 2024, identifies specific vulnerabilities in the workforce. Roles in human resources, recruitment, quality assurance, and art were disproportionately affected by staff reductions. There is a notable correlation between these high-turnover roles and stagnant or declining salary levels, particularly for junior staff and senior-level HR and recruitment specialists. While median salaries generally increased across the industry, these specific segments saw year-on-year decreases.
Beyond employment trends, the survey highlights persistent challenges regarding workplace culture, with burnout, unprofessional management, and poor work-life balance cited as primary drivers of job dissatisfaction. The industry also shows a growing reliance on technology, with 54% of developers reporting the integration of AI into their daily workflows, a significant increase from 37% in the previous year. Additionally, the data underscores a continued prevalence of remote work, with 57% of EU-based companies and 75% of non-EU European companies maintaining remote operations. These findings collectively illustrate a complex landscape defined by economic volatility, shifting labor demands, and evolving operational practices.
- Approximately 21% of European games industry professionals experienced layoffs between 2023 and 2024, with 6.2% remaining unemployed and 10% exiting the sector entirely.
- Human resources, recruitment, quality assurance, and art roles were disproportionately impacted by staff reductions during the survey period.
- While median industry salaries rose, junior staff and senior-level HR and recruitment specialists faced year-on-year salary decreases.
- AI integration in daily developer workflows increased significantly, rising from 37% in the previous year to 54% in 2024.
- Remote work remains a standard practice, utilized by 57% of EU-based companies and 75% of non-EU European companies.
+1
GamesIndustry.bizNov 2024
Article
Video Game Sales: Europe September 2024
Video game sales across Europe experienced a significant surge in September 2024, with total volume increasing by more than 20% compared to the same period in 2023. A total of 17.6 million PC and console games were sold during the month, driven by a mix of high-profile new releases and aggressive promotional activity. EA Sports FC 25 secured the top position in the charts, demonstrating strong performance in its premium tier despite a slight overall dip in launch-week sales compared to its predecessor.
The market saw notable success from Warhammer 40,000: Space Marine 2, which emerged as a breakout hit and is on track to become the fastest-selling title in the franchise's history. Other significant performers included Astro Bot, which outperformed several recent AAA 3D platformers, and The Crew 2, which saw a massive boost in engagement due to a promotional campaign that effectively offered the game for a nominal fee. Conversely, hardware sales faced a downturn, with console volume dropping 18% year-on-year to 335,000 units. While the PlayStation 5 remained the market leader, the Nintendo Switch saw a modest 1.5% increase in sales, while Xbox hardware experienced a 58% decline.
The analysis relies on GSD figures, which aggregate digital and physical sales data across a wide range of European markets. Digital data encompasses major publishers and platforms, though notable exceptions like Nintendo limit the scope of digital reporting for their specific titles. Physical data is tracked across 15 European countries, while hardware and accessory metrics cover a slightly smaller subset of these regions. This data provides a comprehensive overview of the European gaming landscape, highlighting shifting consumer preferences and the impact of both new software launches and hardware lifecycle stages.
- European video game sales volume rose by over 20% year-on-year in September 2024, reaching a total of 17.6 million units sold.
- Console hardware sales declined 18% year-on-year to 335,000 units, with Xbox hardware suffering a 58% drop while Nintendo Switch sales grew by 1.5%.
- EA Sports FC 25 topped the September charts, while Warhammer 40,000: Space Marine 2 emerged as a breakout hit on track to be the fastest-selling title in its franchise.
- The Crew 2 experienced a significant surge in engagement driven by a promotional campaign that offered the game for a nominal fee.
- Astro Bot performed strongly in September, outpacing several recent AAA 3D platformers in the European market.
GamesIndustry.bizOct 2024
Article
EA Sports FC 25, Space Marine 2, Astro Bot and PS5 Impress: September UK Monthly Charts
The UK video game market experienced a robust September, with 3.88 million console and PC games sold, representing an 8% increase compared to the same period in the previous year. This growth was largely driven by a strong influx of new releases, with six titles debuting in the monthly top ten. EA Sports FC 25 secured the top position, despite a 4.6% decline in launch sales compared to its predecessor, though premium early access editions showed year-on-year growth. Warhammer 40,000: Space Marine 2 performed exceptionally well, ranking as the second best-selling game of the month and the third best-selling new release of the year to date.
Other notable market activity included a significant surge in sales for The Crew 2, which reached third place following a deep price discount. Conversely, Star Wars Outlaws experienced a slower start, tracking behind the performance of previous titles from the same studio. Astro Bot also saw a strong debut, with sales in its first four weeks outpacing those of Ratchet & Clank: Rift Apart by 24%.
Hardware sales faced a downturn, with 126,000 consoles sold, a 35% decrease from September 2023. The PlayStation 5 remained the market leader, bolstered by strong performance from the All-Digital model. While total console sales for the year are down 32% compared to 2023, the accessories market saw an 11% increase in units sold. The PlayStation Portal Remote Player continued to be a standout performer, maintaining its position as a top-revenue-generating accessory throughout the first nine months of 2024. Data for these findings was provided by GSD and NielsenIQ/GfK, covering retail and digital sales across the UK.
- The UK video game market grew 8% year-on-year in September, with 3.88 million console and PC games sold driven by six new top-ten releases.
- EA Sports FC 25 debuted at number one, despite a 4.6% decline in launch sales compared to its predecessor.
- Warhammer 40,000: Space Marine 2 became the second best-selling game of the month and the third best-selling new release of 2024 so far.
- Console hardware sales dropped 35% year-on-year to 126,000 units, contributing to a 32% decline in total console sales for the year to date.
- Astro Bot outperformed Ratchet & Clank: Rift Apart by 24% in its first four weeks of sales.
+1
GamesIndustry.bizOct 2024
Article
Grand Theft Auto 5 is No.1 Again in August: European Monthly Charts
The European video game market experienced a 7% year-on-year increase in software sales during August 2024, with 11.8 million console and PC units sold. This growth was primarily driven by promotional activity surrounding legacy titles, most notably Grand Theft Auto 5, which reclaimed the top spot in the monthly charts. The launch of Star Wars Outlaws secured the second position, though its initial performance was noted as being less than half of the launch sales achieved by Star Wars Jedi: Survivor in 2023.
Data for these findings is provided by GSD, which aggregates digital sales from major publishers alongside physical retail data across key European markets. While the software segment saw growth, the hardware market faced a significant downturn. Console sales reached just over 300,000 units, representing a 42% decline compared to August of the previous year, with year-to-date console sales down 29%. The PlayStation 5 remained the market leader despite a year-on-year sales drop exceeding 50%, followed by the Nintendo Switch, which saw a 25% decline.
The report also highlights the volatility of new releases, noting that Sony’s Concord failed to gain traction, charting at number 347 before being pulled from sale. Additionally, the absence of digital sales data for Black Myth: Wukong limited its representation in the rankings. The accessories market also struggled, recording 1.1 million items sold, a 17% decrease from the same period in 2023. These figures underscore a broader trend of reliance on established legacy franchises to sustain software volume amidst a cooling hardware market.
- European console hardware sales plummeted 42% year-on-year in August 2024 to just over 300,000 units, with year-to-date sales down 29%.
- Software sales grew 7% year-on-year to 11.8 million units, driven largely by promotional activity for legacy titles like Grand Theft Auto 5, which reclaimed the number one spot.
- Star Wars Outlaws debuted at number two, but its initial sales were less than half of those achieved by Star Wars Jedi: Survivor during its 2023 launch.
- PlayStation 5 remained the market-leading console despite a year-on-year sales decline exceeding 50%, while Nintendo Switch sales fell 25%.
- The accessories market saw a 17% year-on-year decline, with 1.1 million items sold during August.
+1
GamesIndustry.bizSept 2024
Article
The Brazilian Games Industry in Numbers
The Brazilian games industry has experienced significant expansion, evolving from 133 studios in 2014 to 1,042 developers by 2023. This growth is characterized by a prevalence of micro and small studios, with 93% focusing on original intellectual property. The industry employed 13,225 professionals as of 2023, reflecting a 6.3% year-over-year increase. While the workforce remains male-dominated at 74.2%, the sector maintains a highly flexible operational model, with 70% of studios functioning remotely.
Market data indicates that the Brazilian game development industry generated approximately $251.6 million in revenue in 2023. Although mobile gaming dominates the broader consumer market at 51.7%, domestic production is more diversified, with PC and mobile titles each accounting for roughly 24% of output. International collaboration is a critical component of this growth, as many studios engage in work-for-hire services, particularly with partners in the United States, Latin America, and an increasingly prominent Western Europe.
These findings are derived from the second national survey of the games industry, conducted by the Brazilian Association of Digital Game Developers (Abragames) and the Brazilian Agency for Promotion of Exports and Investments (ApexBrasil). The research utilized data from 343 participating studios, representing approximately one-third of the total national ecosystem. Beyond the development landscape, the report highlights Brazil’s status as the largest games market in Latin America, boasting an audience of 103 million players, 82% of whom identify gaming as a primary form of entertainment. The demographic profile of this audience is broad, with a majority of players aged between 19 and 44.
- Brazil’s game development sector has grown from 133 studios in 2014 to 1,042 developers by 2023, with 93% of these studios focusing on original intellectual property.
- The industry generated $251.6 million in revenue in 2023 and employs 13,225 professionals, marking a 6.3% year-over-year increase in the workforce.
- Brazil is the largest gaming market in Latin America, supported by a player base of 103 million people, 82% of whom consider gaming their primary form of entertainment.
- While mobile gaming accounts for 51.7% of the broader consumer market, domestic studio production is evenly split, with PC and mobile titles each representing approximately 24% of output.
- The industry operates with high flexibility, as 70% of studios function remotely, though the workforce remains male-dominated at 74.2%.
GamesIndustry.bizSept 2024
Article
75% of Games Sold in August Were Downloaded: UK Monthly Charts
The UK video game market experienced a notable shift toward digital consumption in August 2024, with 75% of all games sold by major publishers being digital downloads. This figure represents a 10-percentage-point increase compared to the same period in 2023, signaling a continued transition away from physical media. Overall, 1.74 million video games were sold during the month, marking a slight year-over-year decline of 1.5%.
Market performance was characterized by a quiet release schedule, with Take-Two Interactive titles dominating the top of the charts. Grand Theft Auto 5 secured the number one position, while promotional activity surrounding the Borderlands franchise propelled multiple entries from that series into the top ten. New releases struggled to gain significant traction, as evidenced by Madden NFL 25, which saw a 31.5% decline in sales compared to its predecessor after two weeks on the market.
Hardware and accessory sectors faced a challenging summer, with console sales dropping 45% compared to the previous year, totaling fewer than 75,000 units. The PlayStation 5, Nintendo Switch, and Xbox Series consoles all experienced year-over-year declines, with the latter two alternating between the second and third positions throughout the year. Accessory sales also trended downward, falling 9.6% compared to August 2023.
The analysis utilizes GSD data for software sales, which tracks digital and physical purchases from a wide range of major publishers, and GfK figures for hardware and accessory performance. The scope of the data is limited to the UK market and covers the period ending August 24, 2024.
- Digital downloads accounted for 75% of all major publisher game sales in the UK in August 2024, a 10-percentage-point increase over August 2023.
- Total video game sales reached 1.74 million units in August 2024, representing a 1.5% year-over-year decline.
- Console hardware sales dropped 45% year-over-year to fewer than 75,000 units, with the PlayStation 5, Nintendo Switch, and Xbox Series consoles all seeing declines.
- Take-Two Interactive dominated the August charts, with Grand Theft Auto 5 taking the top spot and multiple Borderlands titles entering the top ten due to promotions.
- New releases underperformed, highlighted by Madden NFL 25, which saw a 31.5% decline in sales compared to its predecessor after two weeks on the market.
GamesIndustry.bizSept 2024