The current landscape of the video game industry in 2024 reflects a complex transition between established hardware platforms and evolving consumer behaviors. While physical media remains a topic of industry discourse, the broader market is characterized by a shift toward digital services, subscription-based revenue models, and the dominance of mobile gaming. Recent performance data from major players like PlayStation highlights a reliance on yield-focused strategies, such as price adjustments and service tier upgrades, to drive revenue growth despite fluctuations in hardware unit sales and currency values.
Industry analysis indicates that consumer engagement is deepening, with average weekly playtime increasing to 14.5 hours. However, spending patterns remain polarized; while the average American gamer spent $56.20 on games over a six-month period, nearly half of the gaming population made no purchases during that timeframe. This suggests that while core engagement is rising, monetization remains highly dependent on a subset of active spenders. Furthermore, the market is increasingly influenced by the consolidation of younger audiences into massive ecosystems like Roblox and Fortnite, which have effectively displaced traditional children’s MMOs.
Looking ahead, the industry is positioning itself for a potential rebound, with projections suggesting a 15% growth in the PC and console sectors between 2024 and 2028. Strategic developments, such as Nintendo’s commitment to backward compatibility for its next-generation hardware and the introduction of new Steamworks APIs for build management, underscore a focus on long-term platform stability and developer flexibility. These trends, combined with the continued dominance of high-grossing mobile titles, define a market that is prioritizing ecosystem retention and service-based monetization over traditional retail models.
The primary purpose of this analysis is to examine the volatility of Steam wishlist conversion rates and identify why high wishlist counts do not always translate into successful launch-day sales. The central thesis posits that wishlists are often casual bookmarks rather than firm commitments to purchase, and that developers must focus on converting these "eyeballs" into buyers at the moment of release through clear value propositions and gameplay accessibility.
Data indicates that the median conversion rate for games with over 10,000 wishlists is approximately 0.17x of the wishlist balance during the first week of release. However, this figure is highly variable, ranging from below 0.02x to over 1x. A case study of the title The Axis Unseen highlights this disparity; despite securing over 150,000 wishlists, the game experienced a significantly lower-than-expected conversion rate of 0.02x to 0.03x. Analysis suggests this underperformance stemmed from a mismatch between player expectations—driven by the game's high-fidelity visuals and the developer's background—and the actual, niche hunting-based gameplay.
The scope of this analysis covers the global PC gaming market, specifically focusing on Steam platform trends and discovery mechanics during the latter half of 2024. The findings are derived from proprietary platform data, comparative analysis of game performance, and audience affinity metrics. The document concludes that developers should prioritize genres with established, underserved audiences and ensure that marketing materials accurately reflect the core gameplay loop to avoid attracting "soft" wishlists from users who are unlikely to purchase the final product.
This analysis examines the evolving landscape of the PC handheld market, specifically focusing on the Steam Deck’s influence on player behavior and game discovery. While the total installed base of the Steam Deck remains an estimate—likely approaching 5 million units based on growth in associated software usage—recent platform updates have provided new transparency regarding how users interact with the device.
The primary development enabling this insight is a new Steam feature that identifies user reviews submitted by players who have spent more than 50% of their playtime for a specific title on a Steam Deck. By cross-referencing this data with Valve’s official charts of the most-played games by total hours, analysts can now quantify the specific appeal of various titles within the handheld ecosystem. This methodology allows for a more granular understanding of which games resonate most strongly with the mobile-first PC audience.
Beyond the specific metrics of the Steam Deck, the broader industry context reveals significant shifts in platform performance. Recent financial disclosures from major players like Microsoft and Roblox highlight the ongoing importance of subscription services and algorithmic discovery in driving engagement. Furthermore, the industry continues to grapple with the challenges of new IP penetration in the competitive shooter market and the increasing necessity for platform-level transparency, such as Steam’s new requirements for disclosing kernel-level anti-cheat software. These trends collectively underscore a move toward more data-driven platform management and a deeper focus on how hardware-specific play patterns influence long-term game success.
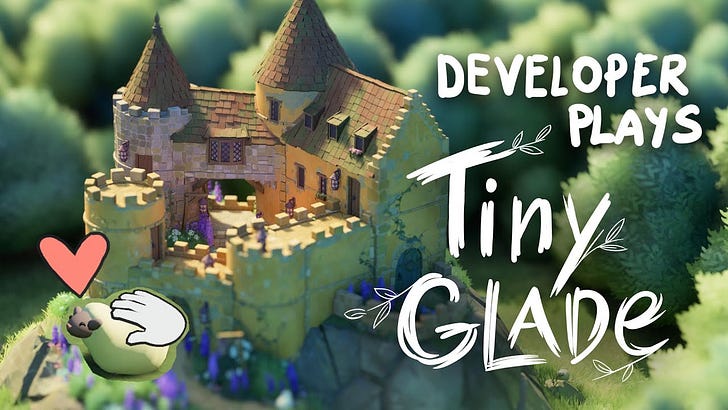
The rapid commercial success of the relaxing building game Tiny Glade serves as a case study for effective game discovery and audience engagement in the modern PC market. Developed by Pounce Light, the title achieved over 616,000 copies sold within its first month of release on Steam. This performance is attributed to a consistent, two-year marketing strategy that leveraged viral social media content, active participation in Steam Next Fest, and a clear appeal to the "cozy" gaming demographic.
Key performance metrics highlight the game’s unique position in the market. While the median playtime is approximately 64 minutes, the title maintains a high daily active user count relative to its concurrent users, suggesting it functions effectively as a "software toy" or sandbox experience rather than a traditional goal-oriented game. The player base is primarily concentrated in the United States, which accounts for 32% of sales, followed by Germany, France, the UK, and China. The game’s success was bolstered by over 1.37 million wishlists at launch and sustained interest from influencers and streamers, which helped maintain a long-tail sales trajectory without the need for initial discounts.
The development process emphasized iterative design, with the creators conducting five external playtests over two years to refine the user experience. The team utilized procedural generation not for infinite content, but to ensure that player inputs—such as drawing walls or fences—resulted in satisfying, tactile, and responsive outcomes. By prioritizing design pillars like "no wrong answers" and "a lot from little effort," the developers successfully captured a market segment interested in creative, low-pressure experiences, demonstrating that high-quality, freeform titles can achieve significant financial scale in the current industry landscape.
The current landscape of video game discovery is shaped by shifting consumer behaviors, platform-specific trends, and evolving marketing strategies. A primary finding indicates that influencer marketing remains the most effective promotional tool for PC and console titles, significantly outpacing traditional events and paid media. Furthermore, the industry is experiencing a notable decline in console hardware spending, which reached its lowest September levels since 2019, while the market continues to see a rise in all-digital console units.
Data highlights reveal that mobile gaming revenue models are increasingly reliant on high-spending "whale" players, with top-grossing titles incentivizing significant end-game investment. In the console space, platform loyalty remains a critical factor for success, as evidenced by the Silent Hill 2 remake, which saw 78% of its European sales occur on PlayStation 5. Meanwhile, platform holders are actively refining their ecosystems, with Apple reportedly developing a dedicated gaming app to consolidate App Store and Game Center functionality, and Valve navigating legal challenges regarding data privacy and antitrust regulations.
These insights are derived from a combination of industry surveys, such as the Bastion video game marketing report, and platform-specific data from sources including Circana, SteamDB, and internal GameDiscoverCo charts. The scope of this analysis covers the global video game industry, with a specific focus on the North American and European markets during the latter half of 2024. The findings underscore a challenging environment for developers, where aligning product releases with seasonal trends and understanding platform-specific audience preferences are essential for navigating the complexities of modern game discovery.
The October 2024 Steam Next Fest marked a significant shift in event structure, as Valve introduced a randomized, auto-advancing showcase for the first three days to address long-standing concerns regarding visibility inequality. Following this initial period, the platform transitioned to a personalized recommendation model based on user preferences rather than raw wishlist counts or demo play volume. Despite the event’s massive growth in scale—featuring between 2,700 and 3,100 demos compared to roughly 1,350 to 1,800 in June 2024—the data suggests that the new format successfully provided visibility to a broader range of titles.
Performance metrics indicate that while top-tier games continue to see high concurrent user (CCU) counts, the event has become an essential marketing beat for developers of all sizes. Free-to-play titles backed by major corporations dominated the top of the charts, including Delta Force, Supervive, and Strinova. However, smaller, independent titles such as The Precinct, Permafrost, and Luma Island also achieved notable breakout success. Analysis of follower growth reveals that lower-ranked games experienced a meaningful increase in interest compared to previous editions, with the 500th-ranked game seeing a significant rise in follower additions between February and October 2024.
The methodology relies on tracking Steam follower increases and peak concurrent user data across thousands of titles. While the influx of large-scale multiplayer games has contributed to higher overall CCU figures, the data confirms that the event remains a critical discovery mechanism. The findings suggest that high-quality, diverse game offerings remain the primary driver of engagement, even as the platform continues to refine its discovery algorithms to mitigate the "rich get richer" phenomenon.
The primary purpose of this analysis is to expose the sophisticated methods used by scammers to obtain Steam keys from game developers under false pretenses. The central thesis is that while basic phishing attempts are easily identified, a new wave of highly organized, deceptive operations—often involving fake influencer personas—poses a significant threat to developers by exploiting the trust-based system of distributing press and influencer keys for resale on gray-market platforms.
Key findings indicate that scammers are increasingly employing a "shotgun, then rifle" strategy. This involves blasting mass requests to developers and then refining their approach based on successful interactions. These sophisticated actors invest in creating high-quality, deceptive assets, including purchasing fake YouTube subscribers, commissioning custom thumbnails, and utilizing plausible voice-over scripts to mimic legitimate content creators. By successfully passing internal developer verification checks, these groups can scale their operations across multiple channels to maximize illicit profits.
The scope of this issue is global, specifically targeting the PC gaming industry and the Steam ecosystem. The analysis highlights that while tools like Keymailer or manual verification steps—such as requiring influencers to reply via official channels—can mitigate risk, the threat remains persistent and evolving. The rise of AI-generated content further complicates the landscape, as it allows for the rapid creation of convincing, fake virtual influencers.
The analysis relies on industry observations, anecdotal evidence from developer communities, and historical context regarding fraud strategies. It emphasizes that the problem is not merely a nuisance but a scalable, professionalized criminal enterprise that requires constant vigilance from developers and marketers to protect their intellectual property and revenue streams.
The analysis examines the geographic distribution of PC game ownership on Steam, specifically identifying titles with the highest concentrations of players in the United States and Japan. By leveraging a methodology that utilizes randomly sampled player profiles, the research aims to provide developers and industry stakeholders with actionable insights into regional market penetration and audience demographics. The scope is limited to games that have achieved a lifetime sales volume exceeding 100,000 units on the Steam platform.
The core objective is to categorize and rank games based on their national player base percentages, offering a clearer picture of how specific titles resonate within distinct cultural and regional markets. By isolating high-performing games in the U.S. and Japan, the findings highlight the variance in consumer preferences and the effectiveness of regional targeting strategies. This approach allows for a more granular understanding of global gaming trends, moving beyond aggregate sales figures to reveal the specific geographic composition of a game's community.
Ultimately, the analysis serves as a tool for benchmarking regional success, helping industry professionals understand which genres or titles maintain the strongest hold in key territories. By focusing on established games with significant commercial success, the data provides a reliable baseline for evaluating how regional demographics influence the long-term viability and reach of PC software. This methodology underscores the importance of geographic data in refining marketing and development strategies for a globalized gaming audience.
The recent report by Hindenburg Research regarding Roblox has sparked significant industry discussion, primarily focusing on allegations of inflated user metrics and compromised child safety. The activist short-seller claims that Roblox misrepresents its scale by failing to adequately account for bots and alternative accounts, suggesting that daily active user (DAU) figures and engagement hours are inflated by 25% to 100% or more. Additionally, the report criticizes the company’s reduction in trust and safety expenditures, arguing that this prioritization of profitability over moderation exposes children to predatory behavior.
While these allegations led to a temporary 9% dip in Roblox’s market capitalization, the broader industry perspective suggests that while the claims highlight genuine operational challenges, they do not necessarily indicate systemic bad faith. The platform’s massive, chaotic nature inherently invites bot activity, and the distinction between unique human players and automated accounts remains a complex, ongoing technical hurdle. Furthermore, while Roblox faces legitimate pressure to improve its content moderation, the company maintains a strong financial trajectory, with revenue growing 31% year-over-year in the most recent quarter.
Beyond the Roblox controversy, the broader gaming landscape shows continued vitality. Data from September 2024 highlights strong performance for titles like World of Warcraft, which saw a 70% increase in hours watched following its latest expansion, and successful debuts for EA Sports FC 25 and Warhammer 40,000: Space Marine II. Other notable industry developments include a significant legal victory for Epic Games against Google regarding third-party app store distribution, and ongoing shifts in how developers approach megabudget game scopes and return-on-investment expectations. These trends underscore a market that remains highly active, even as it grapples with evolving platform policies and discovery challenges.
The evolving nature of the long tail in PC gaming revenue is increasingly defined by the performance of simulator-focused portfolios on Steam. By analyzing data from PlayWay, a prominent publisher specializing in simulation titles, the industry gains insight into how revenue distribution patterns for older titles have shifted in the current market. This analysis serves to clarify the sustainability of back-catalog sales and the mechanisms that drive continued consumer interest in established PC games.
The findings highlight that the long tail—the period of sustained revenue generation following a game's initial launch—is undergoing a structural transformation. While specific data points remain proprietary to the publisher's internal reporting, the core conclusion suggests that strategic management of simulation-heavy catalogs allows for consistent, albeit evolving, revenue streams long after the primary marketing window has closed. This trend underscores the importance of platform-specific discovery and the role of niche genres in maintaining long-term commercial viability on digital storefronts.
The scope of this analysis is limited to the PC gaming sector, specifically focusing on the Steam ecosystem as of late 2024. By utilizing internal performance metrics from a specialized publisher, the assessment provides a targeted look at how simulation games maintain relevance. The methodology relies on longitudinal revenue tracking, offering a practical perspective on the lifecycle of titles within a high-volume, niche-oriented publishing model. Ultimately, the data illustrates that the long tail is not a static phenomenon but a dynamic outcome of ongoing engagement strategies within the modern digital distribution landscape.
This analysis examines the impact of user-generated content (UGC) on the long-term commercial performance and player retention of PC games. By evaluating approximately 1,000 titles on Steam that generated at least $1 million in their first month and maintained at least 10,000 lifetime reviews, the study identifies a clear performance gap between games that integrate UGC and those that do not. While the revenue advantage for games with UGC is a modest 7% after one year, this figure expands significantly to 23% over a five-year period.
The findings further indicate that UGC serves as a powerful driver for player retention. Games incorporating UGC demonstrate 64% higher concurrent user (CCU) retention after two years, rising to 90% after five years compared to non-UGC titles. While the research acknowledges a potential correlation-versus-causation dilemma—specifically whether successful games are more likely to implement UGC or if UGC inherently fosters longevity—the data suggests that free UGC and paid downloadable content (DLC) can coexist effectively. Evidence from specific titles shows that players engaging with UGC are 2.4 times more likely to purchase additional DLC.
Beyond UGC, the analysis explores regional variations in player sentiment by comparing English and Simplified Chinese Steam reviews. Across 8,000 surveyed games, there is a documented trend where games generally receive slightly higher positivity ratings in English than in Simplified Chinese. This disparity is more pronounced in larger titles, with the median game reviewed 2% more positively in English. The analysis attributes some of these differences to cultural preferences regarding game difficulty and specific regional issues, such as platform-related account requirements, highlighting the importance of regional context in interpreting player feedback.
The primary objective of this analysis is to evaluate the risks associated with launching titles in Steam Early Access, specifically focusing on the tension between pre-release marketing hype and the actual state of a game upon launch. The central thesis posits that developers often fall into an expectation-reality trap when high levels of consumer anticipation are met with a product that is perceived as insufficiently polished or mechanically flawed, leading to negative player reception.
The analysis highlights the recent launch of the extraction shooter The Forever Winter as a primary case study. Despite generating significant pre-release interest—evidenced by viral promotional content, such as a video garnering 2.9 million views—the title struggled upon its debut. While the game achieved a notable peak of over 12,500 concurrent users, it faced immediate backlash regarding its gameplay mechanics and overall technical state. This discrepancy suggests that while effective marketing can drive initial traffic, it cannot compensate for a lack of core stability or feature readiness in an early access environment.
The scope of this assessment is limited to the contemporary Steam ecosystem, specifically examining trends in late 2024. By tracking concurrent user data and community sentiment, the analysis underscores the volatility of the current market, where 12 games debuted with at least 1,000 concurrent users in a single week. Ultimately, the findings serve as a cautionary note for developers: launching too early, even with substantial community momentum, risks alienating the core audience if the product fails to align with the expectations established during the promotional phase.