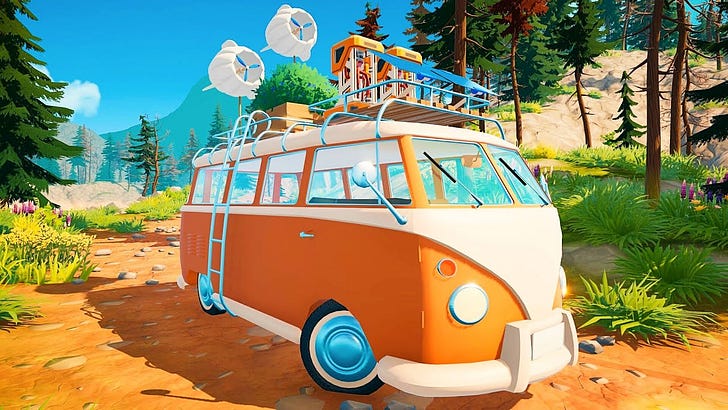
The primary objective is to analyze the marketing and discovery strategies that propelled the indie game Outbound to over 600,000 Steam wishlists within a year of its announcement. The analysis highlights how Square Glade Games leveraged a specific, aspirational "cozy" survival niche—centered on the concept of a mobile camper van base—to capture significant player interest. Key findings indicate that the game’s success was driven by a combination of high-visibility social media content, particularly on TikTok and YouTube, and strategic participation in Steam Festivals. Furthermore, a successful Kickstarter campaign, which raised 265,000 Euros, served as a critical catalyst for building early momentum and community engagement.
The analysis emphasizes the importance of clear conceptual positioning, noting that while Outbound successfully attracted a large audience, it faces the common challenge of managing player expectations. Because the game focuses on a non-combat, relaxing experience, the developers must actively clarify the gameplay loop to prevent potential players from projecting traditional survival mechanics, such as combat or hunger systems, onto the title. The data underscores that while high wishlist counts are a significant achievement, they necessitate proactive communication to ensure that the final product aligns with the audience's anticipated experience.
Beyond the specific case study of Outbound, the analysis provides broader industry insights regarding game discovery and performance as of early 2025. This includes data on the most-streamed games of December 2024, noting the strong performance of Path of Exile 2 and Marvel Rivals, as well as the enduring popularity of Grand Theft Auto V. The scope of the coverage spans global PC and console gaming trends, utilizing data from platforms like Steam and Stream Hatchet to evaluate how developers can navigate the competitive landscape of the 2020s.
The gaming industry landscape in 2024 reflects a shift toward focused, high-quality releases and a move away from the oversaturation of mid-tier, or AA, titles. Analysis of market performance indicates that successful companies are increasingly prioritizing either hyper-cost-conscious production models or highly concentrated release strategies to avoid internal product cannibalization. This trend is supported by broader industry data showing that while graphics remain a point of interest, they are no longer the primary driver of commercial success, as the financial viability of optimizing cinematic experiences for a narrow hardware demographic continues to decline.
Data from 2024 highlights significant activity across major platforms. On Steam, the number of editorial homepage takeovers increased to 115, up from 94 in 2023, signaling a continued reliance on platform-driven discovery. Meanwhile, the U.S. hardware market saw the Nintendo Switch surpass the PlayStation 2 in lifetime unit sales, and PlayStation 5 revenue grew 15% year-over-year, bolstered by the release of the PS5 Pro. Twitch viewership remained stable, with 18.9 billion hours watched, though the top 10 most-streamed titles have remained largely unchanged for five years, dominated by established live-service giants like Grand Theft Auto, League of Legends, and Fortnite.
The industry also continues to adapt to evolving consumer habits, such as the use of remote-play hardware like the PlayStation Portal, which sees peak usage shift to later evening hours as players relinquish primary television access to family members. As the market looks toward future hardware iterations, such as the anticipated successor to the Nintendo Switch, the consensus remains that long-term success is increasingly tied to gameplay diversity and strategic market positioning rather than sheer volume of output.
The 2025 UGC Impact Study, conducted by GameDiscoverCo and commissioned by mod.io, analyzes the commercial and engagement benefits of integrating official user-generated content (UGC) support into video games. The research demonstrates that games offering official modding tools or content-sharing solutions consistently outperform those without such features across PC, console, and VR platforms. By examining a dataset of approximately 1,200 Steam games that generated at least $1 million in their first month, the study finds that titles with UGC support see an 8% revenue advantage after one year, which expands to 31% after five years.
The primary driver for this long-term financial success is significantly higher player retention. On PC, games with UGC support maintain 75% higher concurrent user counts after two years and 115% higher after five years compared to games without these features. Furthermore, the research refutes concerns regarding the cannibalization of official content; games with UGC support actually see 105% higher median revenue per DLC. Case studies, such as Baldur’s Gate 3 and SnowRunner, support these findings, with the latter noting that players using mods were 2.4 times more likely to purchase official DLC.
The scope of the study extends beyond PC to include PlayStation, Xbox, and Meta Quest platforms. On consoles, the impact is even more pronounced in the short term, with UGC-supported titles showing a 16% performance boost on PlayStation and a 24% boost on Xbox after one year. In the VR sector, titles with UGC support experienced 30% more median growth over the past year than those without. The methodology evolved from previous years to include not just Steam Workshop, but also middleware solutions like mod.io and proprietary studio tools, suggesting that the positive correlation between UGC and commercial longevity is a robust, industry-wide trend.
This analysis provides a comprehensive overview of the top-performing PC and console games of 2024, utilizing proprietary estimation algorithms to evaluate market success across Steam, PlayStation, and Xbox platforms. The primary objective is to identify the year’s most successful titles by sales volume and revenue, while also examining industry trends and audience engagement following major events like The Game Awards.
Key findings indicate that Black Myth: Wukong, Palworld, and Helldivers 2 dominated the Steam charts, with each title surpassing one million units sold. The data highlights a significant trend toward viral, lower-cost titles and specialized genres, such as first-person store management simulators, which have demonstrated high appeal among streamers. On the console front, sports titles remain the primary drivers of volume for both PlayStation and Xbox, though Xbox sales figures generally trail those of Steam and PlayStation. Notably, the analysis reveals that PlayStation’s performance in 2024 was bolstered by a substantial "gray market" of Chinese players, particularly for titles like Black Myth: Wukong.
The scope of this research covers global game performance throughout the 2024 calendar year. Methodology relies on internal data platforms that track concurrent user counts, estimated unit sales, and revenue, supplemented by external tracking services like Footprints.gg to measure media buzz and audience interest. Beyond sales data, the analysis explores the impact of platform-specific strategies, such as the influence of Game Pass on Xbox and the evolving landscape of viral marketing on platforms like Twitch. The findings conclude that while established franchises and sequels continue to command the most media attention, original intellectual properties and innovative indie titles remain vital components of the modern gaming ecosystem.
This analysis examines the current landscape of video game discovery and market performance as of mid-December 2024. The primary focus is on identifying high-performing titles across major platforms, including Steam, the Nintendo Switch eShop, and console storefronts, while highlighting significant industry shifts in marketing, platform policy, and hardware development.
Key findings indicate that major releases such as Indiana Jones and the Great Circle, Marvel Rivals, and Path of Exile 2 are currently dominating media coverage and consumer interest. On Steam, the highest-rated titles of 2024, determined by review volume and algorithmic scoring, include Balatro, Webfishing, and Satisfactory. Meanwhile, console charts show strong performance for recent remasters like Legacy of Kain: Soul Reaver 1&2 and The Thing, alongside established franchises. The report also notes that developers are increasingly utilizing viral social media strategies, such as Reddit-driven engagement, to bolster wishlists for smaller projects.
The industry is also navigating critical regulatory and operational updates. Valve has clarified its policies regarding third-party Steam sales, explicitly prohibiting organizers from charging for store placement. Additionally, the emergence of new hardware, such as potential SteamOS-powered handhelds from Lenovo, and the expansion of mixed reality through Android XR, represent significant shifts in platform accessibility. These trends occur against a backdrop of broader industry discourse regarding the prioritization of monetization in game design over traditional player-focused experiences. The data is synthesized from various industry sources, including SteamDB, official platform charts, and media coverage tracking, providing a comprehensive overview of the global gaming market’s current trajectory.
The physics-based medieval combat simulator Half Sword has achieved significant market traction, accumulating approximately 600,000 Steam wishlists. The game’s success is primarily attributed to an open development strategy that prioritized free, accessible demos and playtests, which generated millions of downloads and fostered a highly engaged community. This approach allowed the developers to leverage emergent, chaotic gameplay—a hallmark of the "serious but goofy" physics-based subgenre—to drive viral interest among content creators. Since July 2024, the game has been featured in over 10,000 videos across 3,000 channels, resulting in more than 100 million views.
The analysis highlights that while Half Sword’s appeal is global, its core audience remains concentrated in North America and Western Europe. The development team’s focus on historical accuracy, combined with the unpredictable nature of physics-driven combat, has proven to be a potent formula for streamer-friendly content. This strategy effectively bridges the gap between sandbox-style entertainment and deep, simulation-based mechanics, demonstrating a viable path for independent developers to build substantial pre-release momentum.
Beyond the specific case study of Half Sword, the broader industry context underscores the ongoing debate regarding the reliability of Steam wishlists as a predictive metric. While wishlists are not perfect calculators for future sales, they remain a critical, indicative tool for gauging market interest. Data suggests a clear correlation between Steam followers, wishlists, and lifetime revenue, reinforcing the necessity of using such metrics to inform strategic decision-making. Despite the challenges of an increasingly crowded marketplace, these data-driven insights remain essential for navigating game discovery in the 2020s.
The provided material serves as a broad industry update, focusing on current trends in game discovery, market performance, and consumer behavior within the PC and console sectors. The primary objective is to analyze how players engage with and discover video games in the 2020s, utilizing proprietary data sets and industry reporting to highlight shifting market dynamics. While the title references an analysis of PC game player percentages in the United Kingdom, France, and Germany, the content functions as a broader newsletter summarizing recent developments across the global gaming landscape.
Key findings include a notable shift in Steam’s promotional strategy, with Valve moving away from a "king-making" model toward a more egalitarian approach for its upcoming Next Fest events. Data indicates that gamers now spend more time consuming game-related video content—averaging 8.5 hours weekly—than they do actively playing games, which averages 7.4 hours. Additionally, the industry is seeing a decline in the percentage of adults who play games, with UK regulator Ofcom reporting a drop from 60% during the pandemic to 52% in 2024.
The scope of the information covers the global gaming industry, with specific data points drawn from the United States, Japan, the United Kingdom, France, and Germany. The analysis incorporates diverse sources, including Steam’s internal metrics, Switch eShop download charts, mobile gaming revenue reports, and regulatory findings from Ofcom. By synthesizing these disparate data streams, the summary provides a high-level overview of the current state of game discovery, hardware rumors, and the evolving relationship between game developers and their audiences.
This analysis examines the relationship between Steam wishlist counts and initial sales performance, addressing the industry’s shift toward a hit-driven market. By evaluating every Steam release from August through October 2024 with a minimum of 5,000 launch wishlists, the study provides a realistic assessment of conversion rates, which are often lower than anecdotal industry benchmarks suggest.
The data reveals a median first-week wishlist conversion rate of 10.5%. Performance varies significantly based on percentile rankings; while top-tier titles achieve high conversion, the consequences for underperforming games are severe, with the 25th percentile seeing a 4.8% conversion rate and the 10th percentile dropping to 1.9%. These findings suggest that while wishlists remain a useful indicator of interest, they are not a guaranteed predictor of commercial success. High-converting titles typically rely on a combination of strong franchise recognition, viral streamer engagement, or unexpected "surprise" appeal.
The broader market context highlights that new revenue is increasingly concentrated in a small number of massive hits, with the top five new releases of 2024 grossing over $2.2 billion. Consequently, developers are encouraged to balance their portfolios with both back-catalog "evergreens" and strategic bets on new titles. The analysis also underscores the efficacy of social media-driven marketing, as evidenced by case studies where clear, high-concept hooks and viral social media content successfully drive significant wishlist growth. Overall, the findings emphasize that in a competitive landscape, success is heavily dependent on capturing audience attention through distinct, high-quality hooks rather than relying solely on pre-launch wishlist accumulation.
The provided text serves as a broad industry update covering late 2024 trends in game discovery, platform policy, and market performance. While the title suggests a focus on the success of S.T.A.L.K.E.R. 2, the available content functions primarily as a newsletter digest, aggregating data from sources like Circana, SteamDB, and various industry trade organizations to analyze the current state of the global PC and console gaming markets.
Key findings highlight significant shifts in platform accessibility, specifically the expansion of cloud gaming services by Xbox and PlayStation. Market data indicates that while overall spending remains stable with a 1% year-to-date increase, performance varies by title; for instance, Call of Duty: Black Ops 6 outperformed its predecessor in initial sales, while Dragon Age: The Veilguard saw lower launch-week figures compared to other recent major releases. The industry also faces a challenging environment for independent developers, characterized by intense competition for limited market visibility and a growing reliance on strategic timing for events like Steam Next Fest.
The scope of the coverage is international, with specific data points focusing on the United States and European markets. Methodologically, the information is synthesized from third-party market research, platform-specific announcements, and industry expert commentary. The document concludes that success in the current landscape requires careful navigation of platform policies—such as Steam’s new season pass requirements—and a proactive approach to market signaling, where developers must validate their game concepts early through social engagement and community feedback.
The analysis examines the factors contributing to the rapid commercial success of the indie title Sulfur, which achieved over 50,000 unit sales on Steam within three weeks of its October 2024 launch. The primary thesis posits that the game’s success stems from a combination of rigorous iterative development, strategic community engagement, and a well-calibrated blend of genre influences that resonated with a specific, core audience. By utilizing multiple testing phases and public demos, the four-person development team at Perfect Random successfully built momentum, entering the market with 160,000 wishlists and maintaining strong player retention with a median playtime of nearly six hours.
Key data points highlight the importance of targeted marketing, as nearly 29,000 of the initial 52,000 units sold were purchased by users who had previously wishlisted the game. Notably, the title achieved significant traction in Japan, capturing 15% of its player base—a figure substantially higher than the 1.8% median for similar extraction-style shooters. The analysis attributes this performance to the team’s proactive localization efforts and the game’s distinct aesthetic, which balances gritty, high-stakes gameplay with a readable, stylized visual direction.
The scope of the analysis covers the PC indie market during the latter half of 2024, identifying a broader trend of "breakout" successes among mid-sized titles. Beyond Sulfur, the document highlights several other notable performers, including Mouthwashing, Fields of Mistria, and Liar’s Bar, noting that these titles often share characteristics such as lower price points, laser-focused market positioning, and strong reliance on word-of-mouth and streamer visibility. The methodology relies on platform-specific sales data, Steam concurrent user (CCU) metrics, and direct insights from developers to evaluate how modern indie games navigate discovery challenges in a crowded marketplace.
The provided text serves as a broad industry update, focusing on current trends in game discovery, platform shifts, and market performance across PC, console, and mobile sectors as of mid-November 2024. While the content introduces the topic of "Survivors-likes" as a genre analysis, the primary scope of the available information covers a wide range of industry news, including Steam follower velocity, Xbox marketing strategies, and recent performance data for major titles on the PlayStation and Nintendo Switch platforms.
Key findings highlight the dominance of established franchises and highly anticipated releases, such as the surge in interest for S.T.A.L.K.E.R. 2 following its "going gold" announcement. The industry is currently observing a shift in hardware strategy, particularly with Microsoft’s pivot toward multi-device accessibility and PC Game Pass, moving away from a console-exclusive paradigm. Furthermore, data regarding mobile gaming indicates that a small fraction of users—approximately 2%—accounts for nearly half of all in-app purchase revenue, underscoring the high concentration of value within top-tier player segments.
The analysis incorporates data from various sources, including Steam follower charts, eShop download rankings, and industry-wide reports on media coverage and monetization. These insights reflect a challenging environment for independent developers, where high wishlist counts do not always correlate with commercial success. The document also touches upon broader cultural and social issues within gaming communities, such as the need for improved content moderation on platforms like Steam, and the growing influence of VTubers in driving engagement and revenue through live streaming.
The analysis provides a comprehensive overview of the Nintendo Switch eShop landscape in 2024, focusing on sales performance for both first-party and third-party titles. By extrapolating data from U.S. and UK download rankings, the findings illustrate a market that remains heavily dominated by Nintendo’s internal releases. While the eShop has seen a significant influx of new content—averaging over 50 new games per week and totaling approximately 2,300 releases in 2024—third-party success remains concentrated in specific niches, particularly "cozy" games and classic collection re-releases.
Top-performing paid titles on the platform frequently reach hundreds of thousands of units, with the most successful games exceeding 1 million sales. Notable third-party successes include titles like Hogwarts Legacy, Balatro, and Little Kitty, Big City. The data suggests that while the Switch is a challenging environment for new third-party developers, specific strategies—such as skipping PC releases to drive platform exclusivity or leveraging established intellectual property—can significantly boost visibility and sales.
Beyond the Switch data, the analysis examines broader industry trends, including the evolving strategies of major platform holders. Observations include a decline in Nintendo Switch Online subscriptions, shifts in Meta’s funding priorities away from VR gaming, and the ongoing debate regarding the efficacy of Steam wishlist metrics. The findings emphasize that while data-driven decision-making is essential, the conversion of interest into sales remains unpredictable, often relying on viral momentum and strategic influencer partnerships rather than pre-launch metrics alone.