Akatsuki
Game Co.41 documents
Documents
Presentation46 pages
Consolidated Financial Results Briefing Materials: FY3/25
Akatsuki Inc. demonstrated significant financial resilience in FY3/25, characterized by a 46% year-over-year surge in consolidated operating profit to ¥3,915 million. While total sales experienced a marginal 1% decline, the core Games segment maintained stability through high-performing legacy titles such as Dragon Ball Z Dokkan Battle and Romancing SaGa Re;univerSe. Strong overseas performance and successful large-scale events effectively offset nearly ¥6 billion in development expenses for upcoming projects. This period also marked a strategic turning point as the Comics and IP Solutions segments achieved profitability, driven by the international launch of the MANGA MIRAI service and the rapid expansion of the Slash Gift online lottery platform.
The company’s investment arm further bolstered the balance sheet, realizing ¥2,840 million in proceeds during the fiscal year with additional capital gains anticipated from the IPO of LIFE CREATE Co., Ltd. in early FY3/26. Despite a reduction in total headcount from 803 to 697, primarily within the Games division, permanent staffing levels remained consistent, reflecting a shift toward operational efficiency. This lean organizational structure supports a robust financial position, with ¥33.3 billion in cash reserves earmarked for a ¥35 billion growth investment plan over the next three years, focusing on mergers, acquisitions, and next-generation game development.
Looking toward FY3/26, the group anticipates sustained growth in sales and profit, anchored by the upcoming release of Kaiju No. 8 The Game and the continued scaling of its digital content divisions. To reflect this positive outlook and strong liquidity, the shareholder return policy has been revised upward, increasing the target Dividend on Equity from 3% to 4%. This strategy signals a transition into a new growth phase where diversified IP solutions and global service expansions complement the established mobile gaming portfolio.
- Akatsuki Inc. achieved a 46% year-over-year increase in consolidated operating profit to ¥3,915 million for FY3/25, despite a 1% decline in total sales.
- The company maintains ¥33.3 billion in cash reserves to fund a ¥35 billion growth investment plan over the next three years, targeting M&A and next-generation game development.
- Shareholder returns are increasing as the target Dividend on Equity (DOE) has been raised from 3% to 4% due to strong liquidity and a positive outlook.
- The Comics and IP Solutions segments reached profitability, supported by the international launch of MANGA MIRAI and the expansion of the Slash Gift online lottery platform.
- Investment activities generated ¥2,840 million in proceeds during FY3/25, with further capital gains expected from the upcoming IPO of LIFE CREATE Co., Ltd. in early FY3/26.
AkatsukiMay 2025
Legal1 pages
Announcement of Revision of Dividend Forecast (Year-end Dividend)
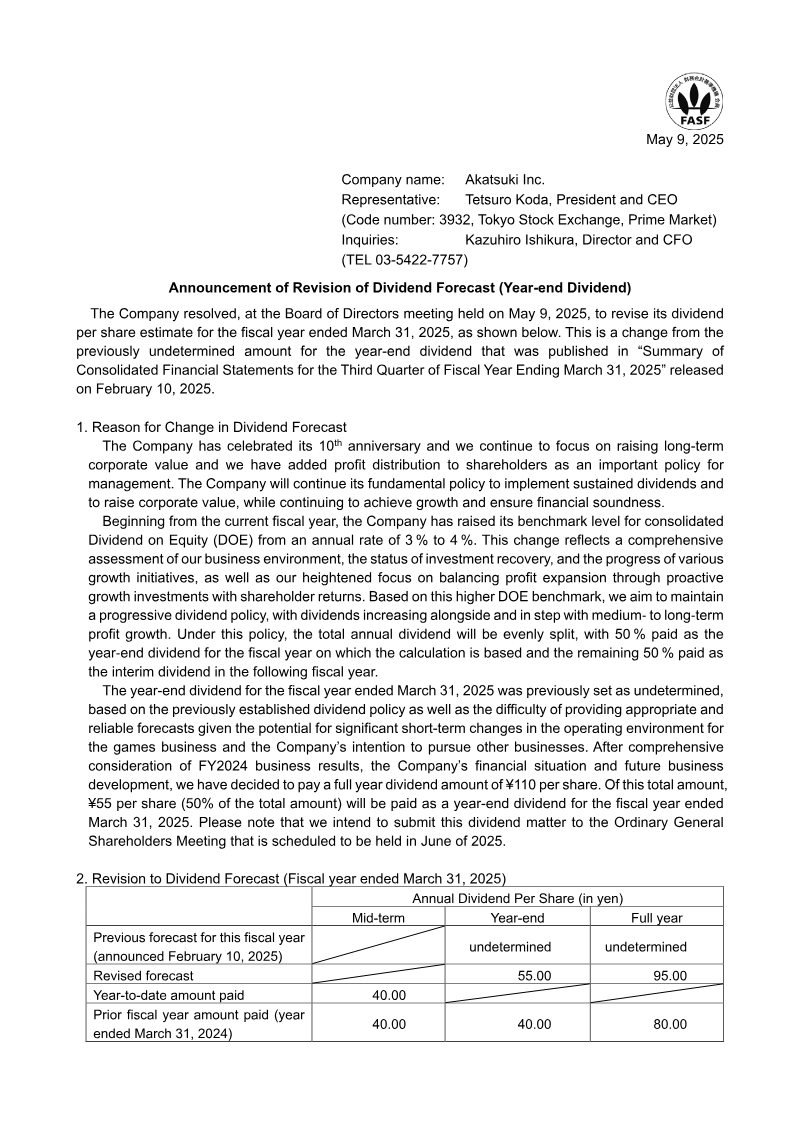
Akatsuki Inc. has revised its dividend forecast for the fiscal year ended March 31, 2025, transitioning from an undetermined status to a specific payout of 110 yen per share for the full year. This decision follows a strategic shift in the company’s shareholder return policy, specifically raising the benchmark for consolidated Dividend on Equity from 3% to 4%. This adjustment reflects a comprehensive assessment of the current business environment, investment recovery status, and the progress of various growth initiatives within the gaming and diversified business segments.
The revised policy establishes a progressive dividend framework aimed at balancing proactive growth investments with consistent profit distribution. Under this new structure, the total annual dividend is split evenly, with 50% paid as a year-end dividend for the current fiscal year and the remaining 50% distributed as an interim dividend in the following year. Consequently, the year-end dividend for the period ending March 31, 2025, is set at 55 yen per share. This represents a significant increase over the previous fiscal year’s total payout of 80 yen per share.
This financial update covers the Japanese market where Akatsuki Inc. is listed on the Tokyo Stock Exchange Prime Market. The board of directors resolved these changes on May 9, 2025, with the final dividend matter scheduled for submission at the Ordinary General Shareholders Meeting in June 2025. The move signals management's confidence in maintaining financial soundness while pursuing long-term corporate value and sustainable growth despite the inherent volatility of the short-term operating environment in the games industry.
- Akatsuki Inc. has set its full-year dividend for the fiscal year ending March 31, 2025, at 110 yen per share, up from 80 yen in the previous year.
- The company increased its consolidated Dividend on Equity (DOE) benchmark from 3% to 4% as part of a new shareholder return policy.
- The year-end dividend for the fiscal year ending March 31, 2025, is confirmed at 55 yen per share, representing half of the total annual payout.
- Under the new progressive dividend framework, future annual payouts will be split equally between a year-end dividend and an interim dividend in the following year.
- The board of directors approved these changes on May 9, 2025, with final ratification scheduled for the Ordinary General Shareholders Meeting in June 2025.
AkatsukiMay 2025
Financial2 pages
Announcement of Consolidated Results for Fiscal Year Ended March 31, 2025
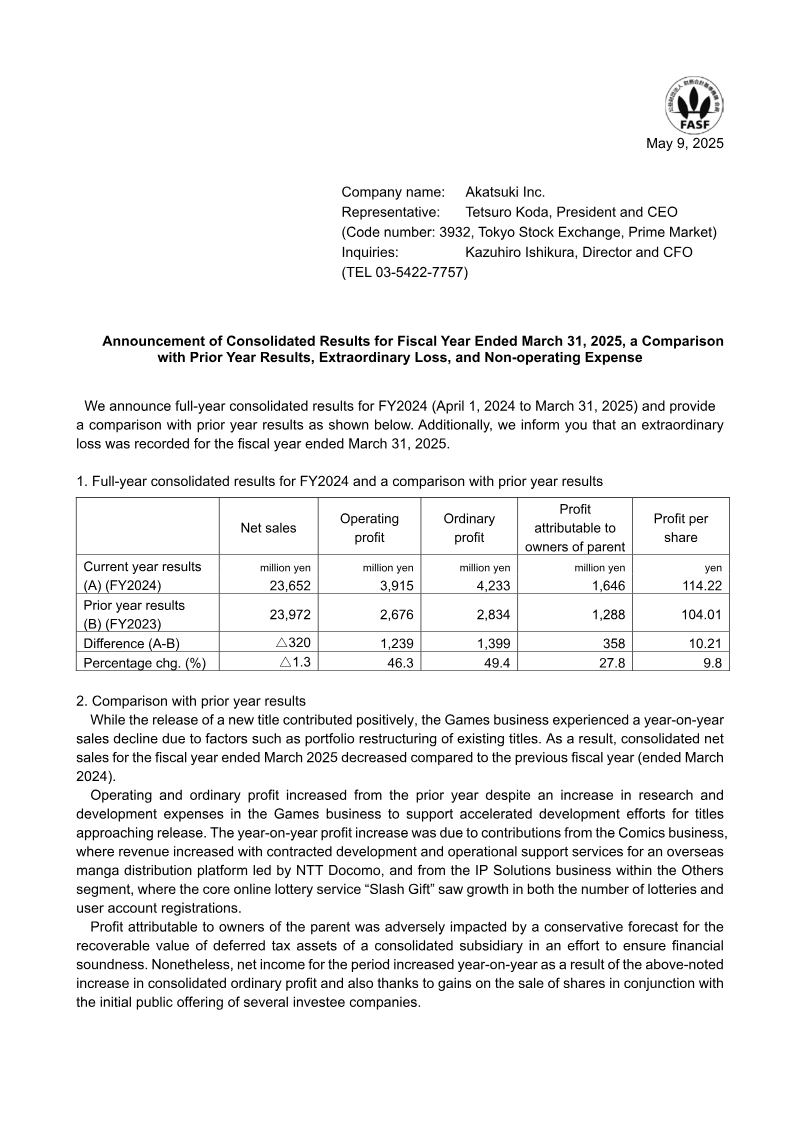
Akatsuki Inc. reported a significant increase in profitability for the fiscal year ended March 31, 2025, despite a slight contraction in overall revenue. Consolidated net sales reached 23,652 million yen, representing a 1.3% decrease from the previous year. This decline was primarily driven by portfolio restructuring within the Games business, which offset the positive contributions from new title releases. However, operating profit rose by 46.3% to 3,915 million yen, and ordinary profit grew by 49.4% to 4,233 million yen. Profit attributable to owners of the parent also saw a 27.8% increase, totaling 1,646 million yen, resulting in a profit per share of 114.22 yen.
The improved profit margins were largely attributed to growth in the Comics and IP Solutions segments. The Comics business benefited from development and operational support for an overseas manga platform, while the IP Solutions segment saw expansion in its online lottery service, Slash Gift. These gains successfully mitigated increased research and development expenses within the Games business. Furthermore, the company realized gains from the sale of shares following the initial public offerings of several investee companies, which bolstered net income.
To ensure long-term financial soundness, the company recorded several one-time charges. On a consolidated basis, an extraordinary loss of 593 million yen was recognized for the valuation of investment securities. On a non-consolidated basis, the company recorded a 5,776 million yen provision for doubtful accounts and a 2,454 million yen loss on the valuation of shares in affiliated companies. While these non-consolidated figures are substantial, they represent internal assessments of subsidiary loans and investments and had a minimal impact on the final consolidated financial results for the fiscal year.
- Akatsuki Inc. achieved significant profit growth for the fiscal year ended March 31, 2025, with operating profit rising 46.3% to 3,915 million yen and ordinary profit increasing 49.4% to 4,233 million yen.
- Consolidated net sales contracted by 1.3% to 23,652 million yen, as portfolio restructuring in the core Games business offset revenue gains from new title releases.
- Profit attributable to owners of the parent grew 27.8% to 1,646 million yen, supported by realized gains from the IPOs of several investee companies.
- Diversification into non-gaming sectors drove margin improvements, specifically through development support for an overseas manga platform in the Comics segment and the expansion of the 'Slash Gift' online lottery service in the IP Solutions segment.
- The company absorbed increased research and development expenses in the Games business by leveraging the profitability of its Comics and IP Solutions segments.
AkatsukiMay 2025
Financial3 pages
Consolidated Results Supplementary Information for Fiscal Year Ended in March of 2025
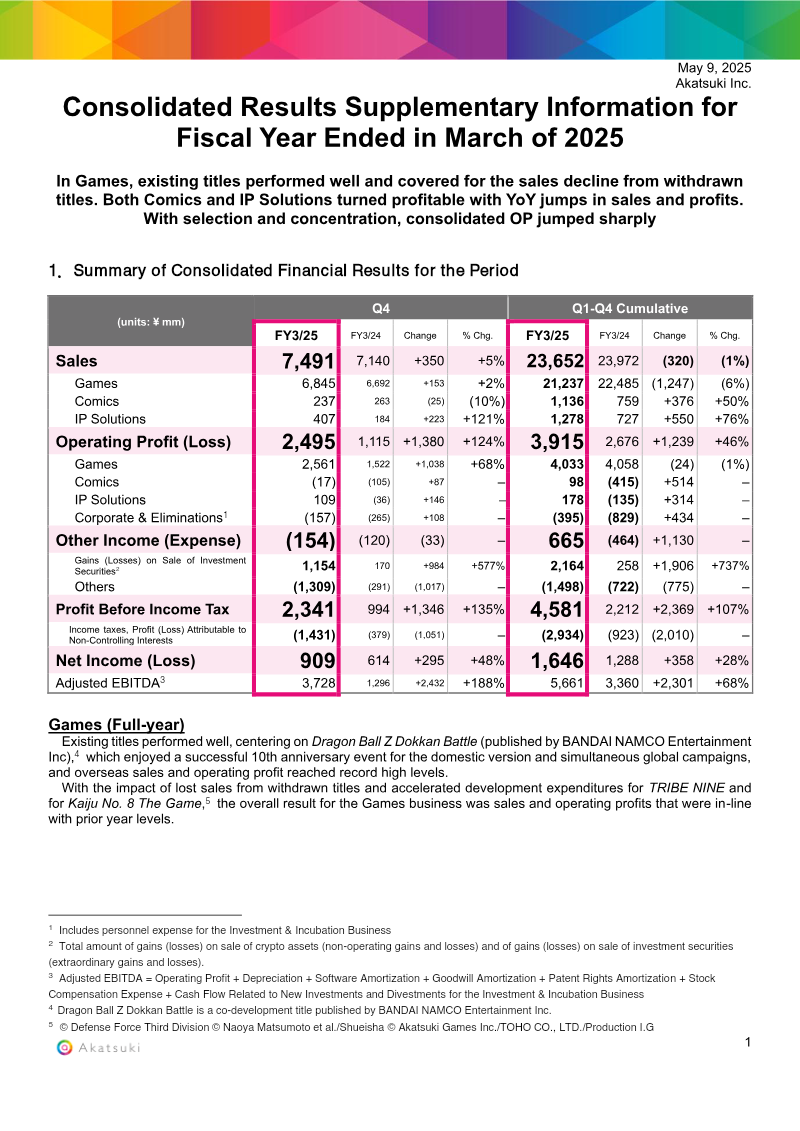
Akatsuki Inc. reported its consolidated financial results for the fiscal year ended March 2025, highlighting a period of strategic "selection and concentration" that led to a significant increase in profitability. While total annual sales remained relatively flat at ¥23.65 billion, a 1% decrease year-over-year, consolidated operating profit jumped 46% to ¥3.91 billion. This growth was driven by the stabilization of the core Games segment and the successful transition of the Comics and IP Solutions divisions into profitable entities.
The Games segment, which accounts for the vast majority of revenue, generated ¥21.24 billion in sales. Performance was bolstered by the 10th anniversary of Dragon Ball Z Dokkan Battle, which achieved record-high overseas sales and operating profit. These gains effectively offset revenue losses from withdrawn titles and increased research and development spending for upcoming projects like TRIBE NINE and Kaiju No. 8 The Game. Meanwhile, the Comics segment saw a 50% surge in annual sales to ¥1.14 billion, achieving full-year profitability due to strong external sales of original works, successful media dramatizations, and a strategic partnership with NTT Docomo for the MANGA MIRAI service in the United States.
Geographically, the results reflect a strong emphasis on global expansion, particularly through simultaneous worldwide game campaigns and international comic distribution. Financial data indicates a robust balance sheet with ¥33.3 billion in cash and total assets of ¥54.6 billion. The company also benefited from a substantial increase in gains from the sale of investment securities, which rose over 700% to ¥2.16 billion. Overall, the fiscal year concluded with a net income of ¥1.65 billion, representing a 28% increase over the previous year, supported by improved operational efficiency across all business pillars.
- Akatsuki Inc. achieved a 46% increase in consolidated operating profit to ¥3.91 billion for the fiscal year ended March 2025, despite a 1% decline in total sales to ¥23.65 billion.
- The Games segment generated ¥21.24 billion in revenue, anchored by the 10th anniversary of Dragon Ball Z Dokkan Battle, which reached record-high overseas sales and operating profit.
- The Comics segment reached full-year profitability with a 50% surge in annual sales to ¥1.14 billion, driven by media dramatizations and a partnership with NTT Docomo for the MANGA MIRAI service.
- Net income rose 28% year-over-year to ¥1.65 billion, bolstered by a 700% increase in gains from the sale of investment securities, which totaled ¥2.16 billion.
- The company maintains a strong liquidity position with ¥33.3 billion in cash and total assets of ¥54.6 billion.
AkatsukiMay 2025
Financial30 pages
Consolidated Financial Results for the Fiscal Year Ended March 31, 2025
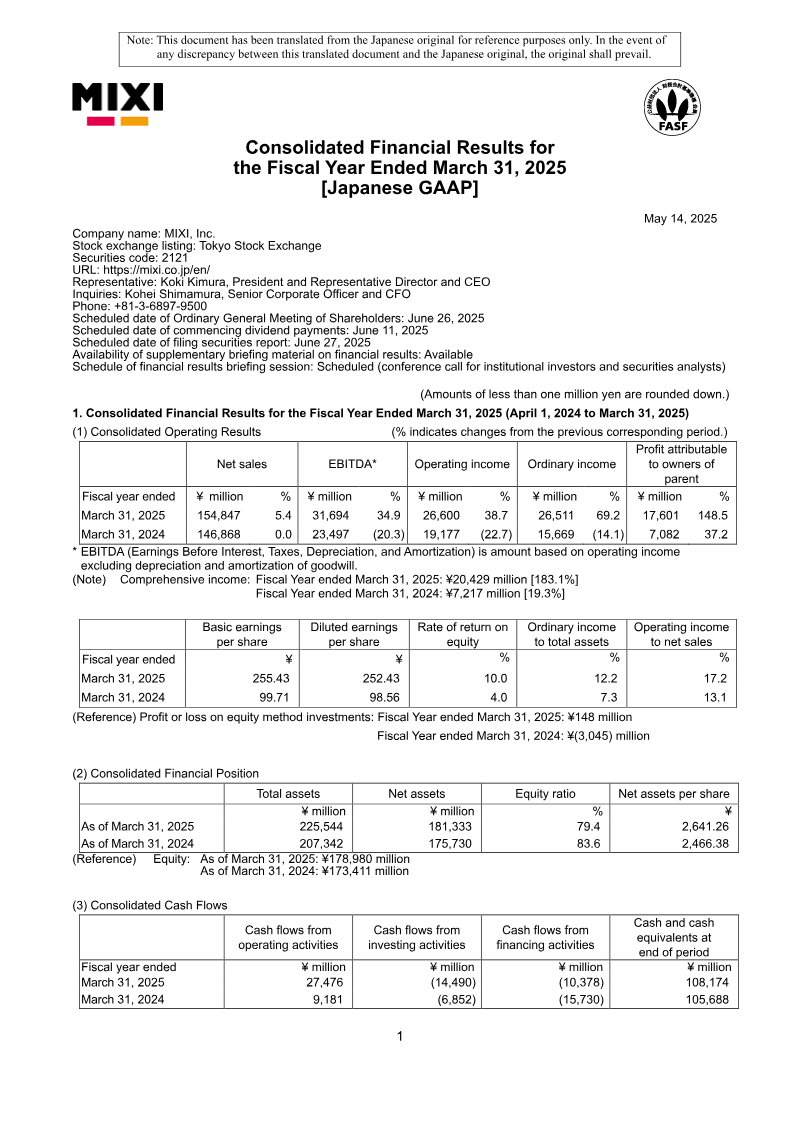
MIXI, Inc. achieved significant financial growth during the fiscal year ended March 31, 2025, characterized by a 5.4% increase in net sales to ¥154.8 billion and a 148.5% surge in profit attributable to owners, reaching ¥17.6 billion. While the core Digital Entertainment segment experienced a minor revenue contraction as engagement for the flagship title Monster Strike stabilized following its tenth anniversary, overall performance was bolstered by the Sports and Investment segments. Growth in these areas was primarily driven by increased betting service sales and strategic share divestments. This profitability was further supported by a ¥7 billion reduction in selling, general, and administrative expenses, specifically within advertising and settlement fees.
The financial position remains robust, with total assets expanding to ¥225.5 billion and net cash from operating activities nearly tripling to ¥27.5 billion. Despite this liquidity, the equity ratio saw a marginal decline to 79.4% due to treasury share acquisitions and new borrowings, including a ¥9 billion loan commitment for the subsidiary Chariloto Co., Ltd. The fiscal year was also marked by strategic organizational shifts, including the acquisition of picon, Inc. and the establishment of MIXI Australia, though these were tempered by a ¥1 billion loss resulting from improper transactions at a subsidiary.
Operations remain heavily concentrated in the Japanese market, which accounts for over 90% of net sales. Looking toward the fiscal year ending March 31, 2026, the outlook remains cautious with a projected 26.1% decline in profit despite stable sales forecasts of ¥155 billion. Future growth strategies prioritize expansion into AI technologies and the continued scaling of the Sports and Lifestyle segments. To maintain shareholder value, the company has committed to a ¥9.500 million treasury share repurchase program and the cancellation of 2.4 million shares, following a significant rise in basic earnings per share from ¥99.71 to ¥255.43.
- MIXI, Inc. reported a 148.5% surge in profit attributable to owners to ¥17.6 billion for the fiscal year ended March 31, 2025, alongside a 5.4% increase in net sales to ¥154.8 billion.
- Profitability was driven by a ¥7 billion reduction in selling, general, and administrative expenses and growth in the Sports and Investment segments, which offset a revenue contraction in the flagship Digital Entertainment segment.
- The company projects a cautious outlook for the fiscal year ending March 31, 2026, forecasting a 26.1% decline in profit despite maintaining stable net sales at ¥155 billion.
- Basic earnings per share rose significantly from ¥99.71 to ¥255.43, and the company has committed to a ¥9.5 billion treasury share repurchase program and the cancellation of 2.4 million shares.
- Net cash from operating activities nearly tripled to ¥27.5 billion, though the equity ratio declined marginally to 79.4% due to treasury share acquisitions and a ¥9 billion loan commitment for subsidiary Chariloto Co., Ltd.
MIXI, Inc.May 2025