Akatsuki
Game Co.41 documents
Documents
Report3 pages
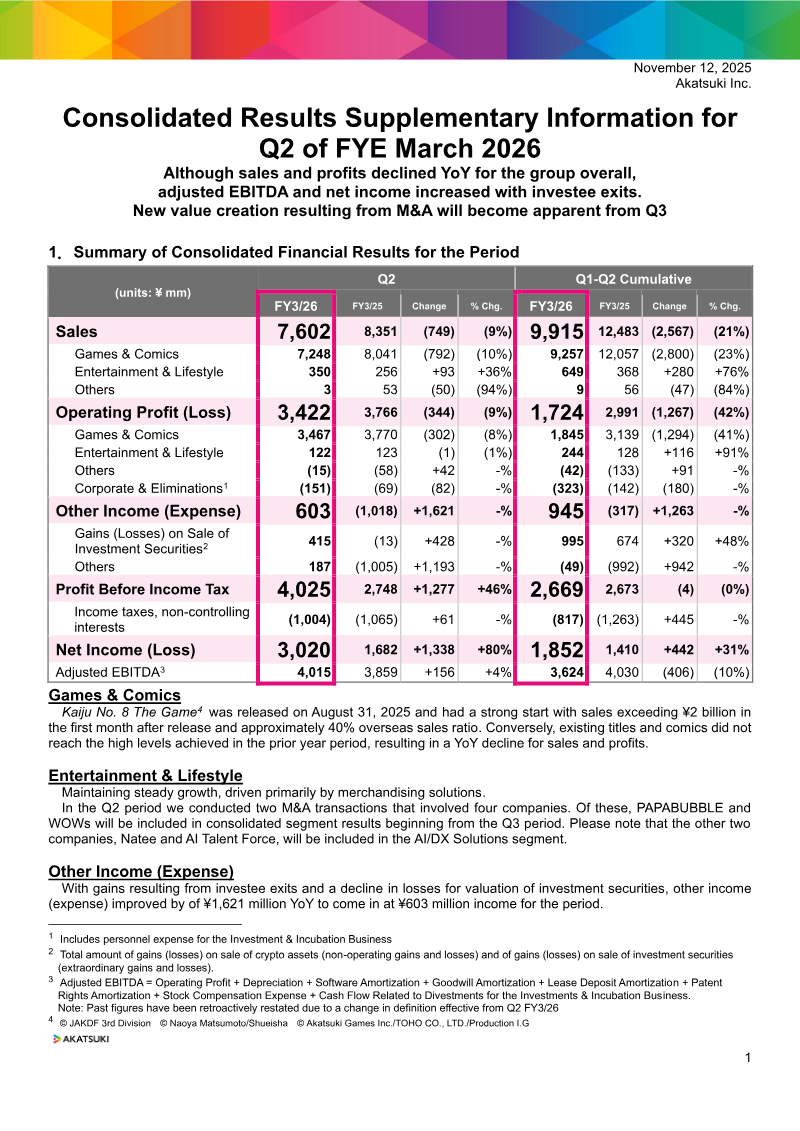
Consolidated Results Supplementary Information: Q2 of FYE March 2026
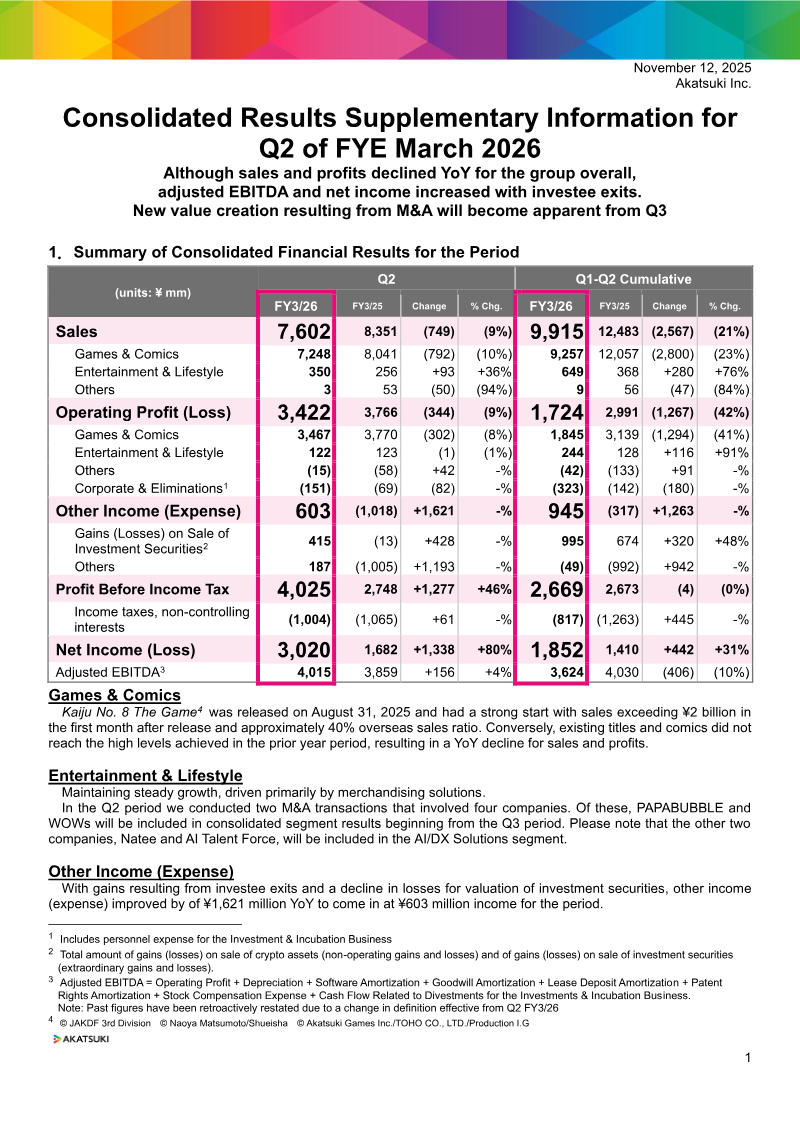
Akatsuki Inc. reported consolidated financial results for the second quarter of fiscal year ending March 2026, noting a 9 % decline in sales to ¥7,602 million and a 21 % drop in cumulative year‑to‑date sales of ¥9,915 million versus the prior year. The Games & Comics segment led the decline with a 10 % YoY fall to ¥7,248 million, while Entertainment & Lifestyle grew 36 % to ¥350 million, and the Others segment contracted sharply by 94 %. Operating profit fell 9 % to ¥3,422 million, largely due to weaker performance in the core Games & Comics unit; however, net income rose 80 % to ¥3,020 million, driven by gains from investee exits and reduced valuation losses on investment securities. Adjusted EBITDA increased modestly by 4 % to ¥4,015 million, reflecting a recovery in operating profitability after the release of new titles.
Key drivers include the launch of “Kaiju No. 8 The Game” on 31 August 2025, which generated over ¥2 billion in first‑month sales with a 40 % overseas share, partially offsetting declines from legacy titles. Two M&A transactions in Q2 added PAPABUBBLE and WOWs to the consolidated segment from Q3, while Natee and AI Talent Force will join the AI/DX Solutions segment. The company’s balance sheet shows a net asset base of ¥42,995 million and cash equivalents of ¥33,272 million, with current liabilities at ¥6,954 million.
Methodologically, the report aggregates data from all operating subsidiaries, restating prior figures to align with revised definitions effective Q2 FY3/26. The analysis covers Japan and international markets, focusing on the Games & Comics, Entertainment & Lifestyle, and AI/DX Solutions segments over a two‑quarter period.
- Akatsuki Inc. reported a 9% decline in quarterly sales to ¥7,602 million, primarily driven by a 10% YoY contraction in the core Games & Comics segment.
- Net income surged 80% to ¥3,020 million, bolstered by gains from investee exits and a reduction in valuation losses on investment securities despite lower operating profit.
- The launch of 'Kaiju No. 8 The Game' on 31 August 2025 generated over ¥2 billion in first-month sales, with 40% of revenue originating from overseas markets.
- Adjusted EBITDA increased by 4% to ¥4,015 million, signaling a recovery in operating profitability following the release of new titles.
- The company expanded its portfolio through Q2 M&A activity, acquiring PAPABUBBLE and WOWs for the Entertainment & Lifestyle segment, and Natee and AI Talent Force for the AI/DX Solutions segment.
+2
Akatsuki
Report11 pages
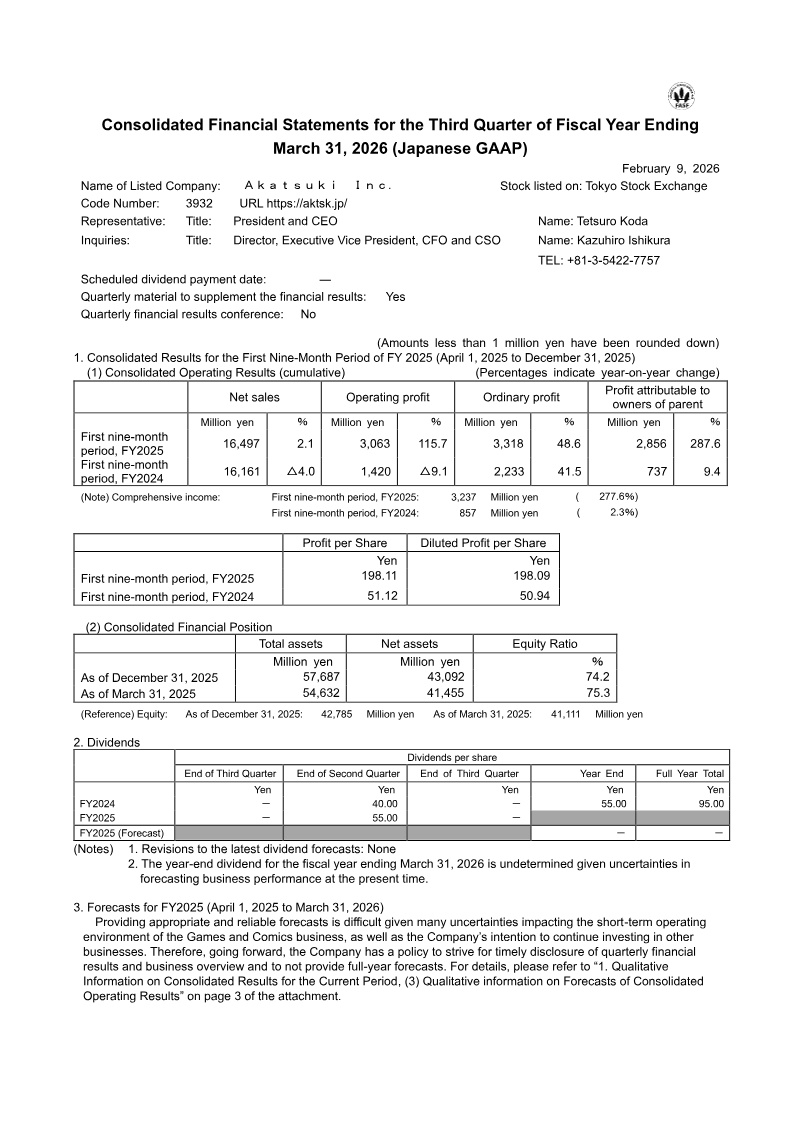
Consolidated Financial Statements for the Third Quarter of Fiscal Year Ending March 31, 2026
Akatsuki Inc. reports consolidated financial results for the first nine months of fiscal year 2025, ending December 31 2025. Net sales rose modestly by 2.1 % to ¥16,497 million, while operating profit surged 115.7 % to ¥3,063 million and ordinary profit increased 48.6 % to ¥3,318 million. Net profit attributable to parent shareholders climbed 287.6 % to ¥2,856 million, yielding diluted earnings per share of ¥198.11 versus ¥51.12 in the prior year. Total assets reached ¥57,687 million, up ¥3,054 million from March 31 2025, with net assets at ¥43,092 million and an equity ratio of 74.2 %. The company’s liquidity remained solid, with cash and deposits at ¥28,377 million and current liabilities down to ¥4,462 million.
Segment performance varied: the Games and Comics business posted a 5.3 % decline in sales but doubled operating profit through cost reductions; Entertainment and Lifestyle achieved a 76.1 % sales increase to ¥1,400 million but saw a modest profit decline; the newly reported AI/DX Solutions segment generated ¥600 million in sales and incurred a ¥112 million loss. The Others segment recorded a sharp 83.1 % sales drop and a ¥51 million loss.
The company added five subsidiaries to its consolidation scope, including CRAYON Inc. and PAPABUBBLE, while excluding Akatsuki Fukuoka after liquidation. No changes to accounting policies were noted. Forecasts for FY 2026 are withheld due to market uncertainties, and the company maintains a policy of not providing full‑year guidance.
- Akatsuki Inc. reported a significant surge in profitability for the first nine months of FY2025, with operating profit rising 115.7% to ¥3,063 million and net profit attributable to parent shareholders climbing 287.6% to ¥2,856 million.
- Net sales grew modestly by 2.1% to ¥16,497 million, while diluted earnings per share increased substantially to ¥198.11 compared to ¥51.12 in the prior year.
- The core Games and Comics business experienced a 5.3% decline in sales but successfully doubled its operating profit through effective cost-reduction measures.
- The Entertainment and Lifestyle segment achieved strong growth with a 76.1% sales increase to ¥1,400 million, though this was accompanied by a modest decline in profit.
- The company launched a new AI/DX Solutions segment, which generated ¥600 million in sales but incurred an operating loss of ¥112 million.
+1
Akatsuki
Report4 pages
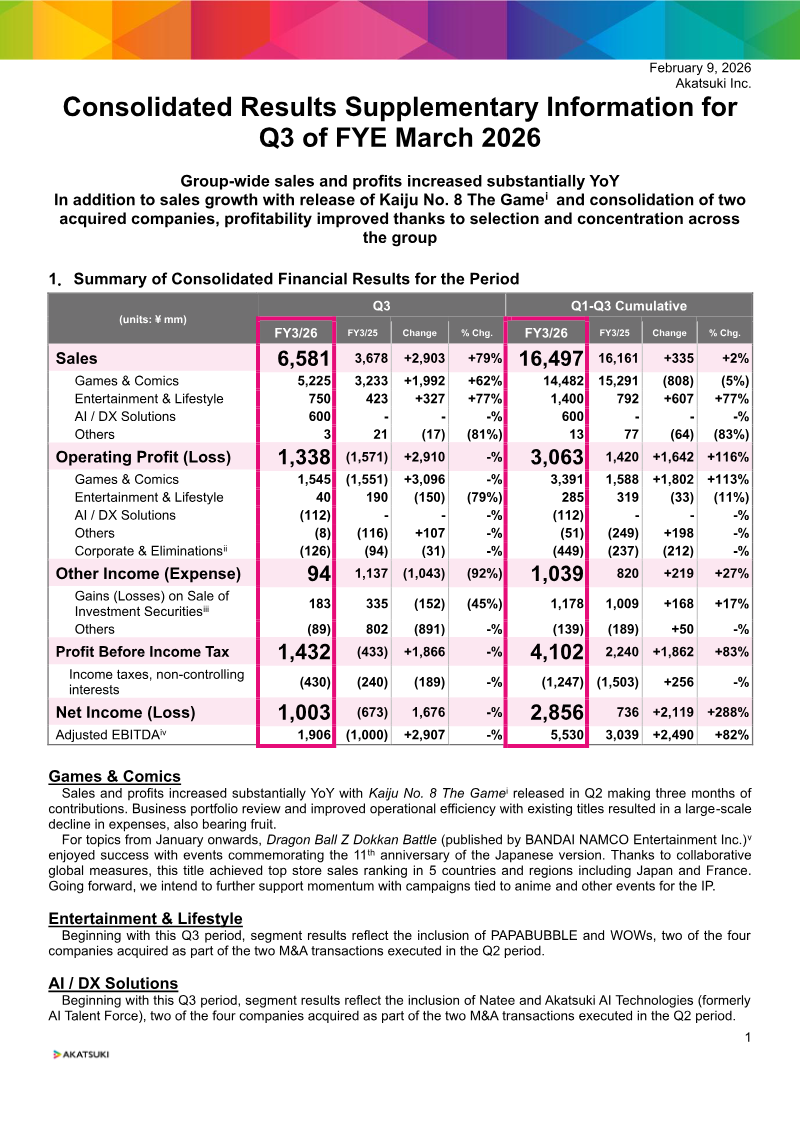
Consolidated Results Supplementary Information: Q3 FY3/26
Akatsuki Inc. reported a dramatic turnaround in Q3 FY3/26, with group‑wide sales surging 79 % YoY to ¥6,581 million and operating profit turning from a loss of ¥1,571 million to a gain of ¥1,338 million. The rebound is largely attributed to the Q2 release of “Kaiju No. 8 The Game,” which contributed three months’ worth of revenue, and the consolidation of two acquired entities that broadened the Games & Comics portfolio. Within this segment, sales climbed 62 % to ¥5,225 million and operating profit rose 113 % to ¥1,545 million. The Entertainment & Lifestyle segment also grew 77 % in sales to ¥750 million, driven by the inclusion of PAPABUBBLE and WOWs following Q2 acquisitions. AI/DX Solutions, newly integrated through Natee and Akatsuki AI Technologies, generated ¥600 million in sales but recorded a loss of ¥112 million.
Net income for the quarter reached ¥1,003 million, a 288 % increase from the prior year’s loss of ¥673 million. Adjusted EBITDA expanded 82 % to ¥1,906 million, reflecting strong operating performance and effective cost management. Cash balances rose to ¥33,266 million, while total assets stood at ¥57,687 million. The company’s balance sheet remained solid with net assets of ¥43,092 million and total liabilities of ¥14,595 million.
Methodologically, figures are presented in Japanese yen (millions) and include retroactive restatements from Q2 FY3/26 due to prior period errors. The report covers the entire Japanese market and global operations, focusing on Q3 FY3/26 with cumulative data for FY3/26 versus FY3/25.
- Akatsuki Inc. achieved a significant financial turnaround in Q3 FY3/26, reporting ¥6,581 million in group-wide sales (up 79% YoY) and an operating profit of ¥1,338 million, reversing a prior-year loss of ¥1,571 million.
- The primary growth driver was the Q2 release of 'Kaiju No. 8 The Game,' which contributed three months of revenue and helped boost Games & Comics segment sales by 62% to ¥5,225 million.
- Net income reached ¥1,003 million, a 288% increase compared to the ¥673 million loss recorded in the same period last year.
- The Entertainment & Lifestyle segment grew 77% to ¥750 million in sales, bolstered by the integration of newly acquired entities PAPABUBBLE and WOWs.
- The newly integrated AI/DX Solutions segment, comprising Natee and Akatsuki AI Technologies, generated ¥600 million in sales but incurred an operating loss of ¥112 million.
+1
Akatsuki
Financial36 pages
Consolidated Financial Results: FY3/26 – 3rd Quarter
Akatsuki Inc. achieved a significant financial turnaround in the third quarter of the fiscal year ending March 2026, characterized by a 79% year-over-year increase in consolidated sales to ¥6,581 million and a return to profitability with net income reaching ¥1,003 million. This performance was underpinned by a strategic reorganization into three core segments: Games & Comics, Entertainment & Lifestyle, and AI/DX Solutions. Growth was primarily catalyzed by the successful launch of Kaiju No. 8 The Game and the sustained operational efficiency of legacy titles such as Dragon Ball Z Dokkan Battle, which continues to drive revenue despite inherent seasonal fluctuations tied to major anniversary events.
The company’s operational structure has shifted toward a model of selection and concentration, marked by strategic M&A activity and a reduction in research and development spending as major projects moved into the operational phase. While personnel and outsourcing costs rose due to the integration of new subsidiaries like PAPABUBBLE and Akatsuki AI Technologies, the core gaming workforce saw a downward trend in permanent staff. Investment activities remain a vital component of the corporate value proposition, with ¥2.2 billion in proceeds realized from exits, including one IPO and two M&A transactions, during the cumulative nine-month period.
Future strategy focuses on global IP expansion and optimized capital allocation, supported by a strategic alliance and a commitment to shareholder returns. The company has established a plan to return between ¥10 billion and ¥15 billion to shareholders through fiscal year 2028, utilizing a progressive dividend policy. Despite a slight decrease in total assets to ¥57,687 million due to lower accounts receivable, the group maintains a robust financial position intended to support long-term growth across its diversified entertainment and technology portfolio.
- Akatsuki Inc. returned to profitability in Q3 FY3/26 with ¥1,003 million in net income and a 79% year-over-year sales increase to ¥6,581 million.
- The company committed to returning ¥10 billion to ¥15 billion to shareholders through FY2028 via a progressive dividend policy.
- Financial performance was driven by the launch of 'Kaiju No. 8 The Game' and sustained revenue from the legacy title 'Dragon Ball Z Dokkan Battle'.
- Investment activities generated ¥2.2 billion in proceeds over the first nine months of the fiscal year through one IPO and two M&A exits.
- Operational strategy has shifted toward 'selection and concentration,' resulting in reduced R&D spending and a decrease in permanent gaming staff despite rising costs from new subsidiary integrations like PAPABUBBLE.
+1
AkatsukiFeb 2026
Financial11 pages
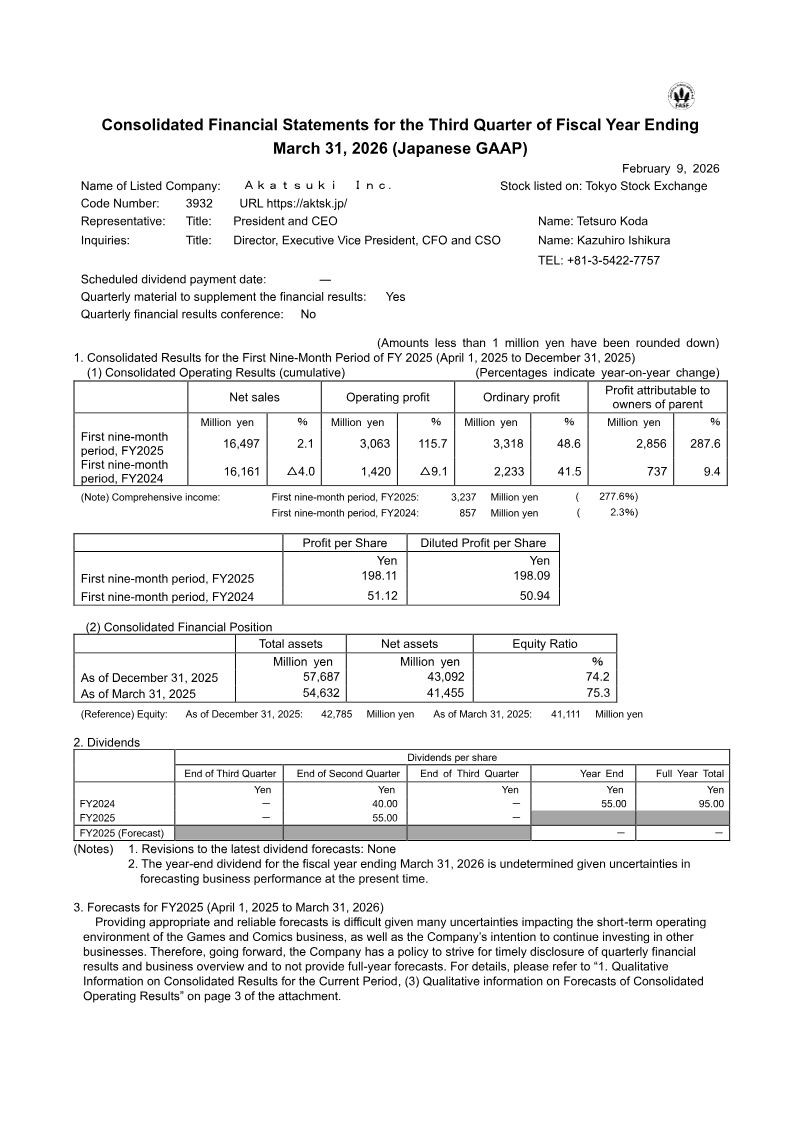
Consolidated Financial Statements for the Third Quarter of Fiscal Year Ending March 31, 2026 (Japanese GAAP)
Akatsuki Inc. demonstrated significant financial growth during the first nine months of the fiscal year ending March 31, 2026, characterized by a substantial increase in profitability despite modest revenue gains. Net sales rose 2.1% to ¥16,497 million, while profit attributable to owners surged by 287.6% to reach ¥2,856 million. This performance was primarily driven by enhanced operational efficiencies within the core Games and Comics segment and the successful market entry of new intellectual properties, most notably the August 2025 launch of Kaiju No. 8 The Game. Although the gaming division experienced a slight decline in top-line revenue, its segment profit more than doubled to ¥3,391 million, reflecting a strategic shift toward high-margin operations and the liquidation of underperforming subsidiaries.
The company expanded its operational scope through aggressive diversification and restructuring, establishing a new reporting framework consisting of Games and Comics, Entertainment and Lifestyle, and AI/DX Solutions. Strategic acquisitions played a pivotal role in this evolution, with the consolidation of entities such as CRAYON, Inc., PAPABUBBLE, Inc., and Natee Inc. contributing to a ¥3,880 million increase in goodwill. These investments bolstered the Entertainment and Lifestyle portfolio and provided the foundation for the new AI/DX Solutions segment, signaling a long-term commitment to integrating technology and lifestyle brands into the broader entertainment ecosystem.
Geographically focused on the Japanese market for the period ending December 31, 2025, the financial results indicate a robust balance sheet bolstered by diversified revenue streams, including the growth of the Slash Gift online lottery service. However, management has opted not to provide a full-year earnings forecast, citing inherent volatility in the gaming sector and the ongoing impact of heavy investment activities. This cautious outlook underscores a focus on long-term structural growth and IP development over short-term predictability.
- Akatsuki Inc. reported a 287.6% surge in profit attributable to owners to ¥2,856 million for the first nine months of the fiscal year ending March 31, 2026, despite a modest 2.1% increase in net sales to ¥16,497 million.
- The Games and Comics segment saw segment profit more than double to ¥3,391 million, driven by operational efficiencies, the liquidation of underperforming subsidiaries, and the August 2025 launch of Kaiju No. 8 The Game.
- The company underwent a major restructuring to establish three new reporting segments: Games and Comics, Entertainment and Lifestyle, and AI/DX Solutions.
- Strategic acquisitions including CRAYON, Inc., PAPABUBBLE, Inc., and Natee Inc. contributed to a ¥3,880 million increase in goodwill as part of a diversification strategy into lifestyle brands and technology integration.
- Management has declined to provide a full-year earnings forecast for the fiscal year ending March 31, 2026, citing gaming sector volatility and the impact of ongoing heavy investment activities.
AkatsukiFeb 2026
Financial4 pages
Consolidated Results Supplementary Information for Q3 of FYE March 2026
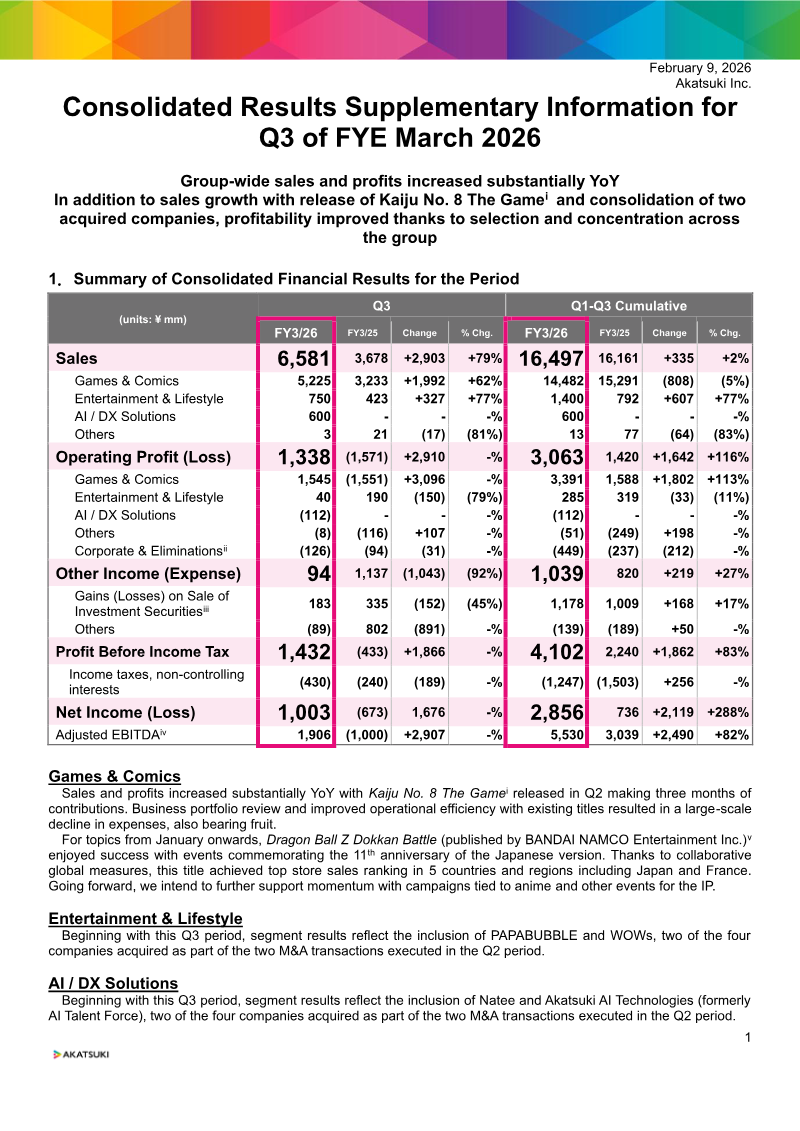
Akatsuki Inc. reported substantial year-over-year growth in sales and profitability for the third quarter of the fiscal year ending March 2026. Consolidated sales for the quarter reached ¥6,581 million, a 79% increase compared to the same period in the previous year, while operating profit rose to ¥1,338 million, reversing a loss from the prior year. This financial improvement was driven by the successful release of Kaiju No. 8 The Game, the continued performance of Dragon Ball Z Dokkan Battle, and the strategic consolidation of four acquired companies.
The Games & Comics segment remains the primary revenue driver, contributing ¥5,225 million in quarterly sales. Profitability in this sector improved significantly due to a rigorous business portfolio review and enhanced operational efficiency for existing titles, which led to a large-scale reduction in expenses. Beyond gaming, the company expanded its scope through M&A activity, establishing a new AI / DX Solutions segment and bolstering the Entertainment & Lifestyle division. These new segments reflect the inclusion of acquired entities such as PAPABUBBLE, WOWs, Natee, and Akatsuki AI Technologies.
Geographically, the company noted strong global performance for its legacy titles, specifically reaching top store rankings in five regions, including Japan and France. Financial data indicates a robust balance sheet with cash and equivalents totaling ¥33,266 million. The methodology for these results involves consolidated accounting of various subsidiaries and the use of Adjusted EBITDA to measure performance, which accounts for depreciation, amortization, and investment-related cash flows. Overall, the findings suggest a successful transition toward a more diversified and cost-efficient corporate structure.
- Akatsuki Inc. reported Q3 FYE March 2026 sales of ¥6,581 million, a 79% year-over-year increase, with operating profit reaching ¥1,338 million compared to a prior-year loss.
- The Games & Comics segment generated ¥5,225 million in quarterly revenue, bolstered by the launch of 'Kaiju No. 8 The Game' and the sustained performance of 'Dragon Ball Z Dokkan Battle'.
- Profitability improved significantly through a rigorous business portfolio review and large-scale expense reductions across existing gaming titles.
- The company expanded its corporate structure through the acquisition of four entities—PAPABUBBLE, WOWs, Natee, and Akatsuki AI Technologies—leading to the creation of new AI / DX Solutions and Entertainment & Lifestyle segments.
- Legacy gaming titles achieved top store rankings in five global regions, including Japan and France.
+1
AkatsukiFeb 2026
Financial35 pages
Consolidated Financial Results: FY3/26 Q2
Akatsuki Inc. achieved consolidated sales of ¥7,602 million and a net income of ¥3,020 million during the second quarter of the fiscal year ending March 2026, representing an 80% year-over-year increase in profitability. This financial performance was primarily bolstered by strategic investment exits and the successful launch of Kaiju No. 8 The Game, which secured over 5 million downloads and generated more than ¥2 billion in its debut month. While the core Games & Comics segment experienced a 10% decline in sales compared to the previous year’s high benchmarks, the company maintained strong operational momentum through established titles like Dragon Ball Z Dokkan Battle and a significant 40% overseas sales ratio for new releases.
The strategic focus has shifted toward a reorganized three-segment business model designed to diversify revenue streams beyond traditional mobile gaming. This evolution includes the expansion of the Entertainment & Lifestyle pillar, highlighted by the acquisition of the candy brand PAPABUBBLE, and the establishment of an AI/DX Solutions division. Total assets rose to ¥59.4 billion as a result of aggressive M&A activity, which added substantial goodwill and software assets to the balance sheet despite a corresponding decrease in cash equivalents used for these acquisitions.
Human capital remains a priority, with permanent staff increasing to 561 to support new business ventures, even as the core gaming division saw a slight contraction in headcount. The company is positioning itself for long-term growth by leveraging investment exit gains, which totaled approximately ¥400 million in the second quarter, to fund its transition into a broader entertainment conglomerate. These structural changes and recent product successes suggest a pivot toward a more diversified portfolio intended to mitigate the volatility of the gaming market while capitalizing on global intellectual property.
- Akatsuki Inc. reported Q2 FY3/26 net income of ¥3,020 million, marking an 80% year-over-year increase in profitability driven by strategic investment exits and the launch of Kaiju No. 8 The Game.
- Kaiju No. 8 The Game generated over ¥2 billion in its debut month and surpassed 5 million downloads, helping to offset a 10% year-over-year sales decline in the core Games & Comics segment.
- The company is aggressively diversifying beyond mobile gaming into an entertainment conglomerate, evidenced by the acquisition of candy brand PAPABUBBLE and the creation of an AI/DX Solutions division.
- Total assets grew to ¥59.4 billion due to M&A activity, though cash equivalents decreased as capital was deployed to acquire goodwill and software assets.
- New product releases achieved a 40% overseas sales ratio, while established titles like Dragon Ball Z Dokkan Battle continue to provide stable operational momentum.
AkatsukiNov 2025
Financial3 pages
Consolidated Results Supplementary Information for Q2 of FYE March 2026
Akatsuki Inc. reported its consolidated financial results for the second quarter of the fiscal year ending March 2026, highlighting a period of strategic transition. While overall group sales and operating profits saw year-over-year declines, net income rose by 80% to ¥3,020 million, and adjusted EBITDA increased by 4% to ¥4,015 million. These gains were primarily driven by successful investee exits and a significant reduction in valuation losses for investment securities, which improved other income by ¥1,621 million compared to the previous year.
The Games & Comics segment remains the primary revenue driver, though it experienced a 10% decline in quarterly sales to ¥7,248 million. This was attributed to the natural cooling of existing titles and comics compared to a high-performance prior year. However, the August 2025 launch of Kaiju No. 8 The Game provided a significant boost, generating over ¥2 billion in its first month with a 40% overseas sales ratio. Conversely, the Entertainment & Lifestyle segment grew 36% year-over-year, supported by merchandising solutions and recent M&A activity.
The financial outlook emphasizes future value creation through recent acquisitions, including PAPABUBBLE and WOWs, which will be integrated into consolidated results starting in the third quarter. Additionally, the company is expanding into AI and DX solutions through the acquisition of Natee and AI Talent Force. Total assets increased to ¥59,400 million by the end of the second quarter, reflecting higher fixed assets following these strategic investments. Operating expenses shifted as R&D costs for new titles were reclassified to cost of goods sold upon release, alongside a one-time reimbursement of R&D expenses for Hyke: Northern Light(s).
- Akatsuki Inc. reported an 80% increase in net income to ¥3,020 million for Q2 FYE March 2026, largely driven by successful investee exits and reduced valuation losses on investment securities.
- The Games & Comics segment, the company's primary revenue driver, saw a 10% year-over-year sales decline to ¥7,248 million due to the cooling of existing titles.
- The August 2025 launch of 'Kaiju No. 8 The Game' generated over ¥2 billion in its first month, with 40% of those sales coming from overseas markets.
- The Entertainment & Lifestyle segment grew 36% year-over-year, bolstered by merchandising solutions and recent M&A activity.
- The company is expanding its portfolio through the acquisition of PAPABUBBLE, WOWs, Natee, and AI Talent Force, which will be integrated into consolidated results starting in Q3.
+1
AkatsukiNov 2025
Financial12 pages
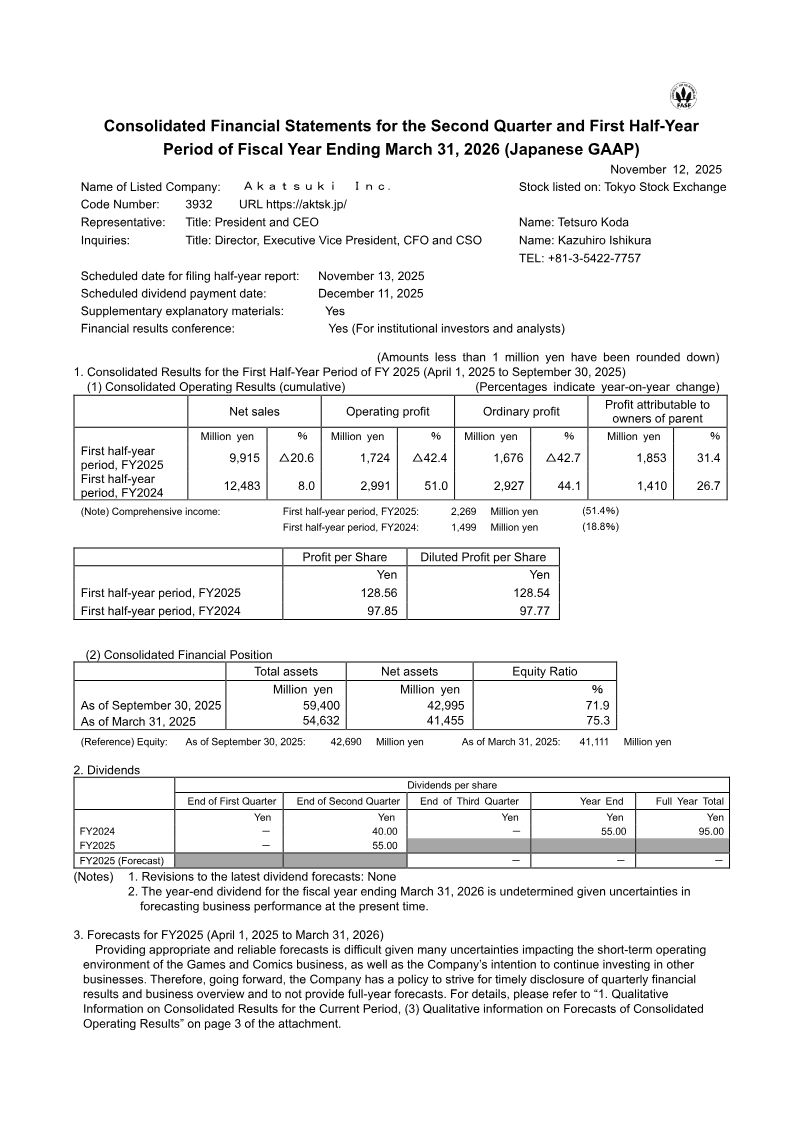
Consolidated Financial Statements for the Second Quarter and First Half-Year Period of Fiscal Year Ending March 31, 2026 (Japanese GAAP)
Akatsuki Inc. experienced a period of strategic transition during the first half of the fiscal year ending March 31, 2025, characterized by a contraction in core gaming revenue alongside aggressive expansion into new business segments. Net sales declined 20.6% year-on-year to ¥9,915 million, while operating profit fell 42.4% to ¥1,724 million. This downturn was primarily driven by a reactionary decline in the performance of existing game titles. However, net income attributable to owners rose 31.4% to ¥1,853 million, bolstered by the successful launch of Kaiju No. 8 The Game and the growing contribution of the Entertainment and Lifestyle segment.
The financial structure underwent significant shifts as the company expanded its consolidation scope to include six new entities, most notably CRAYON Inc., Natee, Inc., and PAPABUBBLE JAPAN HD, Inc. These acquisitions, totaling several billion yen, resulted in a provisional goodwill increase of ¥3,352 million and a rise in long-term borrowings to ¥6,763 million. To reflect this evolving business model, the company restructured its reporting segments, merging Games and Comics while elevating the Entertainment and Lifestyle division due to its increased materiality and growth potential.
Despite the growth in net income and the expansion of the IP-driven lifestyle business, management has opted not to provide consolidated operating forecasts for the remainder of the fiscal year. This decision stems from high levels of uncertainty within the Games and Comic sectors, where market volatility makes precise projections difficult. The current strategy focuses on balancing the stabilization of the core gaming portfolio with the integration of newly acquired subsidiaries to diversify revenue streams beyond traditional digital entertainment.
- Akatsuki Inc. reported a 20.6% year-on-year decline in net sales to ¥9,915 million and a 42.4% drop in operating profit to ¥1,724 million, driven by the underperformance of existing game titles.
- Net income attributable to owners increased by 31.4% to ¥1,853 million, supported by the launch of 'Kaiju No. 8 The Game' and growth in the Entertainment and Lifestyle segment.
- The company expanded its consolidation scope by acquiring six new entities, including CRAYON Inc., Natee, Inc., and PAPABUBBLE JAPAN HD, Inc., resulting in a ¥3,352 million increase in goodwill.
- Long-term borrowings rose to ¥6,763 million to fund the recent acquisitions and strategic shift toward diversifying revenue beyond traditional digital entertainment.
- Management declined to provide consolidated operating forecasts for the remainder of the fiscal year ending March 31, 2026, citing high market volatility and uncertainty in the Games and Comic sectors.
AkatsukiNov 2025
Presentation37 pages
Consolidated Financial Results Briefing Materials: FY3/26 Q1
Akatsuki Inc. experienced a challenging start to the fiscal year ending March 2026, reporting a 44% year-over-year decline in consolidated sales to ¥2,313 million and an operating loss of ¥1,698 million for the first quarter. This downturn was primarily driven by a 52% revenue contraction in the core Games business, resulting from a reactionary fall following a strong prior quarter, strategic title withdrawals, and heightened development costs associated with the upcoming global launch of Kaiju No. 8 The Game. While total operating expenses decreased by 18% due to a 42% reduction in research and development spending and a streamlined portfolio, these savings were insufficient to offset the revenue decline and typical seasonal fluctuations.
Despite the volatility in gaming, the IP Solutions and Comics segments demonstrated robust growth. IP Solutions sales surged 168% to ¥298 million, bolstered by the consolidation of CRAYON, Inc. and the rapid expansion of the Slash Gift online lottery service. Simultaneously, the Comics segment broadened its international footprint through the MANGA MIRAI service in the United States, integrating high-profile titles such as One Piece and Naruto. The company also accelerated its expansion into new business domains through the full acquisition of the creator agency Natee Co., Ltd. and realized ¥1.2 billion in investment proceeds following the IPO of LIFE CREATE Co., Ltd.
The financial position remains liquid with ¥33.2 billion in cash and deposits, providing a stable foundation for ongoing strategic investments despite a slight decrease in total assets to ¥50.9 billion. The current fiscal trajectory reflects a transition period as the company rebalances its portfolio, shifting focus toward high-potential global IP launches and diversified digital entertainment services to mitigate the inherent cyclicality of the mobile gaming market.
- Akatsuki Inc. reported a 44% year-over-year decline in consolidated sales to ¥2,313 million and an operating loss of ¥1,698 million for Q1 FY3/26.
- The core Games business revenue contracted by 52% due to title withdrawals, a reactionary decline from the previous quarter, and high development costs for the upcoming 'Kaiju No. 8 The Game'.
- IP Solutions revenue grew 168% to ¥298 million, driven by the consolidation of CRAYON, Inc. and the expansion of the Slash Gift online lottery service.
- The company maintains a liquid financial position with ¥33.2 billion in cash and deposits, despite total assets decreasing to ¥50.9 billion.
- Operating expenses fell by 18% overall, supported by a 42% reduction in research and development spending and a streamlined game portfolio.
+1
AkatsukiAug 2025
Financial11 pages
Consolidated Financial Statements for the First Quarter of Fiscal Year Ending March 31, 2026 (Japanese GAAP)
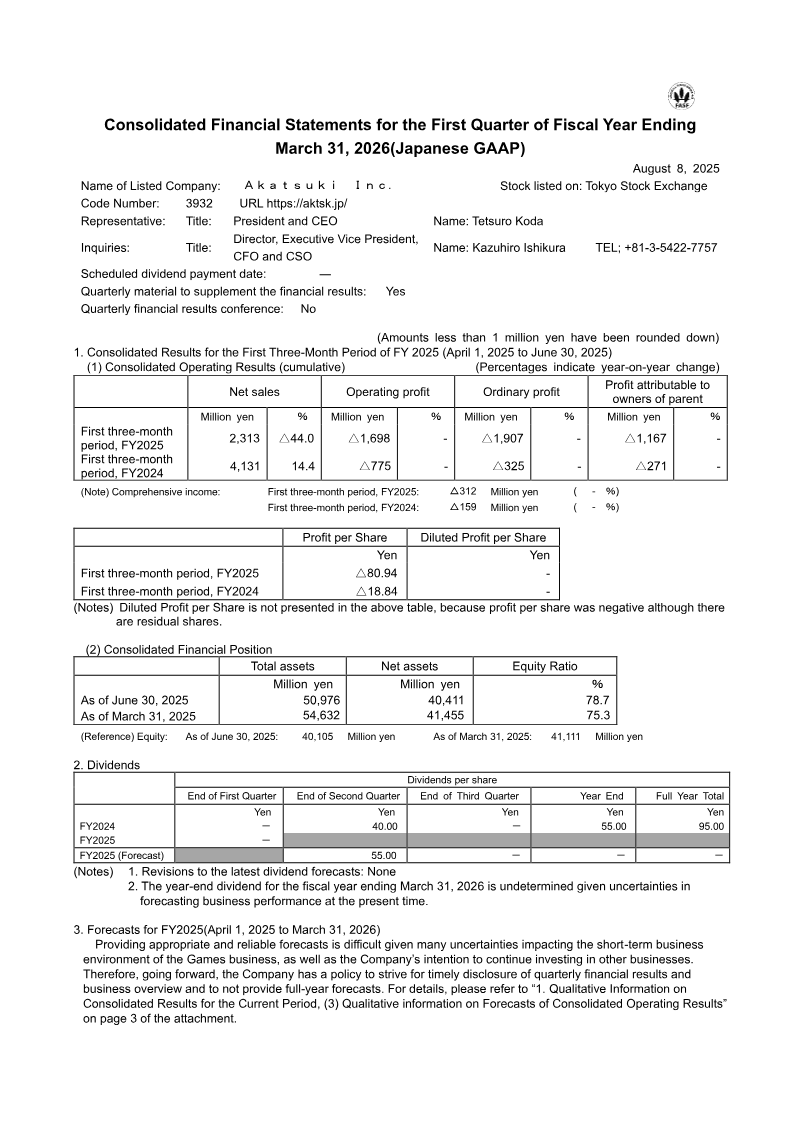
Akatsuki Inc. experienced a significant downturn in financial performance during the first quarter of the fiscal year ending March 31, 2026, characterized by a 44.0% year-on-year decline in net sales to ¥2,313 million. This contraction led to a widened operating loss of ¥1,698 million and a net loss of ¥1,167 million. The primary driver of this decline was the Games business, where revenue plummeted 52.3% to ¥1,782 million. This segment’s performance was impacted by a strategic portfolio review and a transition period for flagship titles such as Dragon Ball Z Dokkan Battle, resulting in a segment loss of ¥1,643 million. Furthermore, the company recorded a ¥103 million extraordinary loss stemming from the discontinuation of a specific game title and subsequent organizational restructuring.
Despite these challenges in the core gaming sector, the newly reclassified IP Solutions segment emerged as a growth driver, with revenue increasing 167.2% to ¥298 million and achieving a segment profit of ¥122 million following the consolidation of CRAYON, Inc. Conversely, the Comics business saw an 18.3% revenue decline, though it successfully returned to a modest segment profit of ¥20 million. Total assets decreased by ¥3,656 million during the period, settling at ¥50,976 million, yet the company maintains a robust financial foundation with a high equity ratio of 78.7%.
The current strategic trajectory involves a pivot toward large-scale, 3D multi-device projects designed for global markets. This shift aims to stabilize the Games segment by moving beyond traditional mobile constraints while leveraging the momentum found in IP-driven solutions. While the immediate financial results reflect the costs of reorganization and the volatility of existing game lifecycles, the emphasis remains on long-term scalability and the diversification of revenue streams across the broader entertainment landscape.
- Akatsuki Inc. reported a 44.0% year-on-year decline in net sales to ¥2,313 million for Q1 of the fiscal year ending March 31, 2026, resulting in a net loss of ¥1,167 million.
- The Games business segment drove the downturn with a 52.3% revenue drop to ¥1,782 million and a segment loss of ¥1,643 million, largely due to a strategic portfolio review and transitions for flagship titles like Dragon Ball Z Dokkan Battle.
- The company recorded a ¥103 million extraordinary loss attributed to the discontinuation of a specific game title and associated organizational restructuring.
- The IP Solutions segment emerged as a growth driver, increasing revenue by 167.2% to ¥298 million and generating a segment profit of ¥122 million following the consolidation of CRAYON, Inc.
- The Comics business returned to a segment profit of ¥20 million despite an 18.3% year-on-year decline in revenue.
+1
AkatsukiAug 2025
Legal15 pages
Notice of the 15th Annual General Meeting of Shareholders
Akatsuki Inc. is transitioning its corporate governance and shareholder engagement strategies for the fiscal year ending March 31, 2025, by adopting a virtual-only format for its 15th Annual General Meeting. This shift emphasizes digital accessibility, allowing shareholders to participate via live online voting and a structured preliminary questioning system. The company’s strategic focus centers on balancing shareholder returns with long-term stability, evidenced by a proposed year-end dividend of ¥55 per share. This brings the total annual dividend to ¥95, marking a formal policy shift toward a 4% consolidated dividend on equity rate to ensure consistent payouts.
The leadership structure is undergoing a formal renewal as the terms for the current board expire. The proposed slate of four directors and one auditor combines internal continuity with external oversight. CEO Tetsuro Koda and Kazuhiro Ishikura represent the core executive leadership, while the nomination of outside directors Hisashi Katsuya and Tetsuya Mizuguchi introduces specialized expertise in startup scaling and global game development. These appointments are designed to provide neutral, strategic advice while maintaining a robust governance framework supported by a detailed director skill matrix and independent officer oversight.
To mitigate corporate risk and ensure operational resilience, the organization has implemented comprehensive contingency plans for its digital infrastructure and maintains liability insurance for its officers. This governance model aims to align the interests of the board with those of the shareholders while navigating the complexities of the global gaming and entertainment industries. By integrating legal, financial, and industry-specific expertise into its leadership tier, the company seeks to strengthen its oversight capabilities and maintain a competitive trajectory in an increasingly digital corporate environment.
- Akatsuki Inc. has established a new dividend policy targeting a 4% consolidated dividend on equity, resulting in a total annual dividend of ¥95 per share for the fiscal year ending March 31, 2025.
- The company is transitioning to a virtual-only format for its 15th Annual General Meeting to prioritize digital accessibility through live online voting and a structured preliminary questioning system.
- The proposed board renewal includes the appointment of outside directors Hisashi Katsuya and Tetsuya Mizuguchi, who bring specialized expertise in startup scaling and global game development to the leadership team.
- The board of directors slate consists of four directors and one auditor, featuring CEO Tetsuro Koda and Kazuhiro Ishikura to balance internal continuity with external oversight.
- To enhance corporate governance, the company has implemented a formal director skill matrix and maintains liability insurance for its officers to mitigate operational and digital infrastructure risks.
AkatsukiJun 2025