1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial report NEXON Co.
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial reportNEXON Co.
Distilling the key insights…
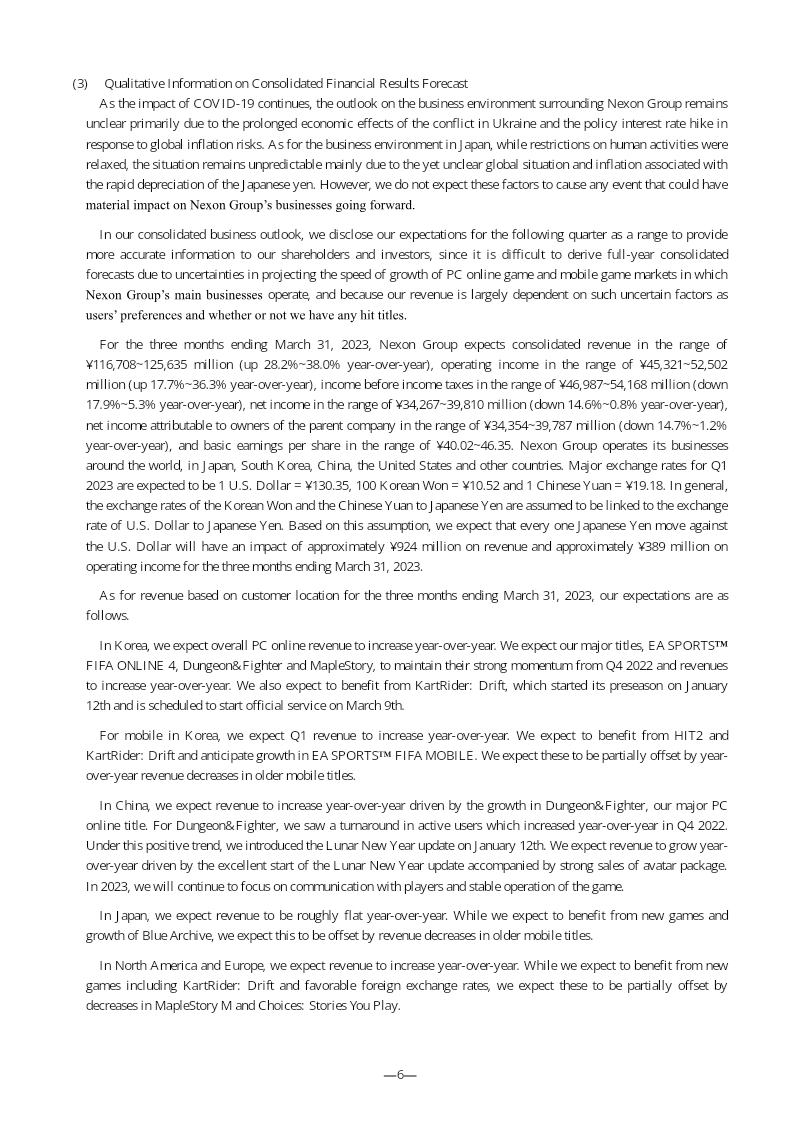
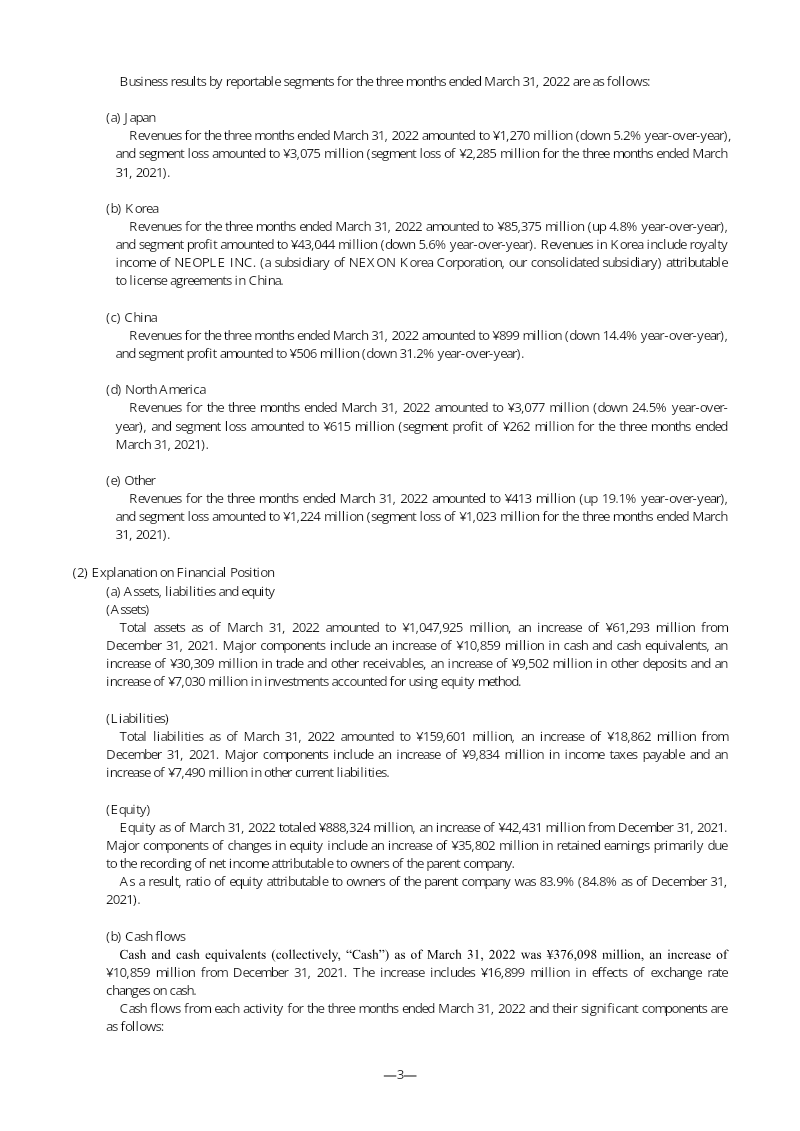
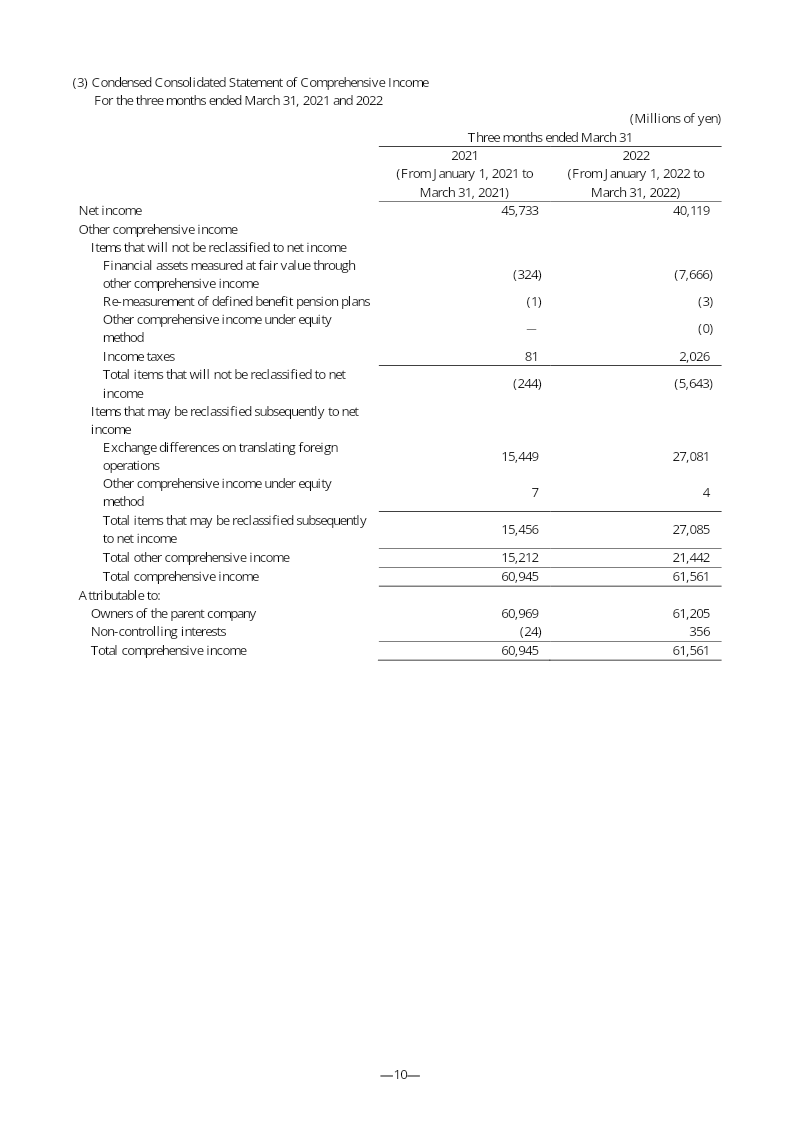
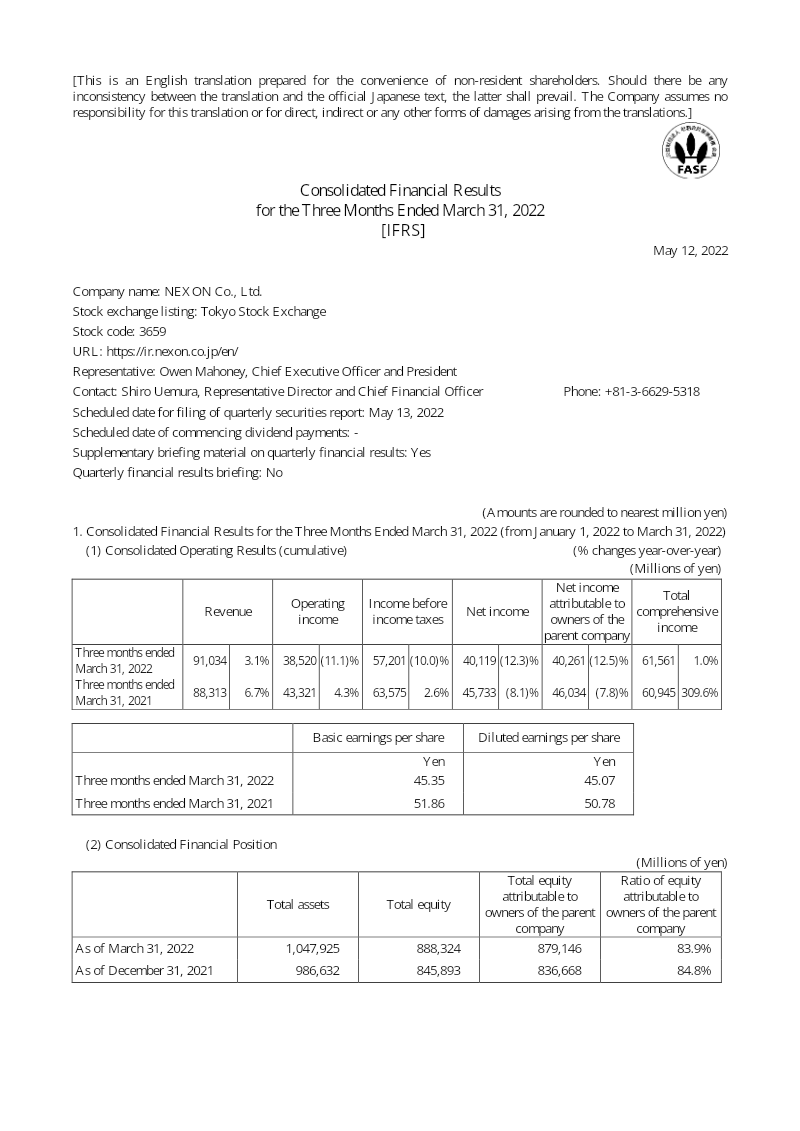
Nexon’s financial performance for the first quarter of 2022 reflects a period of strategic expansion and capital reallocation. The company achieved a 3.1% year-over-year revenue increase, reaching ¥91,034 million, primarily fueled by robust market activity in China and the successful domestic launch of Dungeon&Fighter Mobile in Korea. Despite this top-line growth, net income attributable to the parent company declined by 12.5% to ¥40,261 million. This contraction in profitability is largely attributed to rising operating expenses, including elevated personnel costs and royalty obligations, alongside a decrease in basic earnings per share from ¥51.86 to ¥45.35.
The company maintains a highly stable financial foundation, characterized by total assets of ¥1,047,925 million and a strong equity ratio of 83.9%. Cash flow management during this period prioritized shareholder returns and strategic investments over capital expenditure. Financing activities saw a significant outflow of ¥22,611 million, driven by aggressive treasury stock repurchases totaling ¥17,230 million and dividend payments of ¥4,459 million. Conversely, investing activities saw a sharp reduction in cash usage, as the company shifted its focus toward long-term equity commitments, including significant capital allocations to Smash Capital Fund I L.P. and Brothers International, LLC.
Operating income was bolstered by non-operating gains, specifically a ¥9,298 million windfall from the divestment of shares in Six Waves Inc. While the company continues to utilize complex valuation models for its ¥208.5 billion in financial assets, the overall fiscal strategy remains centered on balancing the monetization of core franchises with deliberate investments in external growth funds. By maintaining high liquidity and prioritizing shareholder value through buybacks and dividends, the company is positioning itself to navigate rising operational costs while sustaining its long-term market presence across global gaming segments.
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
NEXON Co. · 2026
Stillfront · 2023