FinancialNazara Technologies
Nazara Technologies Investor Presentation: Quarter Ended December 31, 2024
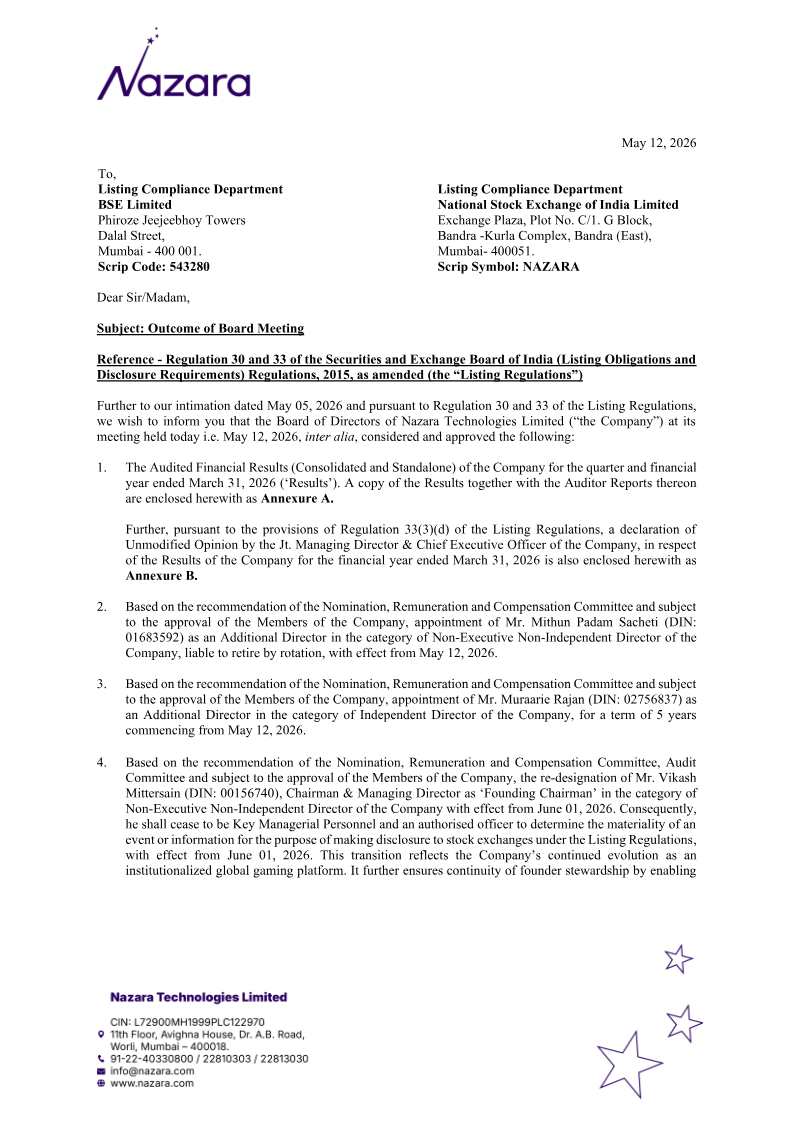
13 Feb 202541 pages~27 min full read
Nazara Technologies achieved record-breaking financial results for the third quarter of fiscal year 2025, characterized by a 66.9% year-over-year increase in consolidated revenue to INR 534.7 crore. This growth trajectory is primarily fueled by a 53% expansion in the core gaming segment, which maintained a robust 22.2% EBITDA margin. While consolidated EBITDA rose by 38.9% to INR 52.4 crore, net profitability faced pressure from a one-time impairment loss associated with Brandscale Innovations. Despite these non-recurring charges and the cancellation of the NH7 Weekender, the company maintains a strong focus on scaling high-margin business lines across its three primary pillars: gaming, esports, and adtech.
The company is aggressively diversifying its portfolio through strategic international expansion and targeted acquisitions. Recent investments, including the purchase of Fusebox Games and the acquisition of popular gaming intellectual properties such as CATS and King of Thieves, underscore a commitment to strengthening its global footprint. Furthermore, the integration of entities like StarLadder, Trinity Gaming, and AFK Gaming has solidified its market position within the competitive esports landscape. Beyond digital gaming, the firm is diversifying into offline entertainment through a majority stake in Funky Monkeys, signaling a broader strategy to capture value across the entire gaming and lifestyle ecosystem.
Financial stability remains a priority as the organization prepares for future growth. A proposed INR 495 crore preferential equity issue, coupled with a subsequent open offer by investors, is set to bolster the company’s capital reserves. By balancing organic growth in established segments like Sportskeeda with the integration of new acquisitions like Space & Time Media, the firm is positioning itself to navigate the evolving global gaming market. These initiatives collectively reflect a transition toward a more integrated, diversified, and capital-efficient business model aimed at long-term scalability.
The Game Business · 2026
The Game Business · 2026
PocketGamer.biz · 2026
Extra Credits · 2026
State of Delaware · 2026
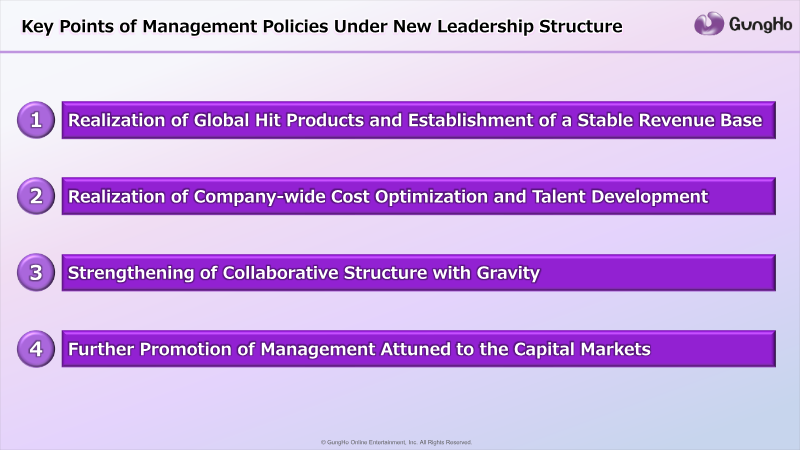
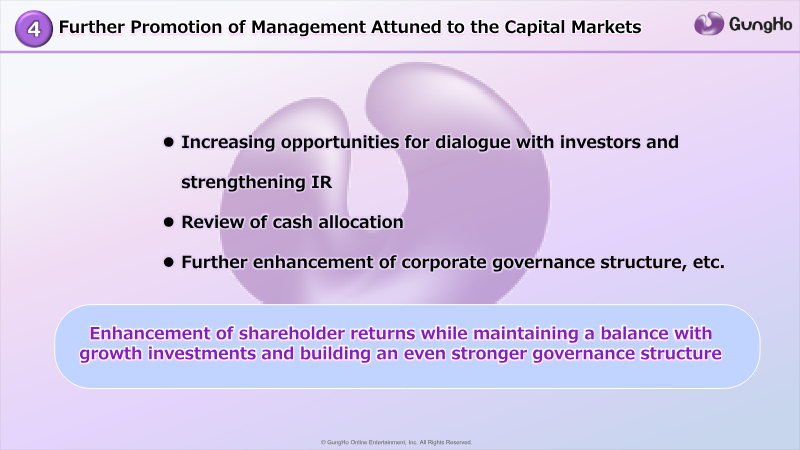
GungHo Online Entertainment · 2026
Deconstructor of Fun · 2026
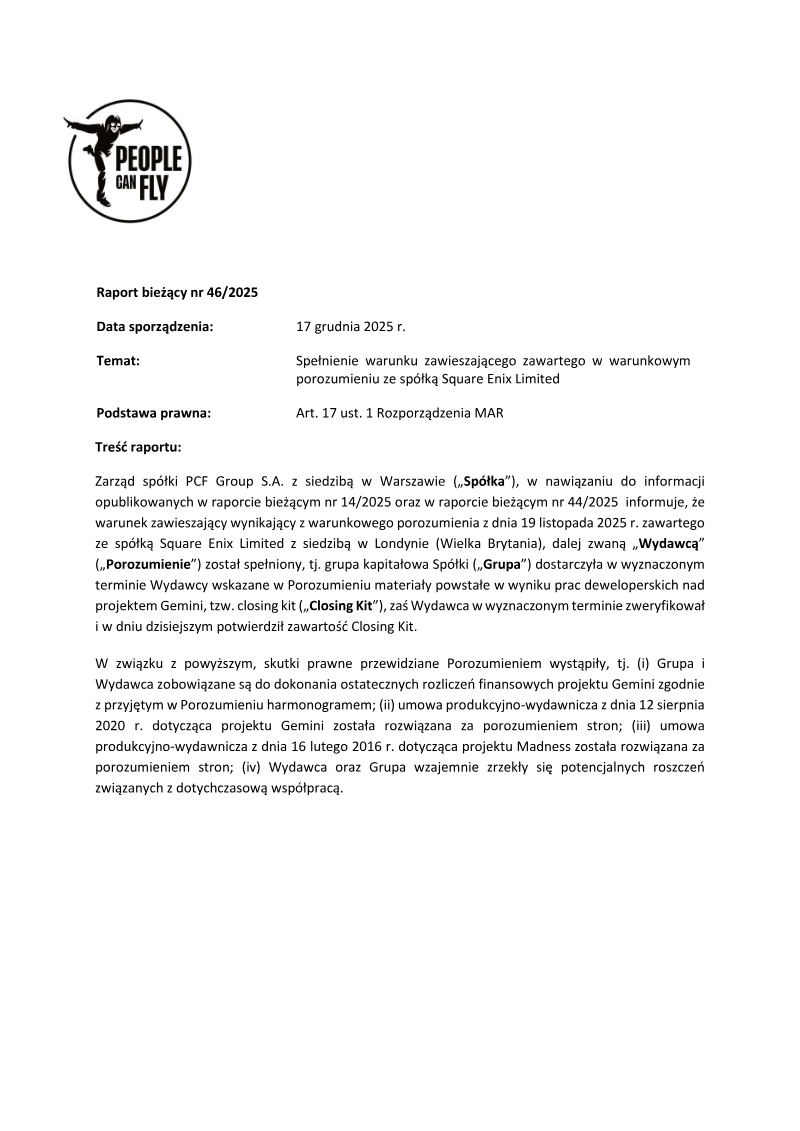
PCF Group · 2025
Deconstructor of Fun · 2025
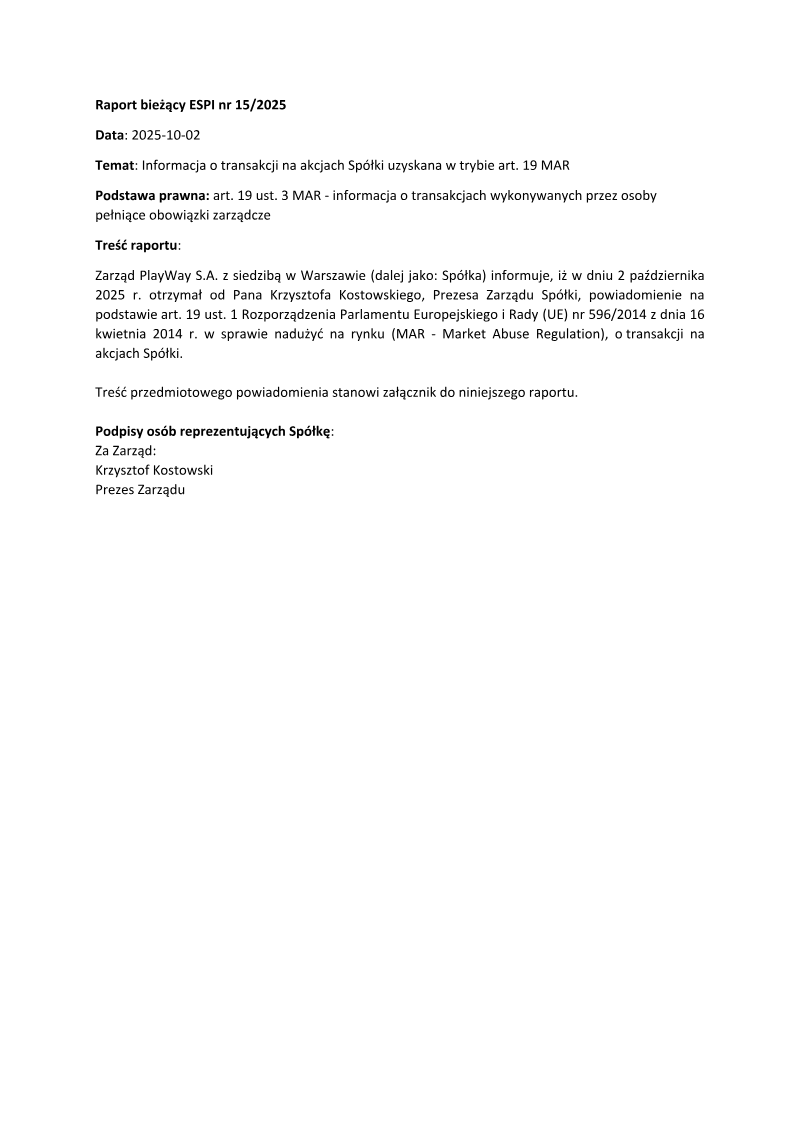
PlayWay · 2025
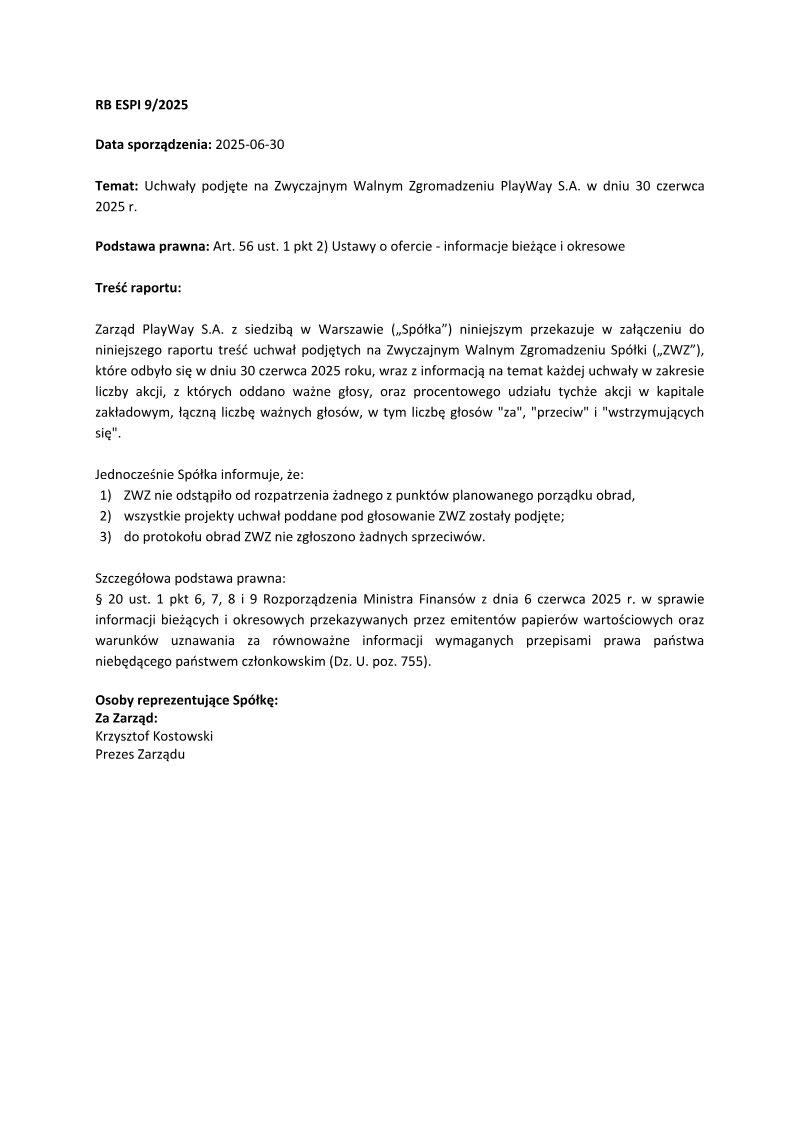
PlayWay · 2025


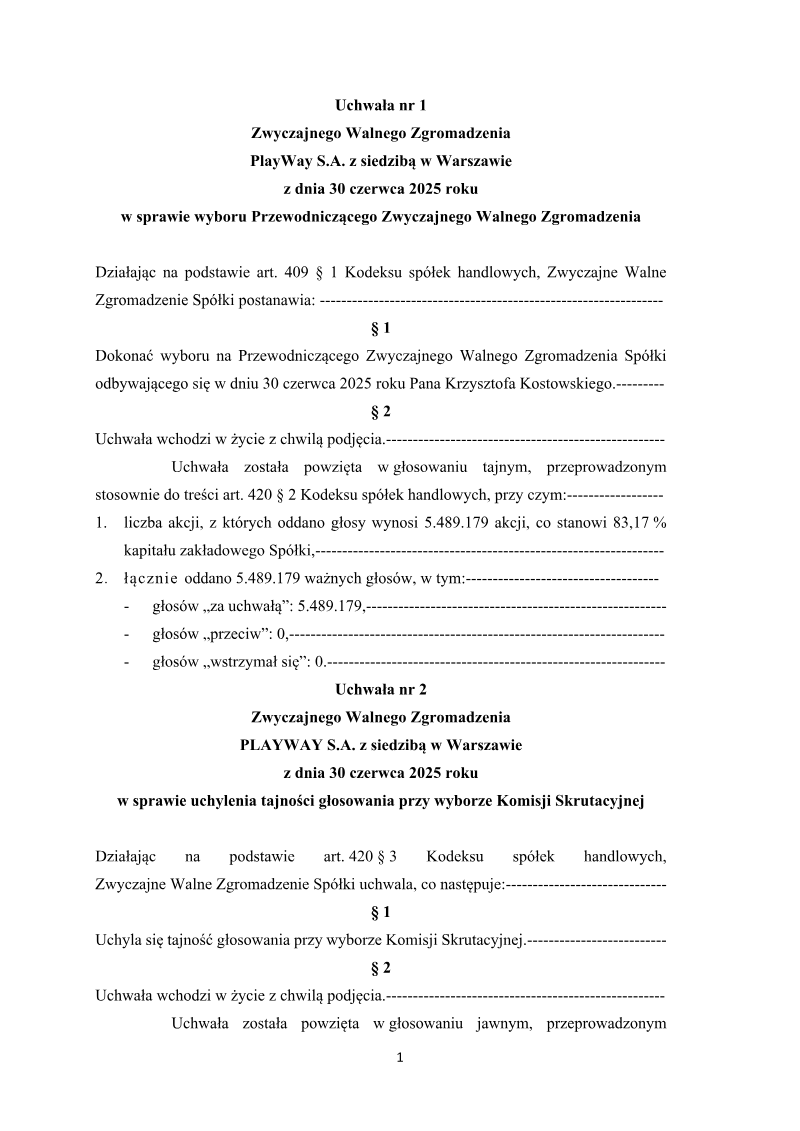
PlayWay · 2025




Comments