PresentationGungHo Online Entertainment
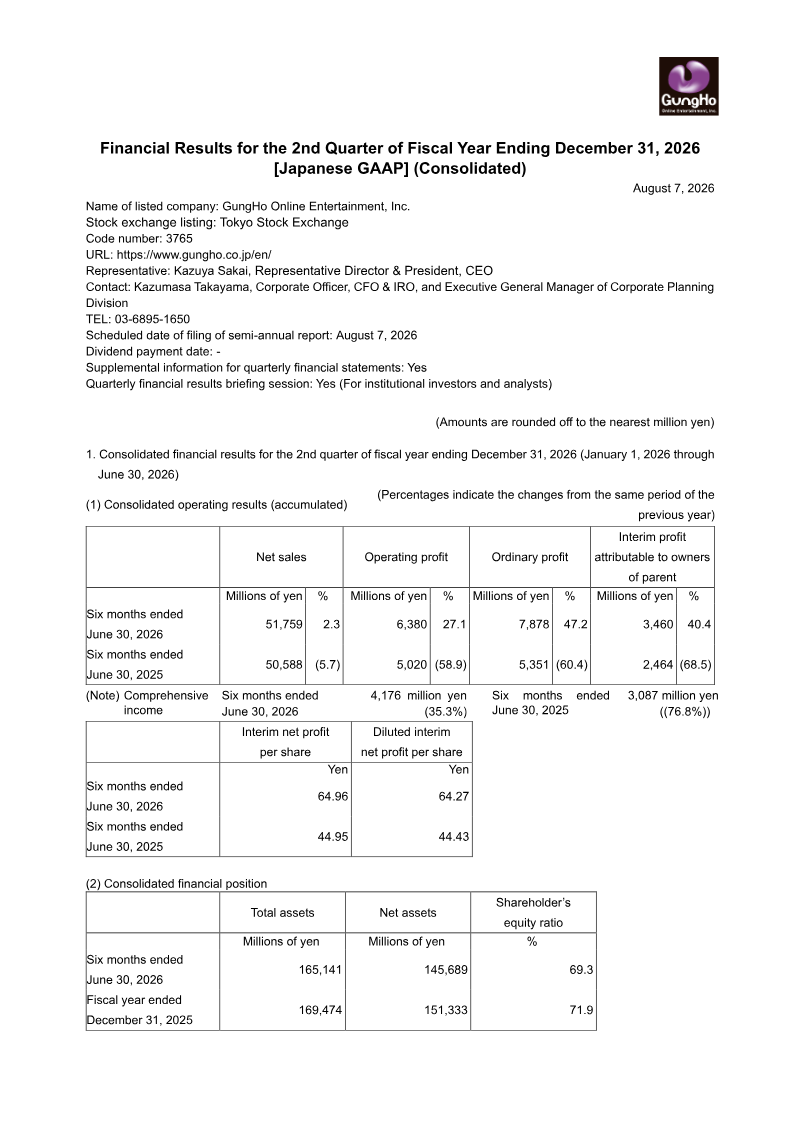
Financial Results Briefing FY2025
1 Feb 202624 pages~10 min full read
Key insights
6 slides
Strategic shift
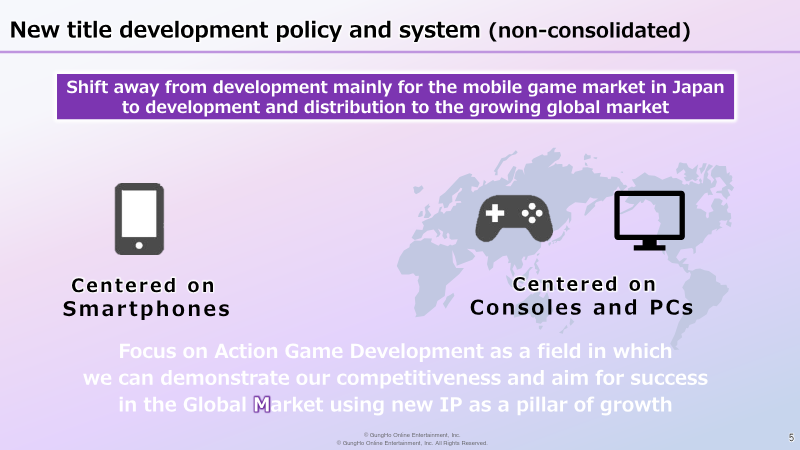
GungHo is pivoting from domestic mobile to a global, multi-platform model.
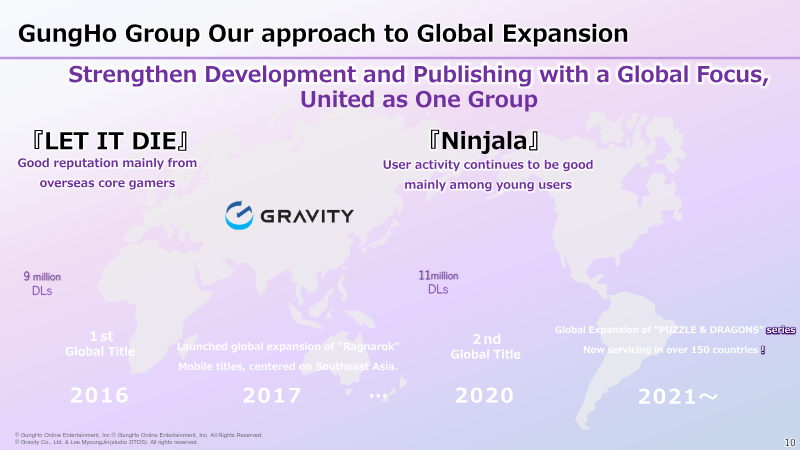
The company is transitioning from a primary focus on the Japanese mobile market toward a global distribution model. This shift targets North America and Europe through console and PC action-oriented intellectual properties.
Global reach. Overseas net sales ratio is projected to reach 66% in fiscal year 2025.
The downturn
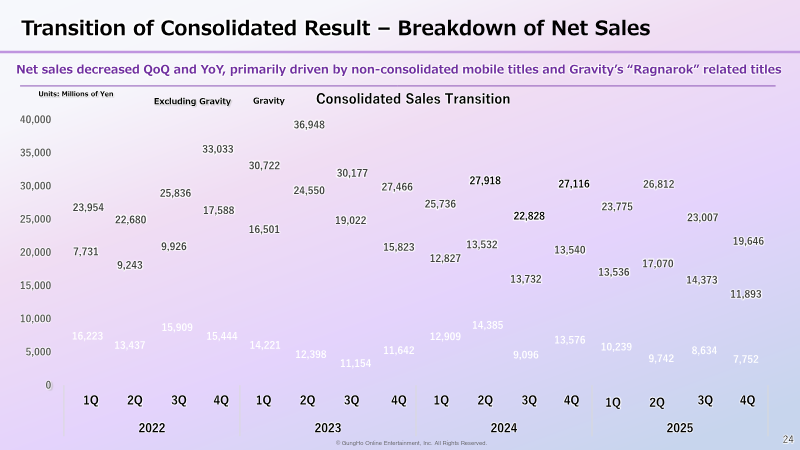
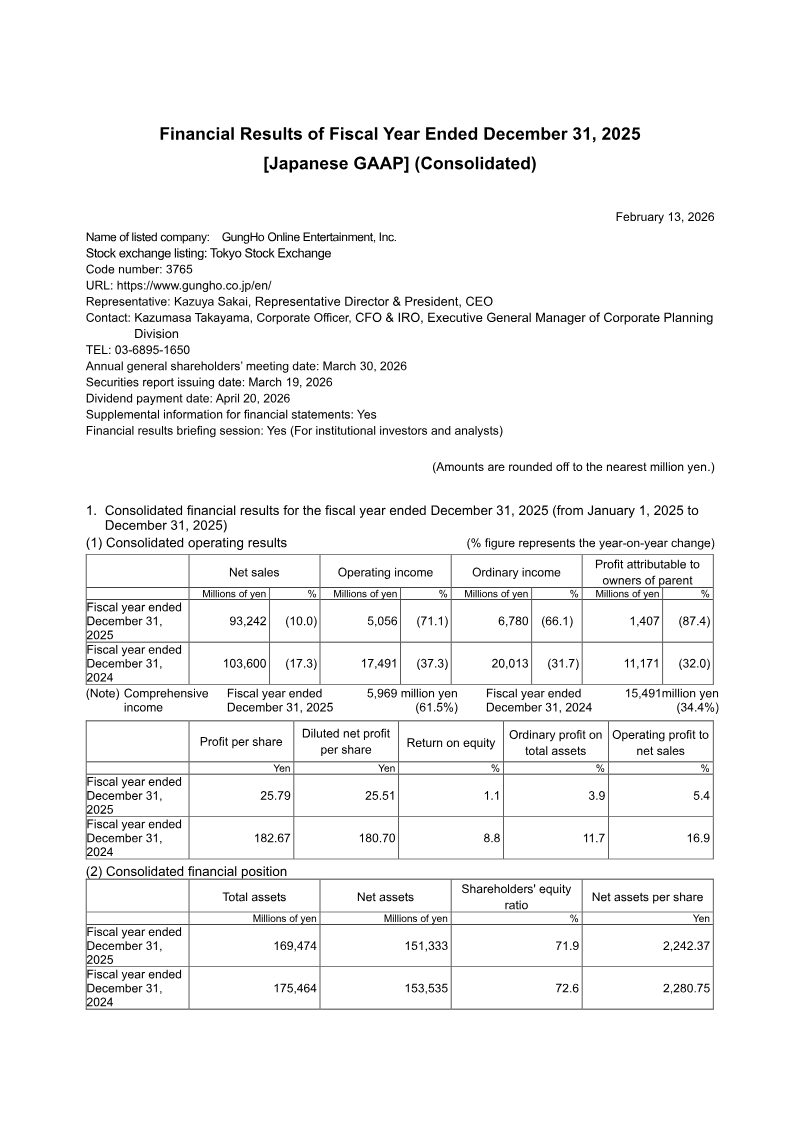
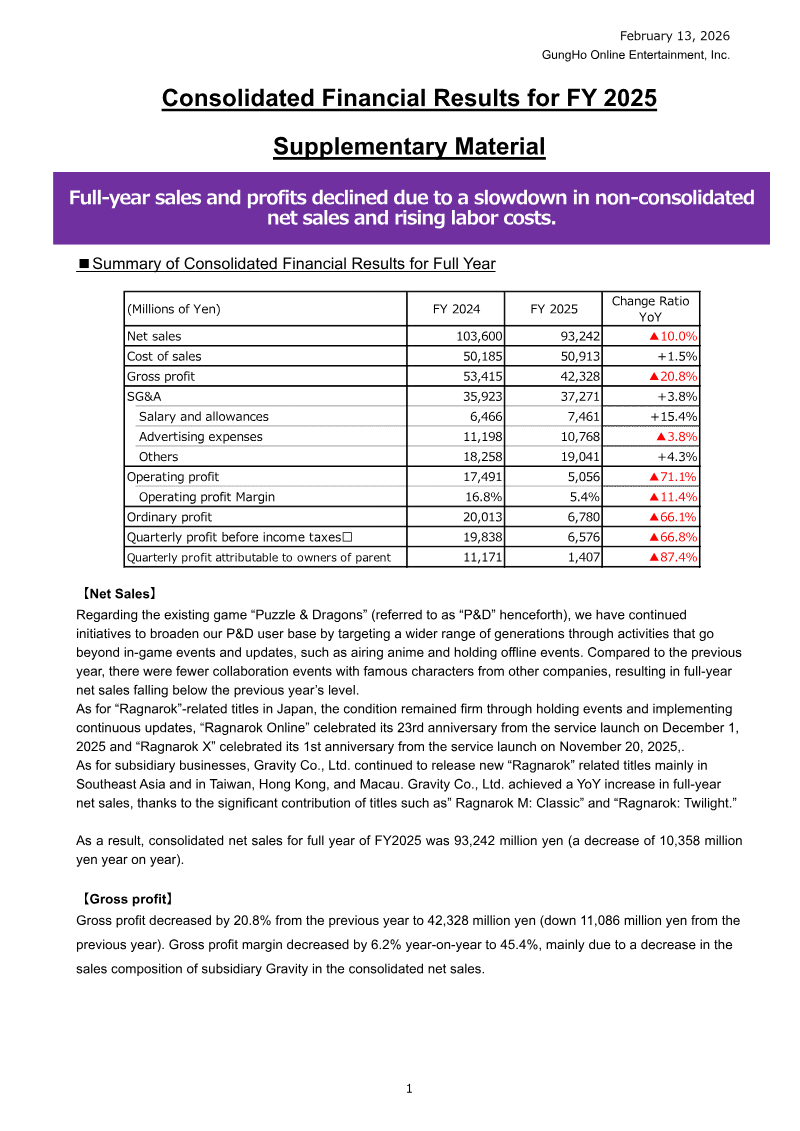
Consolidated net sales and operating profit are in a four-year decline.
Quarterly performance data reveals a downward trajectory over a four-year period. Peak values declined from over 16,000 to approximately 7,750 in the most recent quarter.
Page 22 of the report2024.1Q257.3
2024.2Q279.1
2024.3Q228.2
2024.4Q271.1
2025.1Q237.7
2025.2Q268.1
2025.3Q230
2025.4Q196
Core asset defense
GungHo is leveraging high-profile collaborations to stabilize core mobile assets.
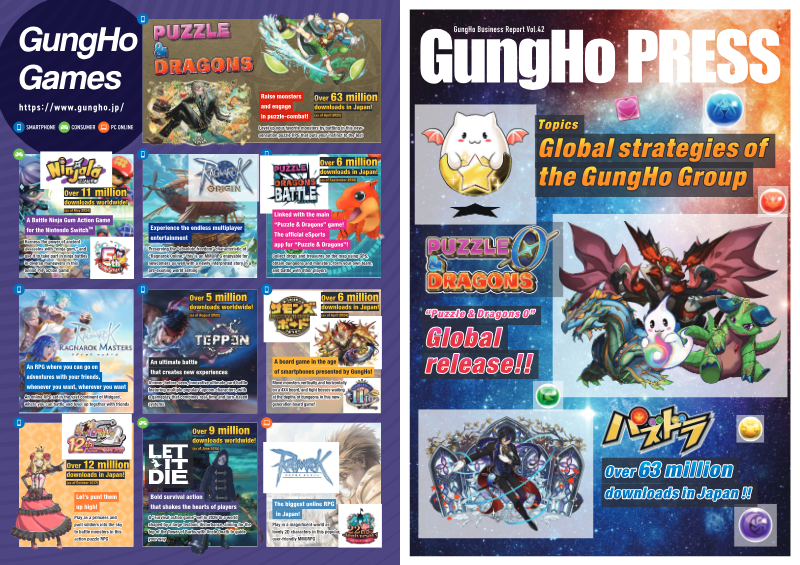
The company is addressing softening sales of legacy mobile titles and decreased revenue from Gravity. High-profile collaborations with brands like Sanrio and Digimon are used to maintain domestic user engagement.
Franchise expansion
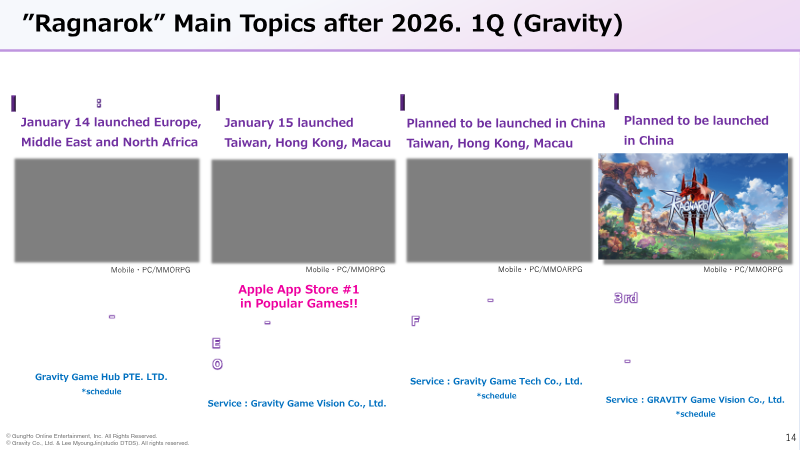
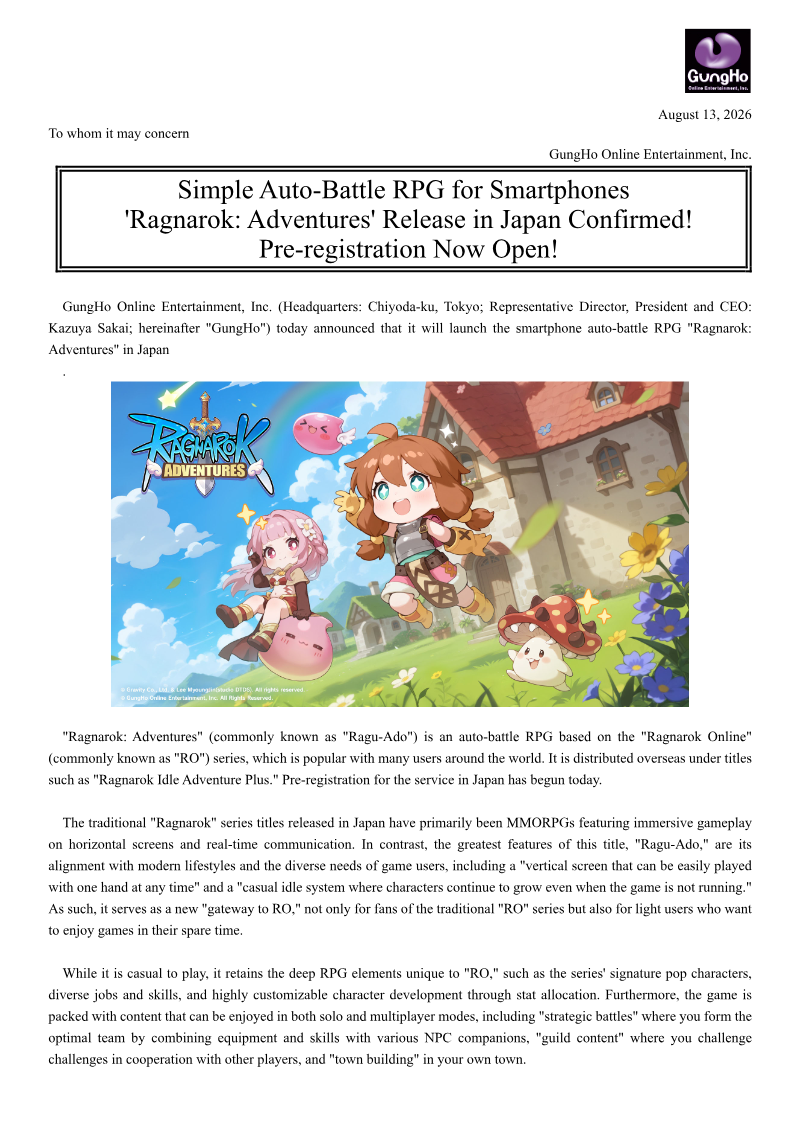
Future growth is anchored in the expansion of the Ragnarok franchise.
The upcoming launch of Ragnarok Online 3 in Asian markets and the introduction of Ragnarok X: Next Generation to EMEA regions anchor future growth. This expansion balances established mobile revenue with new, high-scale global releases.
Platform shift
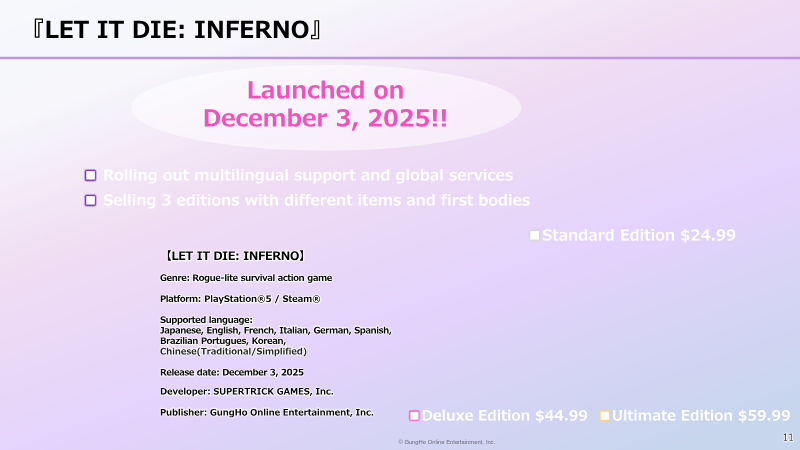
GungHo is shifting its development focus toward action-oriented console and PC IPs.
The company is shifting its development focus toward action-oriented console and PC intellectual properties.
New mechanics
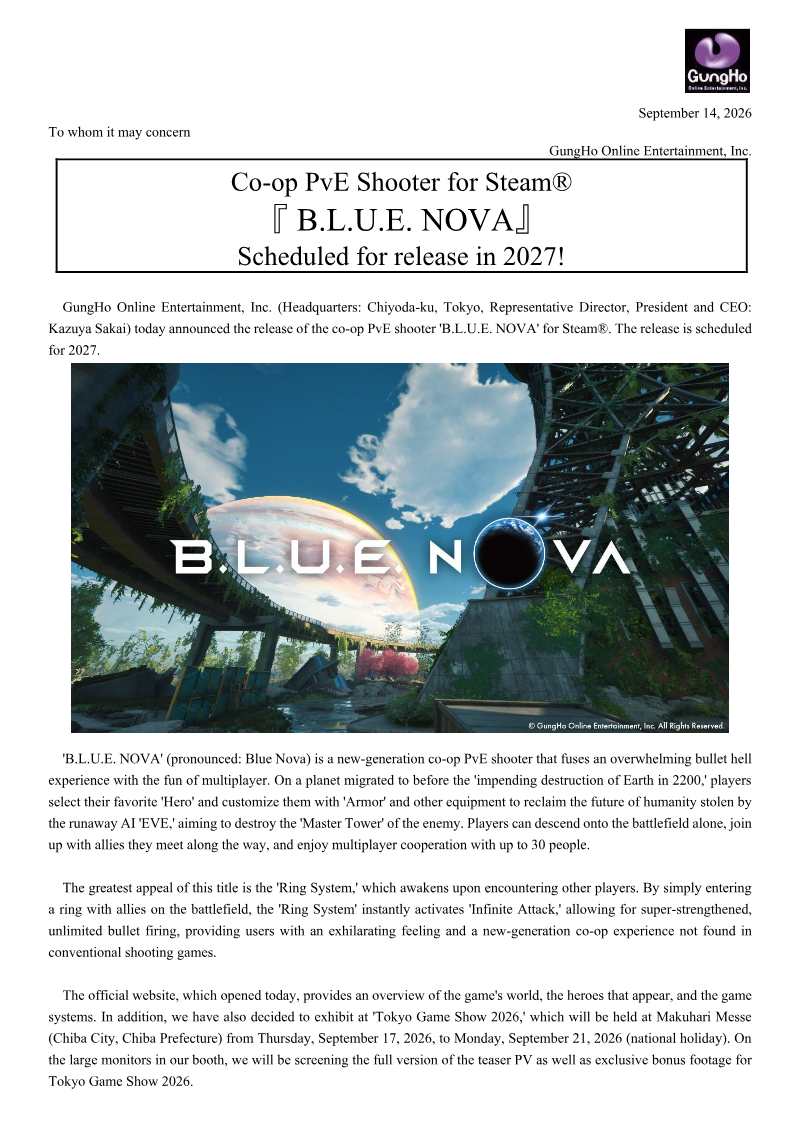
GungHo is integrating 100-player raid mechanics into its new project pipeline.
To compete in the global market, the company is integrating more technologically ambitious features into its new project pipeline. This includes 100-player raid mechanics in upcoming titles.
1 / 6
Ask AI about this report
Comments