Mobile Games
The mobile market by genre, from hypercasual and puzzle to midcore and idle.
403 documents
Sensor Tower · 2021
ReportThe State of Mobile Gaming 2021
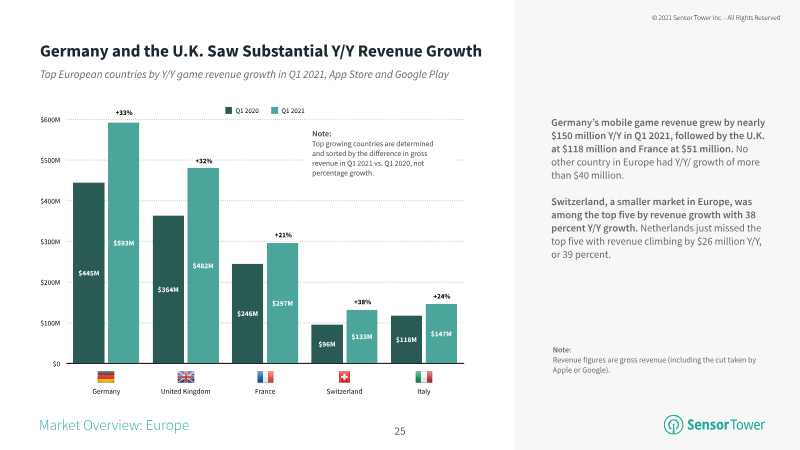
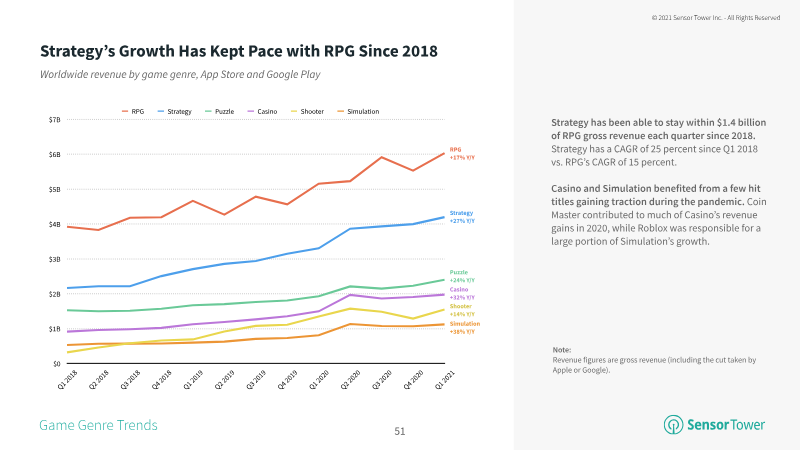
The global mobile gaming industry experienced unprecedented expansion through early 2021, catalyzed by a pandemic-induced surge that drove quarterly revenue to a record $22.2 billion. This growth represents a significant 33% year-over-year increase, with the United States emerging as the premier revenue market, contributing 28% of global consumer spending. While mature markets in North America and Europe reached new financial heights, developing regions—most notably India—served as the primary engines for user acquisition, pushing global downloads to new peaks. Asia remains the largest collective region, surpassing $12 billion in quarterly revenue, anchored by Japan’s robust $5 billion contribution. Market dynamics shifted toward social and multiplayer experiences, with titles such as Roblox and Genshin Impact dominating both engagement and monetization. RPG and Strategy remain the highest-grossing genres, generating $21.9 billion and $15.1 billion respectively in 2020, though Simulation and Shooter categories exhibited the fastest year-over-year growth. Simultaneously, the Hypercasual genre achieved staggering scale, reaching 3.4 billion downloads in a single quarter. This high-volume segment has become a cornerstone of the mobile advertising ecosystem, where publishers like Zynga and Playrix maintain a dominant share of voice across major digital networks. Monetization has consolidated almost entirely around the freemium model, which now accounts for 99% of App Store revenue through a combination of in-app purchases, subscriptions, and advertising. Looking forward, the industry is projected to reach $117 billion in annual revenue by 2023, maintaining a compound annual growth rate of 13.5%. While the initial pandemic-driven spike in downloads has stabilized, the sustained increase in consumer spending and the rapid growth of markets in Southeast Asia and Europe indicate a permanent upward shift in the global gaming trajectory.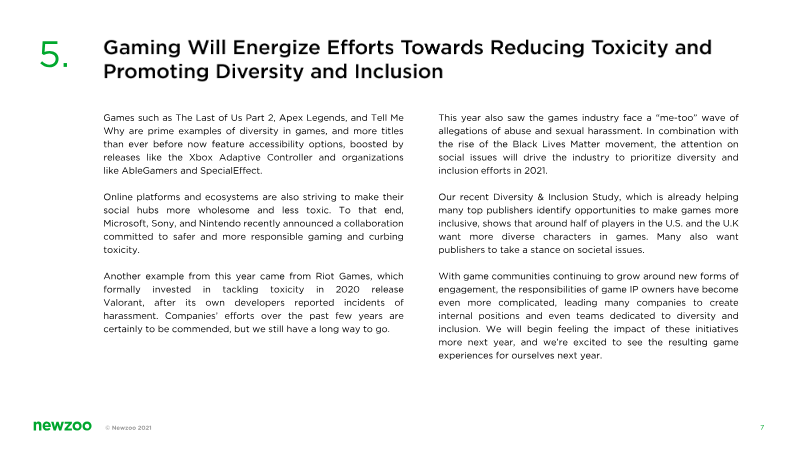
Newzoo · 2021
ReportNewzoo Trends to Watch 2021
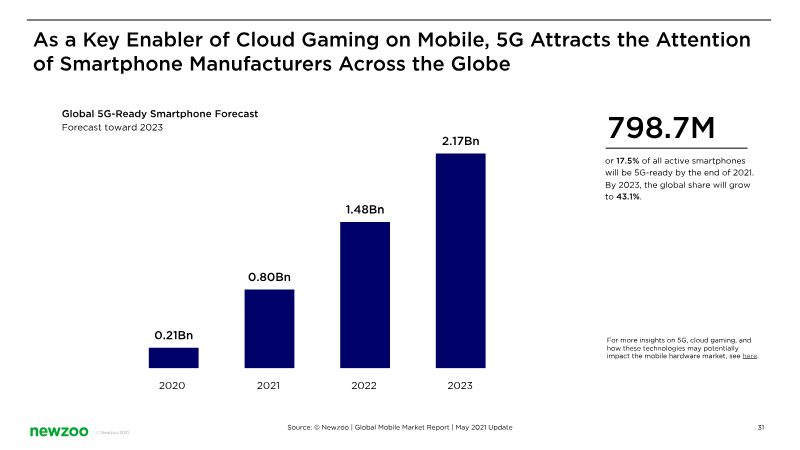
This analysis outlines the primary trends shaping the global games, esports, and mobile markets for 2021. The central thesis posits that while the COVID-19 pandemic accelerated engagement and spending, these behaviors have become permanent habits that will sustain market growth even as lockdowns ease. By the end of 2021, the global games market is projected to reach $189.3 billion in revenue, supported by a player base of 2.8 billion people, with significant growth emerging from Southeast Asia and the Middle East. The scope of the findings covers PC, console, and mobile segments across major global regions, including North America, Europe, China, and emerging markets. Key data points include the rise of cloud gaming, which is expected to surpass $1 billion in annual revenue for the first time, and the rapid expansion of 5G technology, with 5G-ready active smartphones forecasted to grow from 5% in 2020 to 16% (700 million units) by the end of 2021. In the esports sector, mobile titles like PUBG Mobile and Garena Free Fire are now challenging traditional PC giants in viewership, signaling a shift toward mobile-first competitive gaming. Methodologically, the findings are derived from proprietary market models and consumer research. The analysis highlights several structural shifts: the evolution of games into "metaverse" social platforms for non-gaming events, the disruption of mobile marketing due to the removal of Apple’s Identifier for Advertisers (IDFA), and the increasing pressure on traditional app store revenue-share models. Furthermore, the industry is noted to be prioritizing diversity, inclusion, and reduced toxicity in response to social movements and player demand. Ultimately, the convergence of platforms and the expansion of gaming IP into broader entertainment media are identified as the defining characteristics of the industry's trajectory.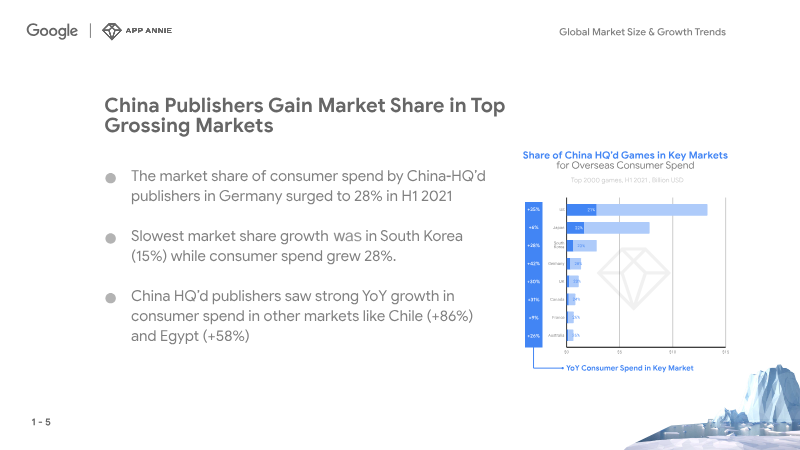
data.ai · 2021
ReportInnovate to Win on the Next Level with Hybrid Genre Games
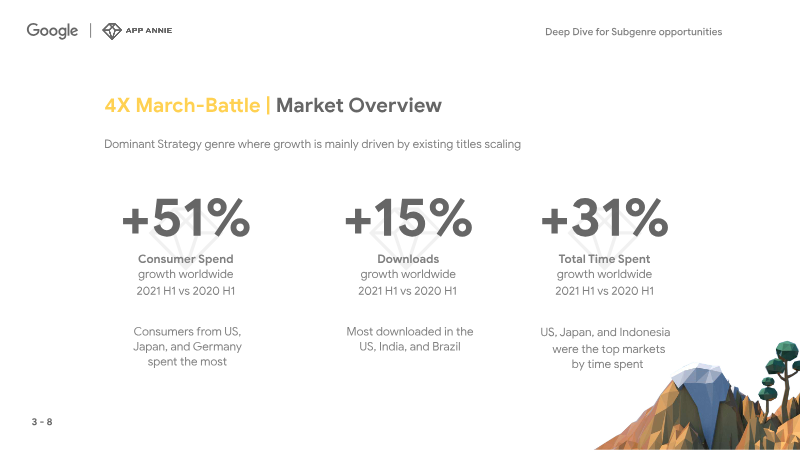
The global mobile gaming landscape has entered a period of sustained growth following the pandemic, with overseas consumer spending reaching $36 billion in the first half of 2021. This represents a 73% increase since 2018, a trend largely spearheaded by China-based publishers who now command a 23% share of the international market. To sustain this trajectory, the industry is shifting toward hybridization, a strategy that blends core mechanics from disparate subgenres to broaden player demographics and optimize revenue streams. By integrating casual elements like farming or social multiplayer features into hardcore frameworks, developers are successfully diversifying their monetization models beyond traditional structures. Market performance in early 2021 reveals that while Strategy, RPG, and Match subgenres remain the primary revenue drivers, high-growth categories such as Luck Battle and Merge-Saga are emerging as significant leaders. The 4X March-Battle subgenre, in particular, saw a 51% year-over-year increase in consumer spend, fueled by strong performance in the United States, Japan, and Germany. Additionally, the Idol Training subgenre experienced an explosive 129% surge in spending, highlighting the rising influence of Asian cultural themes and "Nijigen" aesthetics in the global market. Despite these gains, the industry faces challenges from evolving user privacy policies, which contributed to a 12% contraction in Puzzle RPG spending. In response, successful developers are increasingly utilizing hybrid tactics such as Gacha monetization, home design meta-layers, and social connectivity to maintain engagement. The transition toward these multifaceted game designs suggests that the future of mobile gaming lies in the ability to merge deep, mid-core progression systems with accessible, casual mechanics to capture a more diverse and resilient global audience.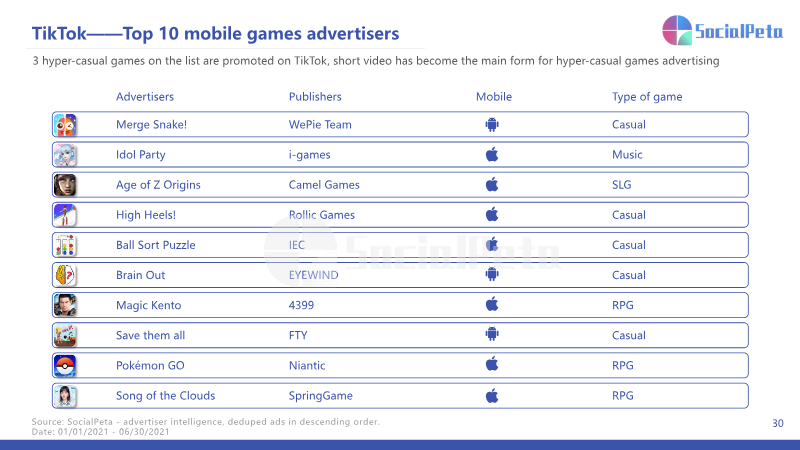
SocialPeta · 2021
Report2021 H1 Global Mobile App Marketing Whitepaper
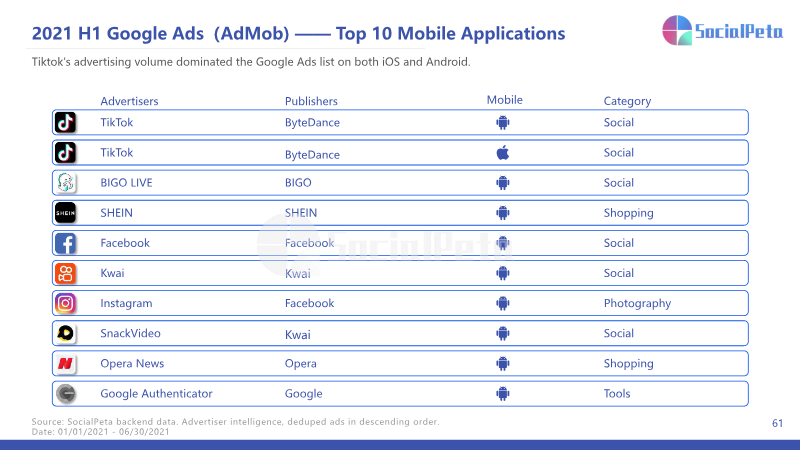
The global mobile marketing landscape experienced a massive surge in activity during the first half of 2021, characterized by a 108% year-on-year increase in advertising creatives totaling over 19 million. This growth was primarily driven by hard-core gaming titles and a significant expansion in the non-game sector, where creatives rose 38% to 47.6 million. Despite this volume increase, Apple’s IDFA policy changes caused a 13% decline in the share of iOS creatives, shifting more focus toward Android platforms. Geographically, the United States remained the largest advertising market, while Oceania emerged as the fastest-growing region for non-game advertisers. Chinese companies solidified their global dominance during this period, accounting for 70% of top-charting mobile game media buying and over 25% of the total global market share. These developers maintained a particularly strong presence on major social platforms, representing 100% of the top ten advertisers on Facebook’s News Feed. However, this increased competition contributed to a sharp rise in acquisition costs, with Facebook’s average CPC and CPM both climbing 128% year-over-year. RPG and Puzzle genres led in total creative volume, while Strategy games exhibited the highest media buying intensity per advertiser. Marketing strategies have evolved toward high-engagement, "snackable" short-form video content and influencer-led campaigns to combat rising costs and privacy-related tracking challenges. In the gaming sector, creative tactics shifted toward live-action footage and gameplay extensions, while non-game apps—particularly in the education and shopping sectors—capitalized on pandemic-related lifestyle shifts. As the industry navigates the post-IDFA era, the integration of high-quality in-game ads and diverse creative formats has become essential for maintaining user retention and driving monetization across both domestic Chinese and international markets.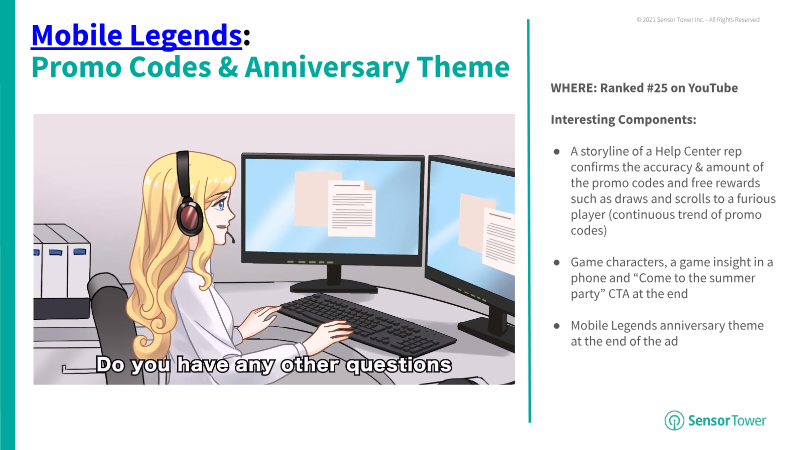
Sensor Tower · 2021
ReportMobile Ad Creative Report: August 2021
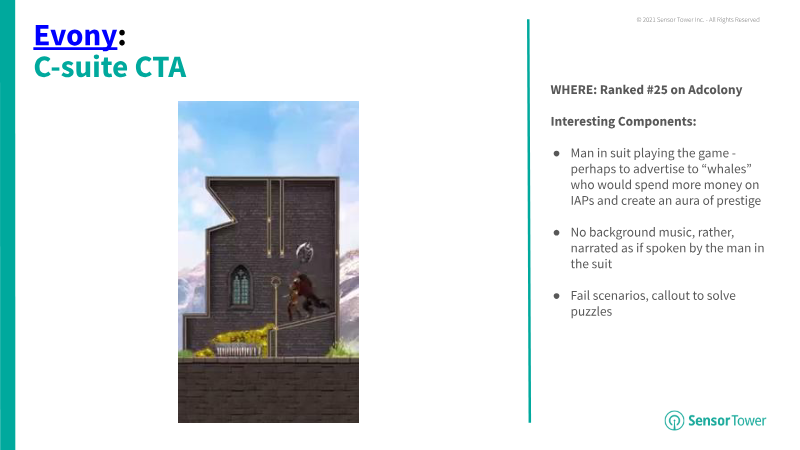
Mobile gaming creative trends in August 2021 centered on humanizing digital experiences and leveraging high-profile cultural partnerships. Analysis of top-performing ads across platforms like YouTube, Instagram, Snapchat, and Facebook reveals a heavy reliance on real-world celebrities, particularly musicians. Notable examples include Garena Free Fire featuring DJs Dimitri Vegas & Like Mike as playable characters and Call of Duty Mobile partnering with artist Ozuna. These collaborations often utilize cinematic storytelling and high-fidelity animations to bridge the gap between gaming and mainstream entertainment. The industry continues to utilize specific psychological triggers and visual formats to drive engagement. Fail-state elements, where ads demonstrate a player losing a level to pique viewer interest, remain prevalent in titles like Royal Match and Evony. Additionally, hyper-casual games are increasingly adopting popular music soundtracks and expressive callouts to appeal to younger demographics on Snapchat. Other emerging visual trends include split-screen layouts, the use of Bitmojis, and "search bar" call-to-actions that visually demonstrate how to find the app in stores. Geographically, the findings cover global releases with specific performance data from major ad networks including ironSource, Applovin, and Vungle. The scope encompasses diverse genres, from mid-core shooters and RPGs to hyper-casual and puzzle games. Methodology involves ranking creatives based on their performance and visibility across social media and ad networks during the August 2021 period. Conclusions suggest that successful creatives are moving away from pure gameplay footage in favor of narrative-driven content, anniversary themes, and interactive elements like Buzzfeed-style quizzes or "Christmas in July" promotions.
Liftoff · 2021
ReportMobile Game Video Ads Analysis: Optimal Video Lengths and End Cards
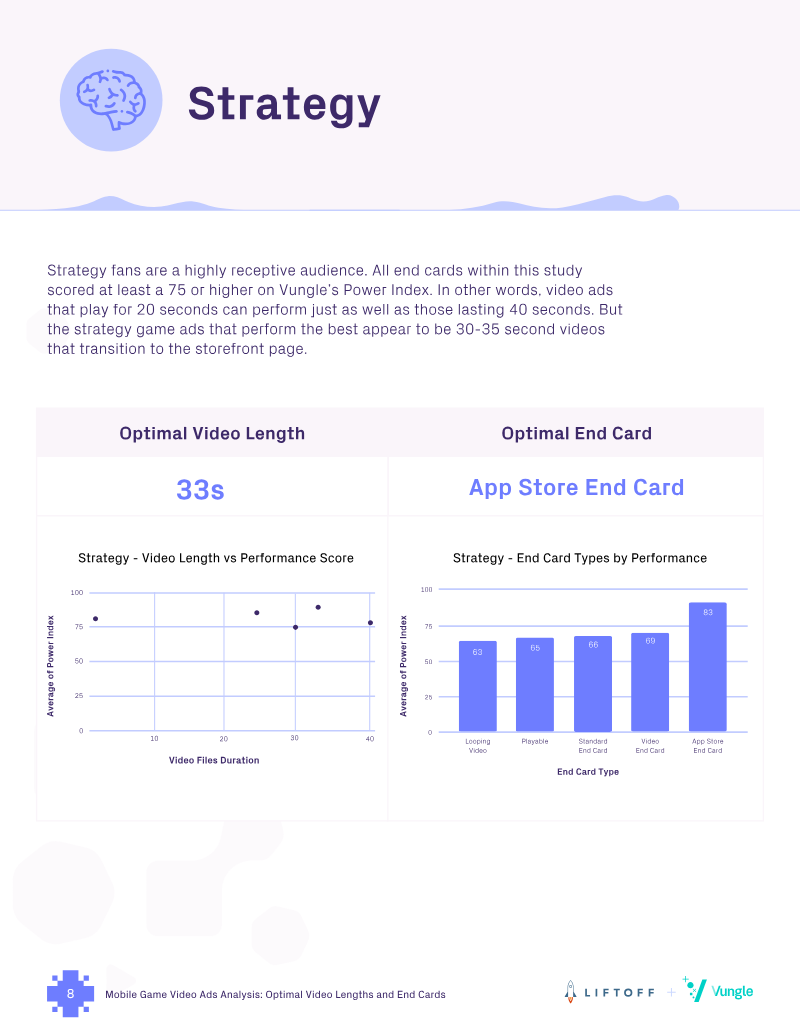
This analysis examines the relationship between video ad length, end card formats, and campaign performance across five major mobile gaming genres: Hyper-Casual, RPG, Strategy, Puzzle, and Social Casino. By evaluating 3.7 billion in-app video ad impressions and subsequent installs via the Vungle platform, the study establishes creative benchmarks using a proprietary Power Index to measure efficacy. The findings suggest that as the industry moves toward a post-IDFA environment with limited user-level data, marketers must prioritize creative optimization and mass-appeal strategies to drive engagement. The data reveals distinct audience preferences for each genre. Social Casino players favor efficiency, responding best to 10-second ads paired with standard static end cards. Puzzle and Strategy games both see peak performance when utilizing app store end cards that provide a direct path to download, though their optimal video lengths differ at 22 seconds and 33 seconds, respectively. Conversely, genres with deeper gameplay loops require more extensive creative storytelling. Hyper-Casual games perform best with 37-second ads and video end cards, while RPGs benefit from the longest engagement times, peaking at 46 seconds with looping video end cards to showcase aesthetic and narrative depth. The scope of the research covers a global audience of over one billion unique devices, focusing on the structural elements of ad creatives rather than specific visual content. The methodology filters out low-performing impressions to ensure the Power Index accurately reflects the most successful format pairings. Ultimately, the findings conclude that aligning ad duration and post-roll interactive elements with genre-specific player expectations is essential for maximizing return on ad spend in an increasingly competitive mobile marketplace.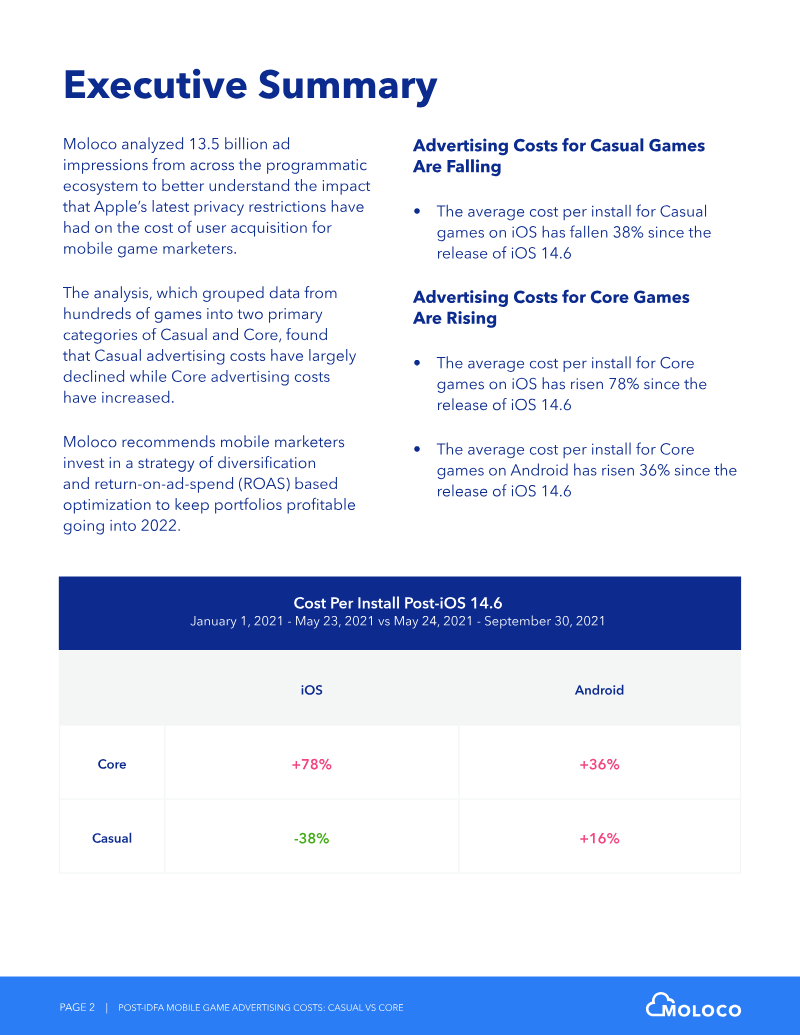
Moloco · 2021
ReportPost-IDFA Mobile Game Advertising Costs: Casual vs Core
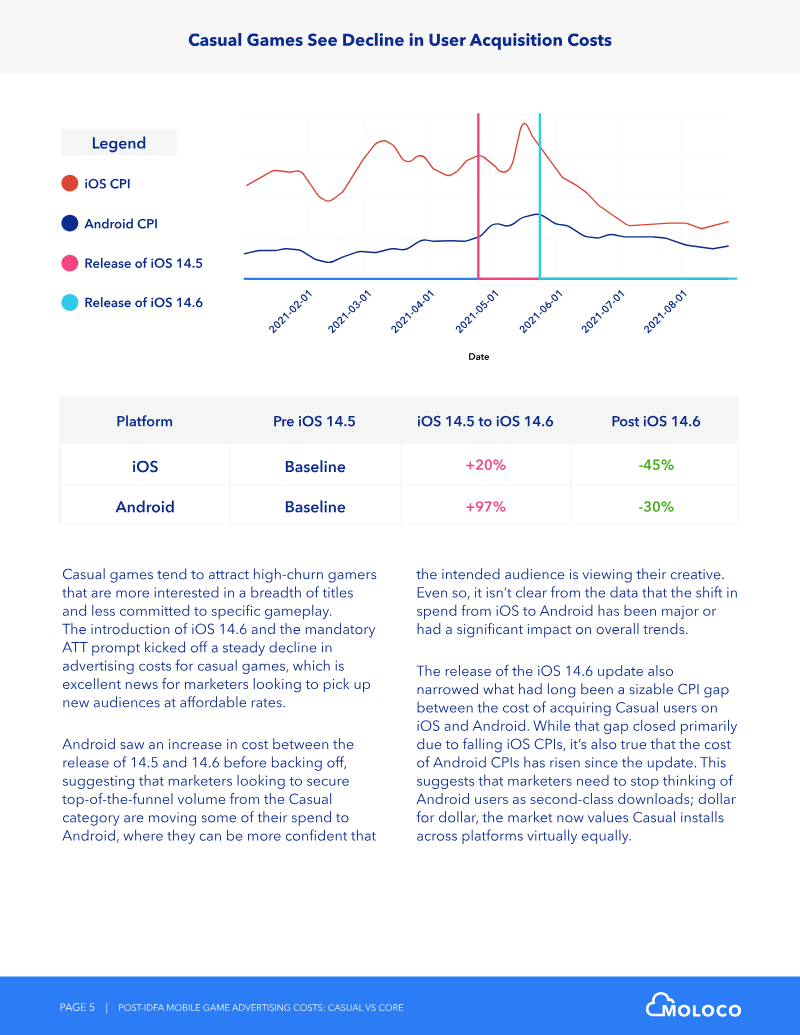
The analysis quantifies how Apple’s post-IDFA privacy updates have reshaped user-acquisition economics for mobile games, contrasting casual titles with core experiences. By aggregating 13.5 billion programmatic ad impressions from iOS and Android between January 1 2021 and September 30 2021, the study tracks cost-per-install (CPI) trends across three intervals—pre-iOS 14.5, during the iOS 14.5-14.6 rollout, and post-iOS 14.6—using Moloco’s proprietary game taxonomy to separate titles into casual and core categories. Casual games experienced a sharp decline in iOS CPI, falling 38% after the iOS 14.6 release, while Android CPI for the same segment rose modestly by 16%. In contrast, core games saw iOS CPI surge 78% and Android CPI increase 36% over the same period, reflecting intensified competition for a shrinking pool of high-value, trackable users. The narrowing of the historical iOS-Android CPI gap for casual titles indicates that Android installs now command comparable monetary value, whereas iOS remains the premium channel for core audiences due to higher in-app-purchase conversion rates. Methodologically, the research averages weekly CPI data across the defined date ranges, applying a taxonomy that classifies games by genre and engagement depth, with subcategories overlapping between casual and core groups. Findings suggest that the divergent CPI trajectories are driven by user churn characteristics and lifetime-value differentials rather than seasonal factors. Strategic recommendations emphasize diversifying media spend, allocating budget to campaigns optimized for return-on-ad-spend, and leveraging machine-learning-based bidding to mitigate volatility. These practices aim to preserve profitability amid the evolving privacy-driven market dynamics for both casual and core mobile game publishers.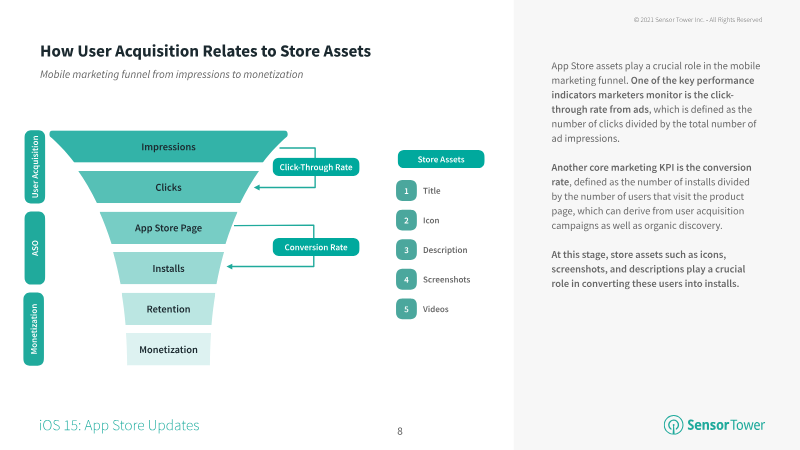
Sensor Tower · 2021
ReportMobile Game Store Asset Optimization Trends 2021
Strategic store asset optimization is a critical driver for increasing conversion rates and reducing user acquisition costs in the mobile gaming industry. Analysis of top-performing publishers reveals that the most successful entities treat app icons, screenshots, and product pages as dynamic marketing tools rather than static assets. This approach is particularly relevant following the release of iOS 15 in late 2021, which introduced Custom Product Pages and Product Page Optimization. These features allow developers to create up to 35 unique landing pages and conduct native A/B testing for up to 90 days, enabling highly targeted campaigns for specific audiences and influencers. Data from major titles illustrates several dominant trends in asset management. Seasonal updates are a primary strategy; for instance, Golf Clash implemented 17 icon changes between 2017 and 2021 to reflect holidays like Halloween and St. Patrick’s Day. Other publishers, such as King and Garena, prioritize brand identity by integrating corporate logos across their entire portfolios to leverage existing brand equity. Furthermore, "forever franchises" like Animal Crossing: Pocket Camp use icon updates to signal anniversaries and live operations events, driving re-engagement among lapsed players. A significant shift in the industry involves the alignment of store assets with high-performing ad creatives. Publishers like Playrix and Nexters successfully utilized "Pull the Pin" advertisements—which often differ from core gameplay—to lower costs per install. To minimize friction and improve conversion, these companies updated their App Store screenshots and icons to match the ad content. While such experimentation was historically more prevalent on Google Play due to its long-standing A/B testing tools, the new iOS 15 capabilities are expected to catalyze similar data-driven optimization strategies across the Apple ecosystem. This analysis utilizes Sensor Tower’s proprietary intelligence platforms to track these trends across global markets and major gaming segments.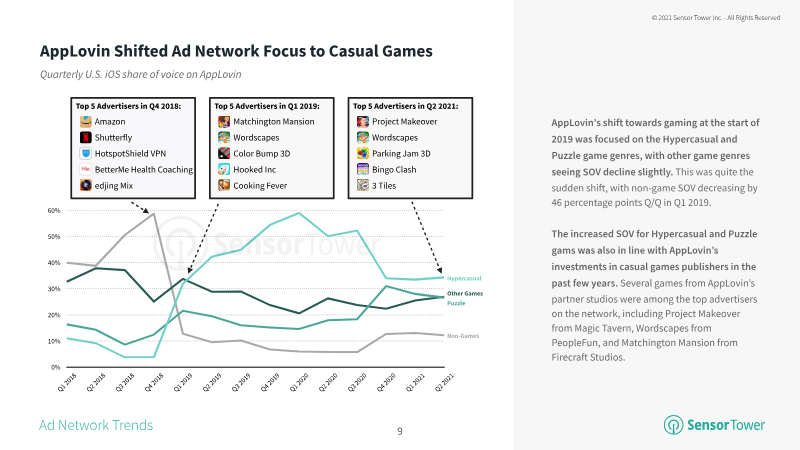
Sensor Tower · 2021
ReportThe State of Mobile Game Advertising: An Analysis of U.S. Mobile Game Advertising Trends in 2021
Mobile game advertising in the United States remained resilient through the first half of 2021, showing no immediate negative impact from privacy changes such as the deprecation of IDFA. Analysis of the advertising landscape reveals a strategic divide between ad networks. Specialized platforms like AppLovin, Chartboost, and Vungle maintain a high concentration of gaming content, often exceeding 90 percent share of voice. In contrast, diversified platforms like Facebook, TikTok, and YouTube maintain a more balanced split between gaming and non-gaming advertisements, serving as critical channels for reaching broader audiences. Market trends indicate that ad network selection is increasingly driven by genre and demographic alignment. Puzzle and Hypercasual games dominate gaming-focused networks, while mid-core genres like Strategy and Shooter find higher engagement on social platforms like YouTube and Instagram. Notably, Adcolony emerged as a primary hub for Casino games, catering to an older, female-leaning demographic. Across most platforms, video remains the dominant creative format, though playable ads have gained significant traction, particularly on AppLovin where they account for over 40 percent of gaming share of voice. Creative strategies are evolving to include "fake playables," relaxing music for casual titles, and real-world testimonial-style conversations. Even mid-core titles with complex mechanics, such as Call of Duty: Mobile, have begun adopting simplified playable "mini-games" to lower the barrier for user acquisition. This data, compiled by Sensor Tower using its Ad Intelligence platform, covers U.S. trends across iOS and Android from 2018 through the second quarter of 2021, suggesting that success in the current market requires a sophisticated mix of genre-specific network targeting and experimental creative formats.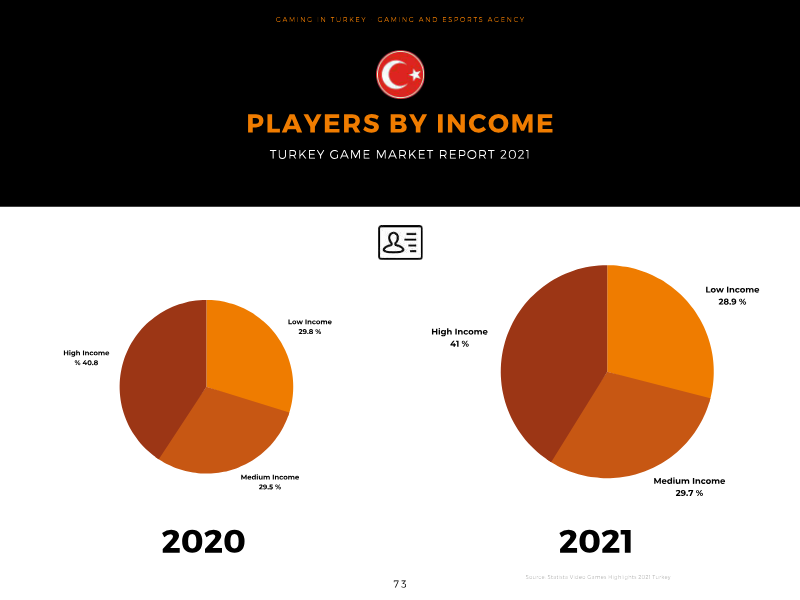
Gaming in Turkey · 2021
ReportTurkey Game Market 2021 Report
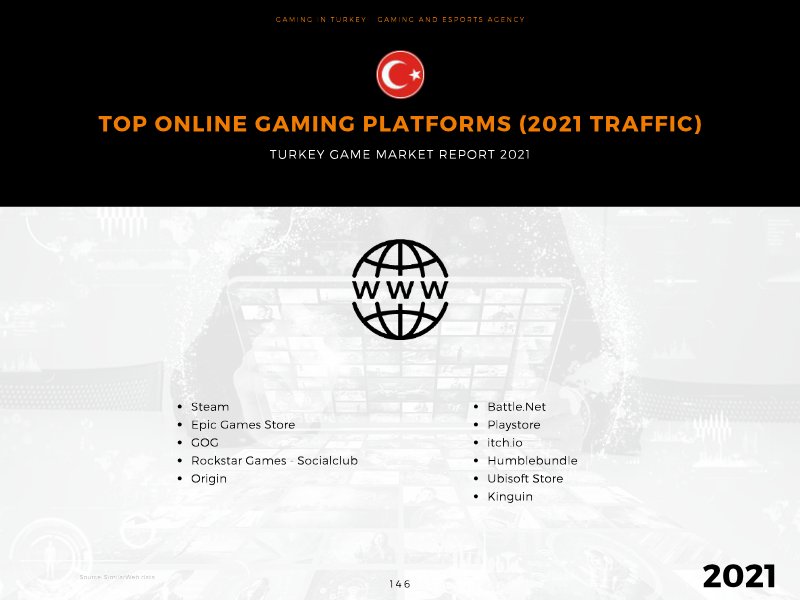
The Turkish gaming market experienced a transformative period of growth and institutionalization in 2021, reaching a total market volume of $1.2 billion. Despite global challenges such as hardware shortages and pandemic-related delays in AAA titles, the local ecosystem expanded to include over 42 million active players. This growth was primarily catalyzed by the mobile segment, which generated $620 million in revenue and solidified Turkey’s position as a global leader in the hyper-casual genre. The year was further defined by record-breaking financial activity, with $266 million invested across 54 startups and the emergence of Dream Games as a new industry "unicorn." Strategically, the market is shifting toward a "gaming-focused entertainment" model, characterized by the rapid adoption of Web3 technologies, including blockchain, NFTs, and Play-to-Earn (P2E) frameworks. While mobile gaming remains the dominant force, there is a burgeoning esports ecosystem supported by approximately 6 million followers and a national federation overseeing 165 licensed clubs. Turkey’s selection as the host for the Global Esports Games 2022 underscores its rising international profile. However, industry experts note a strategic need to diversify beyond mobile platforms into PC and console development to ensure long-term sustainability. The regional landscape reveals Turkey as the primary gaming powerhouse in the Middle East, outperforming neighboring markets in both revenue and player engagement. Success for international entrants remains contingent on high-quality localization and cultural adaptation, given the country's low English proficiency and unique consumer preferences for competitive genres and specific musical influences. As the sector transitions into 2022, the focus remains on bridging the talent gap through specialized academic programs and leveraging the return of large-scale physical exhibitions to maintain momentum in the evolving Metaverse and digital advertising spaces.
AppsFlyer · 2021
ReportThe African Mobile Apps Landscape (2021)
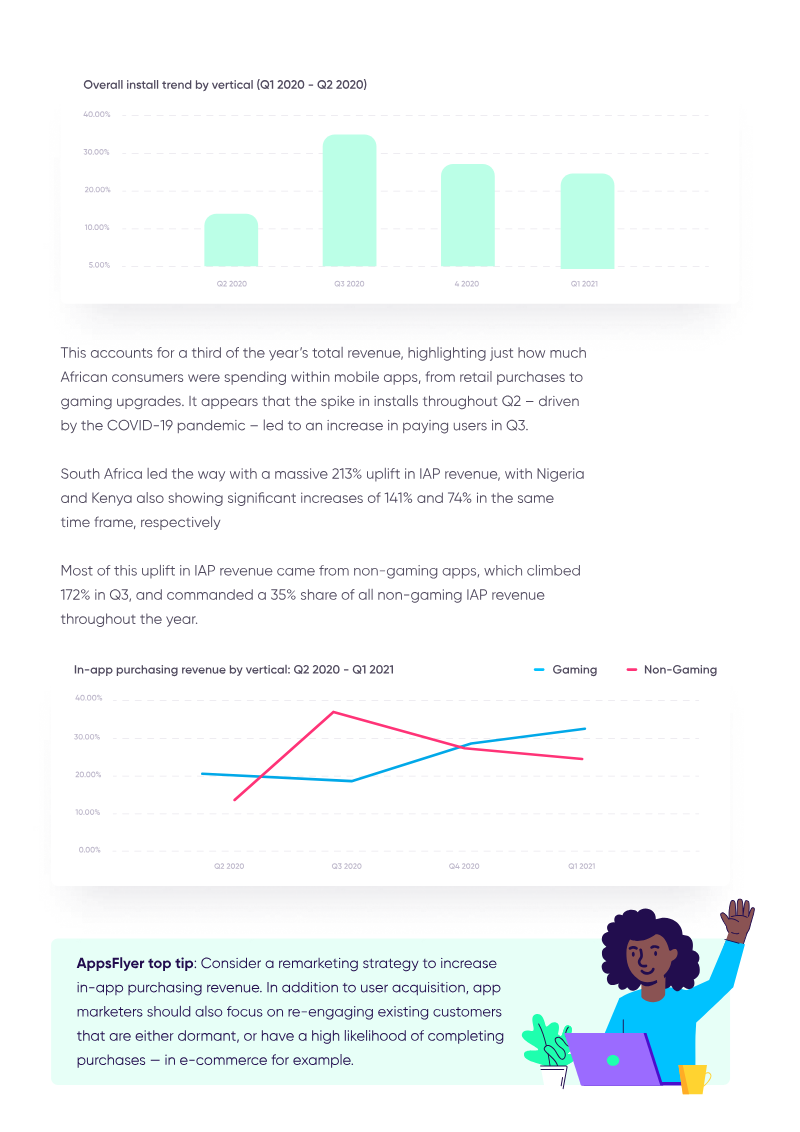
The African mobile app market experienced a period of rapid acceleration between Q1 2020 and Q1 2021, driven by a young, mobile-first population and the unique conditions of the COVID-19 pandemic. Analysis of 6,000 apps and 2 billion installs across South Africa, Nigeria, and Kenya reveals that overall app installs grew by 41% during this period. Nigeria led this growth with a 43% increase, while South Africa saw the most immediate surge in downloads following strict lockdown measures. The gaming sector proved particularly resilient, with installs jumping 50% in Q2 2020 as consumers sought home entertainment. This trend extended to monetization, as in-app advertising revenue surged by 167% between Q2 2020 and Q1 2021. Furthermore, in-app purchasing revenue peaked in Q3 2020, accounting for one-third of the year's total revenue. While Android remains the dominant platform with a 54% increase in non-organic installs, iOS also showed growth despite a 21% rise in cost-per-install. Several structural trends define the current landscape, including the rise of fintech apps addressing the needs of unbanked populations and the emergence of super apps that consolidate multiple services to overcome device storage limitations. Despite this progress, challenges remain regarding connectivity, as mobile internet adoption in Sub-Saharan Africa stands at 26%, well below the global average. To succeed, marketers are encouraged to move toward a multi-moment maturity model by integrating durable measurement foundations, focusing on high-value user acquisition, and utilizing remarketing strategies to drive long-term engagement.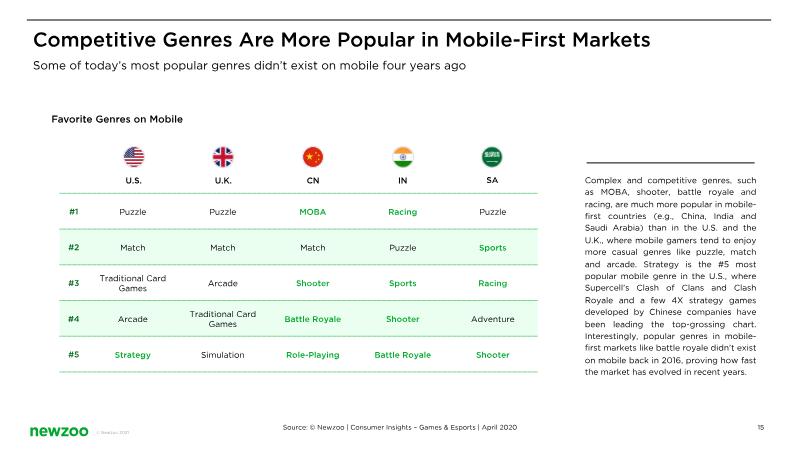
Newzoo · 2021
Report