Skip to main content
Game Industry
Library
Ask AI
Cited answers
Search…
⌘
K
Library
Search
TL;DR
Connect your AI
PRO
Browse
Topics
Collections
Writers
Glossary highlights
Theme
Help & info
Subscribe
Game Industry
Library
Library
TL;DR
Search
Ask AI
Saved
Collections
Asia-Pacific
Asia-Pacific
Japan, China, Korea, Southeast Asia, India and Australia.
321 documents
Reports
Presentations
Whitepapers
Newest first
Oldest first
Title A–Z
Title Z–A
CyberAgent
Report
1Q FY2023 Presentation Material
The presentation outlines CyberAgent’s strategic focus for FY2023, emphasizing a dual‑stream business model that blends advertising revenue with game development while expanding into media and digital content. Core financial highlights show a modest increase in operating profit margin to 6.7 % from 5.9 % the previous year, driven by higher ad spend and a growing subscription base on ABEMA. Operating profit rose to ¥6.4 billion, with revenue growth of 8.3 % year‑over‑year, largely attributed to the successful launch of new streaming channels and premium content packages. Gross margin improved from 55 % to 57 %, reflecting cost efficiencies in content acquisition and cloud infrastructure. Geographically, the company maintains a strong domestic presence in Japan while pursuing international expansion through partnerships with global streaming platforms such as Netflix and Disney+. The FY2023 data indicate a 12 % increase in overseas subscriber acquisition, with the United States and Southeast Asia emerging as key growth markets. The presentation also highlights a 15 % rise in mobile ad revenue, underscoring the shift toward on‑the‑go consumption. Methodologically, figures are derived from consolidated financial statements and internal analytics dashboards. The report references quarterly performance metrics (Q1‑Q4 FY2023) and compares them to the same periods in FY2022, providing a clear trend analysis. Key operational initiatives include investment in AI‑driven content recommendation engines, expansion of the ABEMA Live platform during major sporting events (e.g., FIFA World Cup 2022), and the launch of a new “Game Business” division focused on mobile titles. Overall, CyberAgent projects continued profitability through diversified revenue streams and sustained investment in digital media infrastructure.
CyberAgent
Report
2Q FY2023 Presentation Material: Japan
2Q FY2023 Presentation Material The future information, such as earnings forecast, written in this document is based on our expectations and assumptions as of the date the forecast was made. Our actual results could differ materially from those described in this forecast because of various 1. Financial Summary (January - March 2023) 3. Internet Advertisement Business 6. Medium to long-term strategy FY2023 Quarterly sales hit a new record high.
CyberAgent
Report
FY2023 Presentation Material
October 2022 to September 2023 The future information, such as earnings forecast, written in this document is based on our expectations and assumptions as of the date the forecast was made. Our actual results could differ materially from those described in this forecast because of various risks and uncertainties. 1. FY2023 Full Year Results (October 2022-September 2023) 2. FY2024 Forecast (October 2023-September 2024) 3. Internet Advertisement Business 6. Medium to Long-Term Strategy 7.
CyberAgent
Report
3Q FY2023 Presentation Material: Japan
3Q FY2023 Presentation Material The future information, such as earnings forecast, written in this document is based on our expectations and assumptions as of the date the forecast was made. Our actual results could differ materially from those described in this forecast because of various 1. Financial Summary<sub>(April-June 2023)</sub> 3. Internet Advertisement Business 6. Medium to long-term strategy FY2023 Media and Ads increased the sales.
CyberAgent
Report
1Q FY2024 Presentation Material
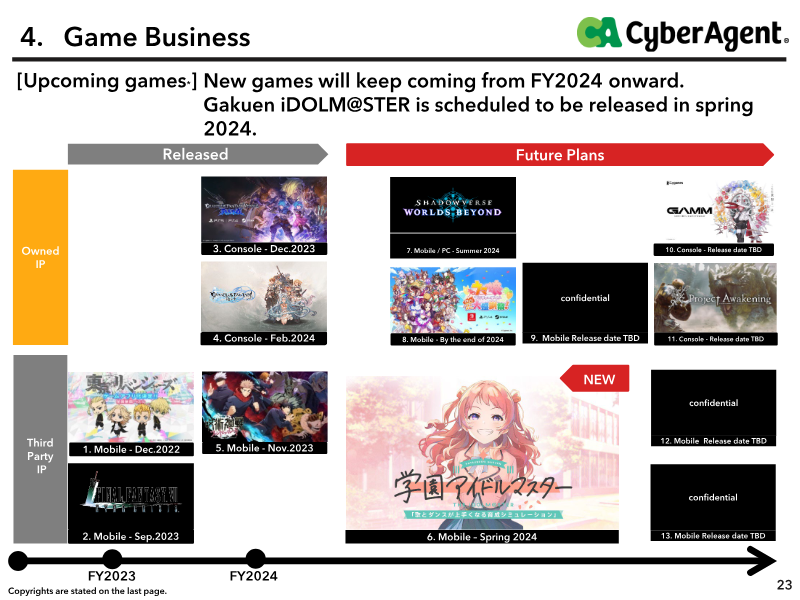
The presentation outlines CyberAgent’s fiscal‑year 2024 first‑quarter performance, emphasizing a robust rebound across its three core businesses—Internet advertising, media (ABEMA), and game development. Consolidated sales reached ¥193 billion, up 15.2 % year‑over‑year, while operating profit climbed to ¥6.28 billion, a 7.5‑point increase from the prior year’s loss. The advertising arm delivered ¥105.3 billion in revenue, up 10.1 % YoY, and an operating profit of ¥5.6 billion, reflecting a 13.3 % YoY gain and sustained improvement in operating‑margin efficiency (OPM). Media operations posted ¥42.7 billion, a 27.8 % YoY rise, though operating loss narrowed to ¥0.9 billion, driven by reduced losses in ABEMA‑related activities. Game sales hit ¥45.0 billion, up 10.1 % YoY and 6.5 % QoQ; operating loss fell to ¥3.4 billion, a 32.9 % YoY decline and 42.4 % QoQ improvement, thanks to a new hit title. Financial statements show total assets of ¥468.7 billion and shareholders’ equity of ¥129.0 billion, with cash deposits at ¥184.8 billion. SG&A expenses rose 8.1 % YoY to ¥43.7 billion, while headcount increased to 7,336 employees. Strategically, the company targets a “growth phase” with new digital ad platforms (e.g., ANA Moment Ads), continued investment in ABEMA, and a pipeline of high‑quality games such as “Jujutsu Kaisen Phantom Parade.” Forecasts indicate that FY2024 operating profit will reach ¥30 billion, with sales projected at ¥750 billion. The presentation stresses a commitment to enhancing monetization, AI‑driven advertising efficiency, and extending game lifecycles to secure long‑term profitability.
CyberAgent
Report
FY2024 Presentation Material: January to March 2024
The presentation outlines CyberAgent’s FY2024 performance, emphasizing record sales and operating profit growth across its three core businesses—Internet Advertising, Media (ABEMA), and Game. Consolidated sales reached ¥215.1 billion in Q2, up 10.0% YoY, while operating profit rose to ¥21.0 billion, a 12.2% increase and the first time surpassing ¥20 billion in eight quarters. Internet Advertising sales climbed 7.1% YoY to ¥107.3 billion, with operating profit up 19.6%. The Media segment achieved a new high of ¥42.0 billion in sales, up 25.8% YoY, and turned profitable for the first time since Q2 2023; operating profit increased 0.7 billion yen. Game sales grew 8.1% YoY to ¥67.1 billion, driven by the launch of “Granblue Fantasy: Relink,” which sold one million units within eleven days, and by anniversary events for major titles; operating profit surged 19.8% YoY. Financially, SG&A expenses increased modestly by 2.9%, while cash deposits and fixed assets grew significantly, reflecting investment in technology and talent. Net income attributable to shareholders rose 30.8% YoY to ¥10.3 billion, offset by a temporary extraordinary loss. The company’s strategy focuses on leveraging generative AI and large‑language models (CyberAgentLM) to enhance ad creative, expand ABEMA’s sports content through partnerships with DAZN and WOWSPO, and sustain game revenue by launching new titles such as “Granblue Fantasy Versus” and “Umamusume Pretty Derby.” The overarching goal is to increase sales and profits, with FY2023 operating profit as a low point, and to position CyberAgent as a global digital media and technology leader.
CyberAgent
Report
FY2024 Presentation Material: October 2023 to September 2024
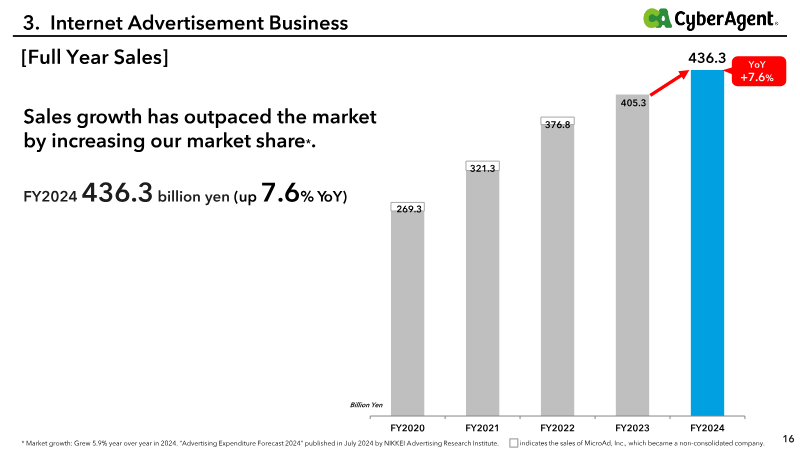
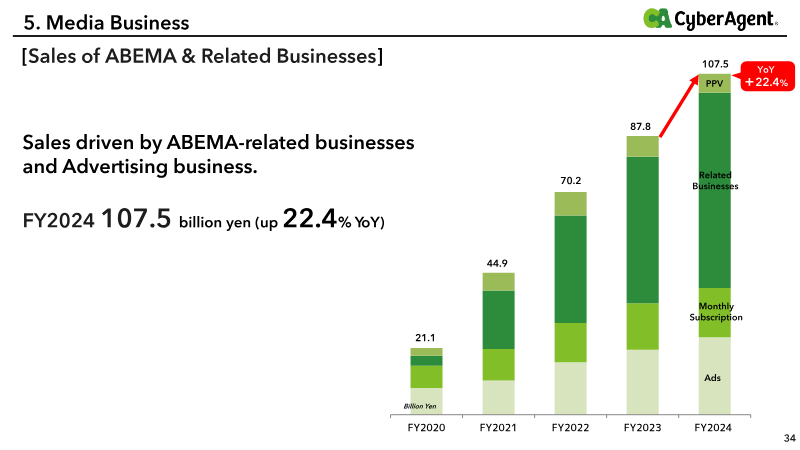
October 2023 to September 2024 The future information, such as earnings forecast, written in this document is based on our expectations and assumptions as of the date the forecast was made. Our actual results could differ materially from those described in this forecast because of various risks and uncertainties. 1. FY2024 Full Year Results (October 2023 -September 2024) 2. FY2025 Forecast (October 2024 -September 2025) 3. Internet Advertisement Business 6. Medium to Long-Term Strategy 7.
CyberAgent
Report
2Q FY2025 Financial Presentation Material
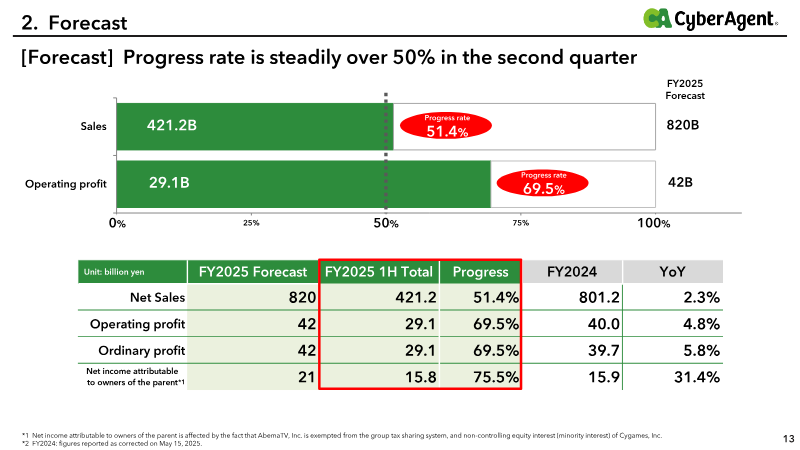
2Q FY2025 Presentation Material We corrected past annual securities reports and others due to the discovery of an inappropriate accounting treatment at the consolidated subsidiary. Please refer to the “Notice on Submission of Correction Reports of Past Annual Securities Reports and Amendments of Financial Statements for Past Fiscal Years” released on May 15, 2025, for details.
CyberAgent
Report
1Q FY2025 Presentation Material
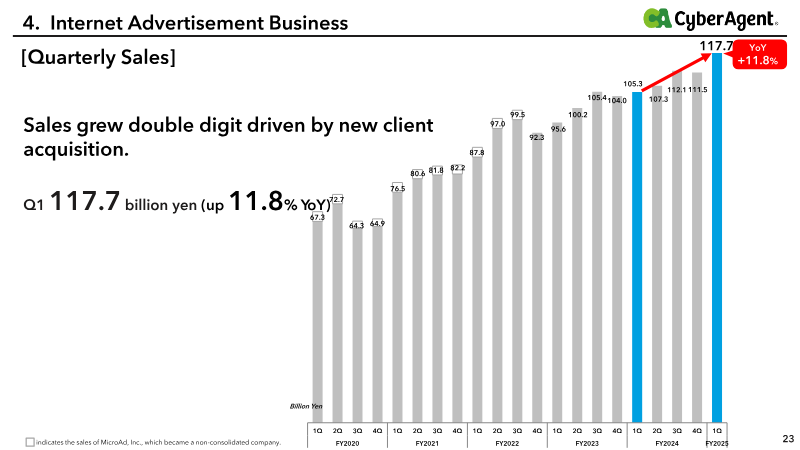
The presentation outlines CyberAgent’s FY 2025 financial outlook, operational highlights, and strategic priorities across its Media & IP, Internet Advertising, and Game divisions. FY 2025 revenue is projected at ¥820 billion with operating profit of ¥42 billion, representing 24.9 % and 19.8 % of the year‑to‑date targets, respectively. First‑quarter results show a 5.6 % YoY sales increase to ¥203.8 billion and a 32.1 % rise in operating profit to ¥8.3 billion, driven largely by a 10.5 % lift in Media & IP sales (¥55.6 billion) and an 11.8 % growth in Internet Advertising sales (¥117.7 billion). The Game segment, however, posted a 15.1 % YoY decline to ¥38.2 billion and a 4.1 % drop in operating profit, attributed to slower releases despite strong performance of new titles. Operating margins improved from 3.3 % in FY 2024 to 4.1 % in FY 2025, supported by a 32 % increase in operating income. SG&A expenses rose 4.4 % YoY to ¥45.7 billion, while cash deposits increased 11.3 % YoY to ¥205.6 billion, reflecting liquidity strengthening. Strategically, the company is shifting from a Media‑only model to an integrated Media & IP business, aiming to generate global IPs through ABEMA and new production units such as CA Soa Inc. The medium‑to‑long‑term plan emphasizes investment in high‑profit IP content, game development, and advertising technology leveraging AI to enhance ad effectiveness. The presentation also lists a pipeline of over six new games for FY 2025, including international releases, and outlines organizational changes to support the expanded IP focus.
CyberAgent
Report
Quarterly Transition by Business Segment: Japan
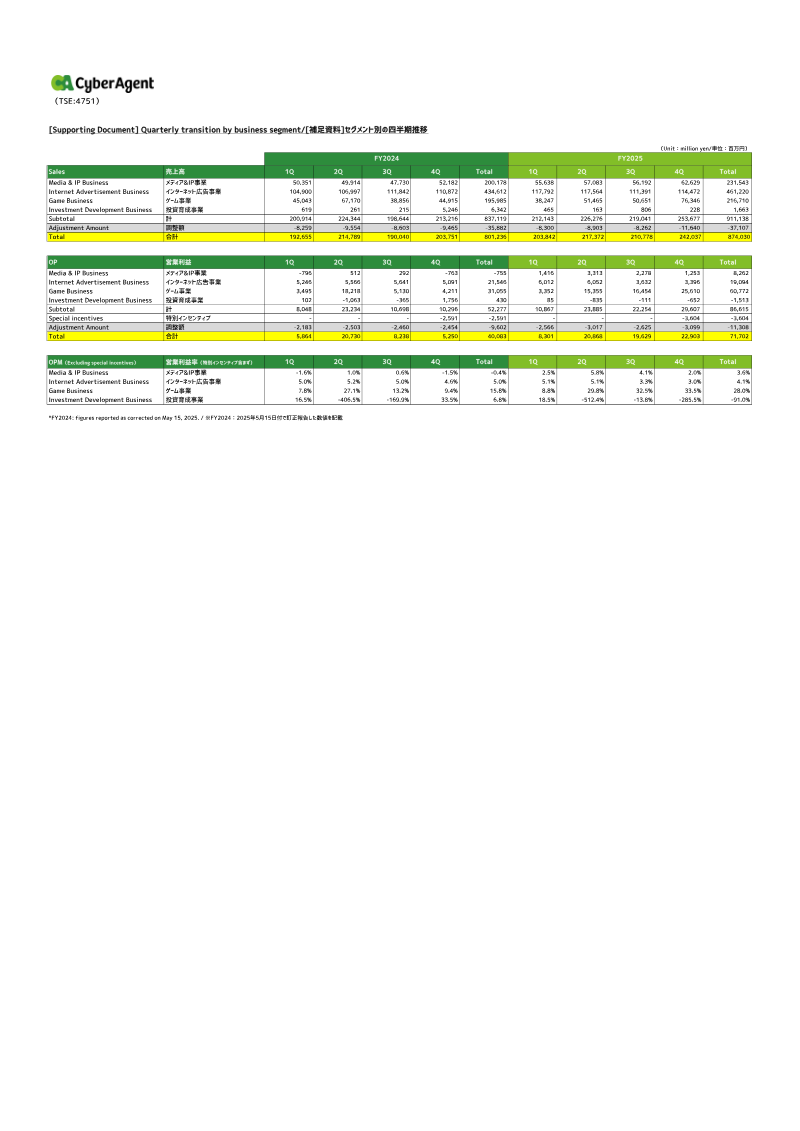
The quarterly transition analysis for Japan’s business segments presents detailed financial performance for FY2024 and FY2025, focusing on Media & IP, Internet Advertisement, Game, and Investment Development divisions. Sales figures reveal that the Internet Advertisement Business consistently leads with a FY2024 total of ¥434,612 million and a FY2025 total of ¥461,220 million. The Game Business shows the most volatility, peaking in Q2 FY2024 at ¥67,170 million before declining to ¥38,856 million in Q3. Media & IP sales remain relatively stable around ¥50–52 billion per quarter, while Investment Development remains a minor contributor with totals under ¥7 billion. Operating profit (OP) highlights divergent profitability across segments. The Game Business delivers the highest OP, reaching ¥31,055 million in Q1 FY2024 and sustaining strong quarterly results thereafter. Internet Advertisement maintains steady OP around ¥5–6 billion each quarter, whereas Media & IP oscillates between losses and modest gains, culminating in a FY2024 total OP of ¥8,262 million. Investment Development experiences significant swings, with a notable loss in Q2 FY2024 but a recovery to ¥1,756 million in Q4. Operating profit margins (OPM) excluding special incentives illustrate segment efficiency. Game Business achieves the highest margin, peaking at 33.5% in Q3 FY2024 and maintaining a FY2025 average of 28%. Internet Advertisement sustains margins around 5%, while Media & IP remains near break‑even, fluctuating between –1.6% and 5.8%. Investment Development shows extreme volatility, with a negative margin of –406.5% in Q2 FY2024 and a positive 33.5% in Q4, resulting in an overall FY2024 margin of 3.6%. The data cover the Japanese market over two fiscal years, with quarterly granularity and corrections applied as of May 15 2025. The analysis relies on internal financial statements, presenting a comprehensive view of segment performance and profitability trends.
CyberAgent
Report
Presentation Material: Q1 FY2026
The future information, such as earnings forecast, written in this document is based on our expectations and assumptions as of the date the forecast was made. Our actual results could differ materially from those described in this forecast because of various risks and uncertainties. 1. Summary (October - December 2025) 4. Internet Advertisement Business 6.
Bushiroad
Report
Financial Report for First Two Quarters: Fiscal 2026
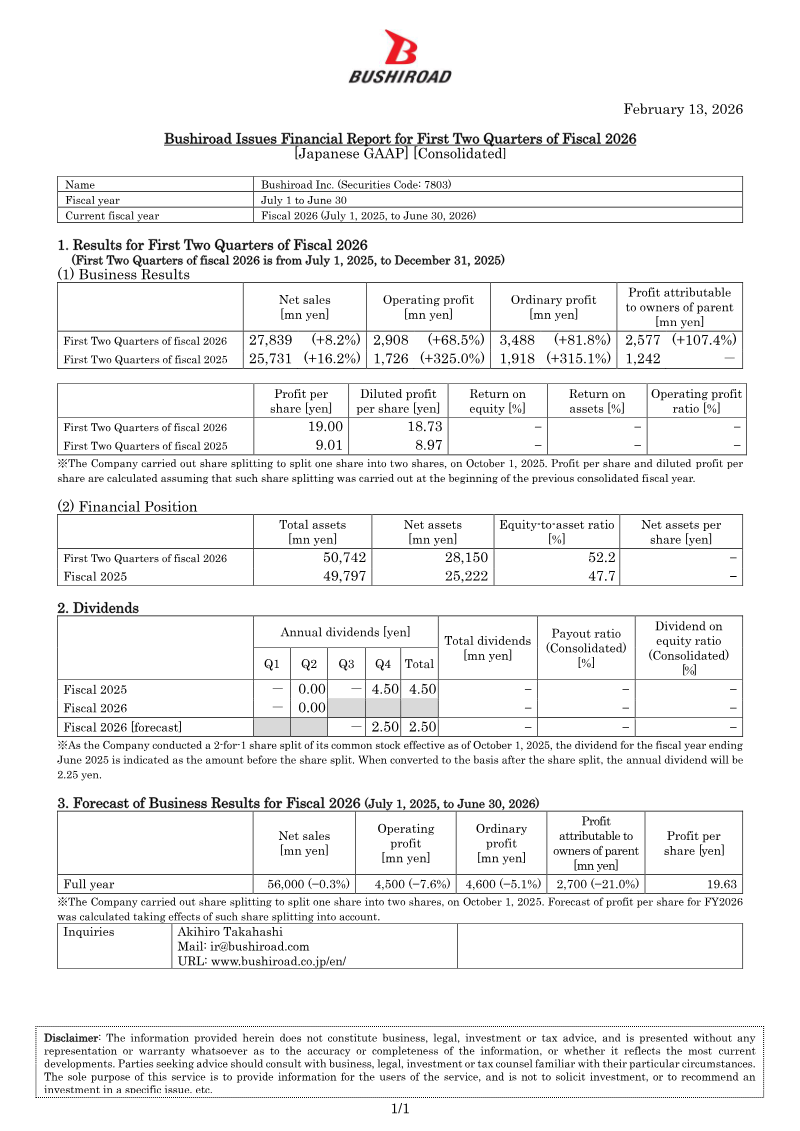
Bushiroad Inc. reports consolidated financial results for the first two quarters of fiscal 2026 (July 1–December 31, 2025). Net sales rose 8.2 % to ¥27,839 million, while operating profit increased 68.5 % to ¥2,908 million and ordinary profit grew 81.8 % to ¥3,488 million; profit attributable to owners of the parent company surged 107.4 % to ¥2,577 million. Earnings per diluted share reached ¥19.00, a significant jump from ¥9.01 in the same period of fiscal 2025, reflecting both higher profitability and a 2‑for‑1 share split executed on October 1, 2025. Total assets expanded to ¥50,742 million and net assets climbed to ¥28,150 million, raising the equity‑to‑asset ratio from 47.7 % to 52.2 %. The company’s dividend policy for fiscal 2025 included a ¥4.50 million payout, while no dividends were declared in the first half of fiscal 2026; a forecast for the full year projects no dividend distribution. For the full fiscal year 2026, Bushiroad forecasts net sales of ¥56,000 million (a slight decline of 0.3 % from the prior year), operating profit of ¥4,500 million (down 7.6 %), ordinary profit of ¥4,600 million (down 5.1 %), and profit attributable to the parent of ¥2,700 million (down 21.0 %). Earnings per share are projected at ¥19.63, adjusted for the share split. These figures cover Bushiroad’s domestic Japanese operations under Japanese GAAP, with the fiscal year running from July 1 to June 30. The report relies on consolidated financial statements and includes a forward‑looking forecast based on current management expectations.
Previous
1
…
4
5
6
…
27
Next