A significant, accidental disclosure of confidential Microsoft internal documents has provided an unprecedented look into the company’s long-term Xbox strategy through 2030. The leak, which occurred during preparations for a legal proceeding involving the Federal Trade Commission, exposed sensitive internal communications and strategic roadmaps that were intended to remain private. These materials reveal a decade-long vision for the gaming division, highlighting the inherent tension between the industry’s need for long-term secrecy and the reality of modern, high-stakes corporate operations.
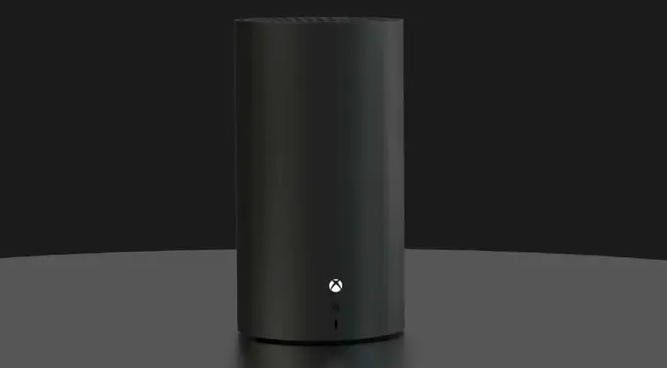
The leaked data covers three primary areas: hardware development, software pipelines, and internal business negotiations. Hardware plans include a digital-only refresh of the Xbox Series X, a new iteration of the Series S, a redesigned controller, and a next-generation console launch targeted for 2028, which will be supported by a hybrid cloud architecture. Software disclosures detail previously unannounced titles from Bethesda, including a third installment in the Dishonored series, a new Doom entry, and various remasters. Furthermore, the cache contains unredacted emails detailing internal discussions regarding potential acquisitions, such as Nintendo, and specific financial strategies for securing Game Pass exclusivity for high-profile titles.
This incident represents a major public relations challenge for the company, as it effectively removes the element of surprise typically maintained to protect competitive advantages and manage consumer expectations. Because the leak originated from an internal administrative error rather than an external breach, the company has little recourse to mitigate the fallout. Ultimately, the exposure provides a rare, transparent view into the long-term planning cycles of a major platform holder, offering a definitive look at the company’s operational playbook for the remainder of the decade.
The video game industry experienced significant turmoil in September 2023 following Unity’s announcement of a new, controversial pricing structure. The company, which provides a widely used game engine accounting for approximately 30% of the market, introduced a "Runtime Fee" based on game installations. This policy, scheduled for implementation in January 2024, proposed charging developers $0.20 per install once a title surpassed $200,000 in revenue or 200,000 total installs within a 12-month period, with a sliding scale for larger professional tiers.
The announcement triggered an immediate and widespread backlash from the global development community. Critics characterized the move as a "bait and switch," arguing that the new fees were implemented without industry consultation and threatened the commercial viability of various business models, particularly free-to-play and hyper-casual games. Developers expressed concerns regarding the lack of transparency in how Unity intended to track and verify installs, as well as the potential for the fees to disproportionately impact independent studios and projects in developing markets.
Unity’s attempt to justify the policy as a necessary evolution of its business model failed to quell the unrest, leading to a significant erosion of trust among its user base. While the company subsequently attempted to clarify the policy by suggesting potential exemptions for demos, charity titles, and fraudulent installs, the incident severely damaged its reputation as a pillar of the games industry. The situation serves as a case study in the risks of imposing unilateral, poorly communicated pricing changes on a sensitive ecosystem, ultimately forcing the company to confront the potential for long-term reputational and commercial fallout.
The release of Bethesda’s Starfield serves as a critical inflection point for Microsoft’s broader video game strategy. Following the $7.5 billion acquisition of ZeniMax Media in 2021, Microsoft positioned the title as a flagship exclusive intended to drive both console hardware sales and subscriptions to its Game Pass service. The game’s performance is viewed as a litmus test for whether Microsoft’s ecosystem-focused model—which prioritizes flexible content access across cloud and hardware platforms—can effectively compete against the traditional, exclusive-driven strategies employed by rivals like Sony and Nintendo.
Microsoft currently faces significant headwinds, including hardware sales that have lagged behind competitors and internal challenges regarding the performance of the Xbox Series S, which has forced developers to scale back technical ambitions. Furthermore, increased regulatory scrutiny regarding the acquisition of Activision Blizzard has constrained Microsoft’s ability to expand its first-party studio roster through further mergers. Consequently, the company’s vision of a unified, borderless gaming ecosystem risks appearing diluted compared to the more focused, high-spec offerings of its competitors.
The long-term success of Starfield may dictate a strategic pivot for Microsoft. If the title succeeds, it could validate the viability of the subscription-based, low-friction access model. Conversely, a lackluster performance might compel the company to re-evaluate its reliance on such services and return to a strategy centered on high-profile, tent-pole releases. Ultimately, the game represents a pivotal moment in determining whether Microsoft can successfully transition to a cloud-led, platform-agnostic future or if it must revert to more conventional industry practices to maintain market relevance.
The Video Games Industry Memo serves as a weekly newsletter designed to bridge the gap between specialized industry insiders and a broader, non-specialist audience. Published by George E. Osborn, the initiative aims to provide accessible, conversational, and informative analysis of the business and political mechanics underpinning the global video games sector. By synthesizing complex industry developments into a digestible format, the publication seeks to address a perceived market void where existing trade outlets are often too technical for outsiders, while mainstream media coverage frequently lacks the necessary depth.
The publication’s content strategy focuses on a weekly deep dive into a dominant industry story, supplemented by curated news, professional development resources, and summaries of notable game releases. This approach is informed by the author’s professional background in communications, which highlighted a consistent demand from government officials, charities, and corporate stakeholders for clear, educational content regarding the inner workings of the gaming industry. The newsletter operates on a model that prioritizes clarity and utility, aiming to make the creative and commercial complexities of the sector understandable to those outside the immediate development ecosystem.
Currently, the project is in a growth phase, transitioning from a semi-private beta to a broader public launch. Future development plans include expanding the subscriber base and exploring a potential paid subscription tier by mid-2024. The initiative remains focused on establishing a sustainable, credible, and engaging platform that serves as a primary resource for those seeking to understand the strategic and political landscape of the video games industry.
The United Kingdom’s Competition and Markets Authority (CMA) has initiated a new Phase 1 investigation into a restructured proposal for Microsoft’s acquisition of Activision Blizzard. This development follows the regulator's initial rejection of the merger, which had left the UK authority isolated from the international consensus that largely favored the deal. The revised proposal introduces Ubisoft as an independent third-party guarantor, granting the company rights to manage cloud gaming access for existing and future Activision Blizzard content for the next 15 years, excluding the European Economic Area.
This structural change serves as a strategic compromise for both parties. For Microsoft, the divestment of cloud gaming rights addresses the CMA’s primary regulatory concerns regarding long-term enforcement and oversight. For the CMA, the new proposal provides a face-saving mechanism to approve the acquisition while maintaining its public stance that its initial intervention was necessary. The regulator has set an October 18 deadline for the completion of this investigation.
While the CMA has cautioned that the re-examination does not guarantee approval, industry analysis suggests the deal is likely to proceed. The inclusion of Ubisoft as a neutral administrator effectively mitigates the regulatory friction that previously stalled the acquisition. By shifting the responsibility of cloud rights management, Microsoft has cleared a significant hurdle, signaling a likely conclusion to the prolonged regulatory saga. This shift reflects a broader trend of increased scrutiny over cloud gaming competition and the evolving role of third-party intermediaries in large-scale industry mergers.
Recent academic research indicates that government-mandated play time limits in China have failed to curb gaming among minors. A study led by Dr. David Zendle of the University of York, which analyzed data from 2.4 billion players provided by the game engine Unity, found no credible evidence that these restrictions reduced playtime. In fact, the data showed that playtime among heavy users—those playing more than four hours per day—remained stable or increased slightly in the year following the implementation of the regulations.
The study attributes this lack of efficacy to the inherent difficulties of enforcement and the ease with which users can circumvent restrictions. While the Chinese government focused its regulatory efforts on major market players like Tencent, a vast ecosystem of independent developers remained largely ungoverned. This allowed players to migrate to unregulated digital spaces, effectively bypassing the intended controls. Furthermore, players frequently utilized technical workarounds, such as VPNs, or interpersonal methods to maintain access to their accounts.
Despite these findings, the Chinese government has signaled its intent to maintain and potentially expand screen time limits. Beyond the specific context of China, the research serves as a broader critique of top-down digital policy, suggesting that such measures are often ineffective and may lead to unintended consequences. The analysis advocates for an evidence-based approach to industry regulation, encouraging stakeholders to share data to foster policies that reflect the actual realities of gaming behavior rather than relying on public perception or moral concerns.
The global video games market is currently experiencing a period of renewed growth, with projections indicating a trajectory toward a $200 billion valuation within the next five years. According to the 2023 Newzoo Global Games Market Report, the industry has reached a total valuation of $187.7 billion. This represents a 2.8% increase over the $182 billion recorded in 2022, signaling a recovery following the post-pandemic market correction.
Several key factors are driving this upward momentum. The easing of hardware supply chain constraints, which had persisted since 2020, has allowed manufacturers to meet consumer demand for consoles and PCs more effectively. Furthermore, the industry is benefiting from a robust release slate, as titles previously delayed by pandemic-related development challenges have finally reached the market. Beyond hardware and software sales, companies are successfully diversifying revenue streams through service-based models, intellectual property extensions, and cross-platform integration.
While the broader industry outlook remains positive, performance varies by company. Organizations that have struggled to align with current market trends—such as those facing significant release delays or declining hardware momentum—have experienced financial headwinds. However, the overall forecast remains optimistic, as the global player base continues to expand and the sector recovers from the volatility of the pandemic era. The data suggests that as the industry moves past these transitional challenges, the combination of increased accessibility and a steady pipeline of major releases will sustain long-term growth.