Report3 pages
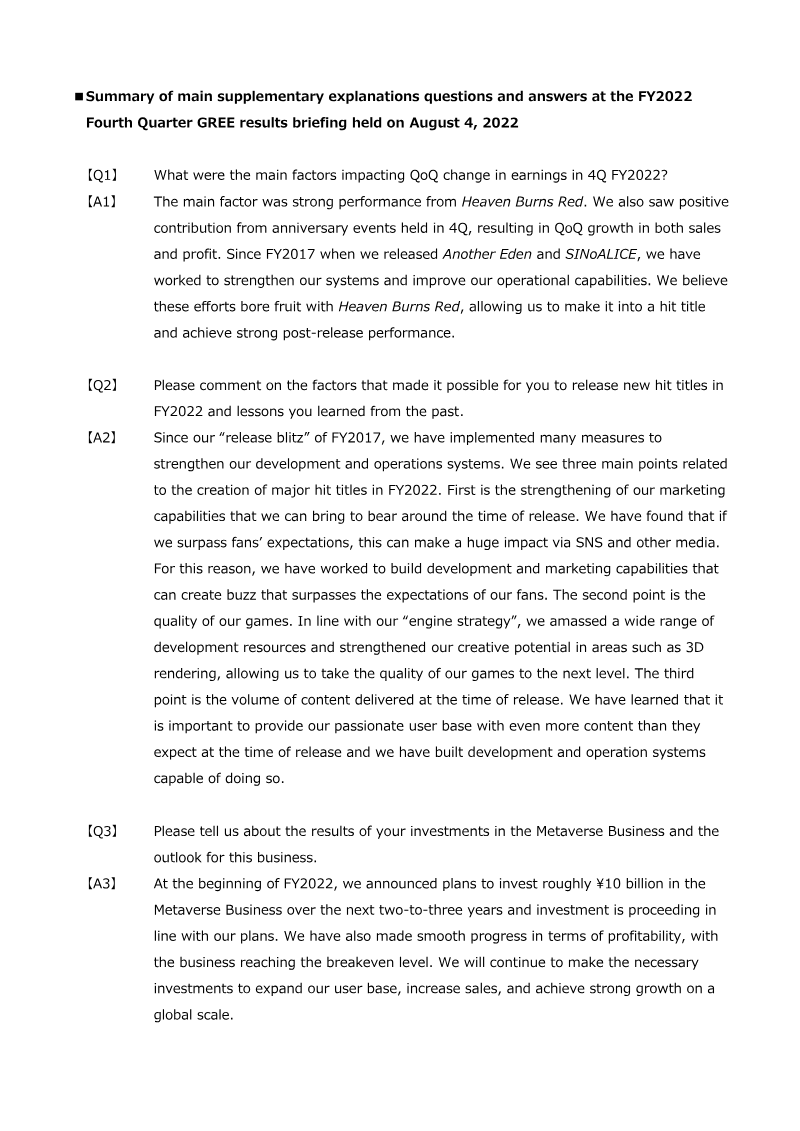
Summary of main supplementary explanations questions and answers at the FY2022 Fourth Quarter GREE results briefing held on August 4, 2022
The briefing focused on GREE’s financial performance and strategic initiatives for FY2022, highlighting the strong contribution of new titles such as Heaven Burns Red and anniversary events to quarter‑over‑quarter earnings growth. The company attributed this success to a “release blitz” strategy launched in FY2017, which has since strengthened marketing, game quality through an engine‑centric approach, and content volume at launch. These measures have enabled the company to exceed fan expectations, generate significant social media buzz, and deliver high‑quality 3D rendering.
Investment in the Metaverse Business is progressing as planned, with a ¥10 billion allocation over two to three years and the business reaching breakeven. GREE intends to continue expanding its global user base and sales through further investment. The DX Business is being restructured to integrate marketing support services, creating a data‑driven platform that offers comprehensive digital transformation solutions to corporate clients. Meanwhile, the Manga Business is introduced as part of a broader media diversification strategy aimed at leveraging first‑party IP across games, anime, and manga to broaden user engagement channels.
The Investment and Incubation Business is expected to provide stable medium‑to‑long‑term earnings, with a target return on investment of 10 % or higher. For FY2023 Q1, operating income in the Internet and Entertainment segment is projected at ¥1.0–¥1.5 billion, reflecting a decline from the strong performance of new titles and anniversary events in FY2022 while anticipating continued system‑strengthening investments.
- GREE’s FY2022 Q4 earnings growth was driven by the successful launch of Heaven Burns Red and high-performing anniversary events, validating a 'release blitz' strategy focused on high-quality 3D rendering and marketing.
- The company has allocated ¥10 billion over two to three years to its Metaverse business, which has currently reached a breakeven point as it seeks to expand its global user base.
- Operating income for the Internet and Entertainment segment is projected to decline to ¥1.0–¥1.5 billion in FY2023 Q1, reflecting a normalization after the peak performance of new titles in FY2022 and ongoing system investments.
- The Investment and Incubation business is positioned for medium-to-long-term stability with a target return on investment of 10% or higher.
- GREE is diversifying its media strategy by leveraging first-party IP across games, anime, and manga to increase user engagement channels.
+2
GREE
Report2 pages
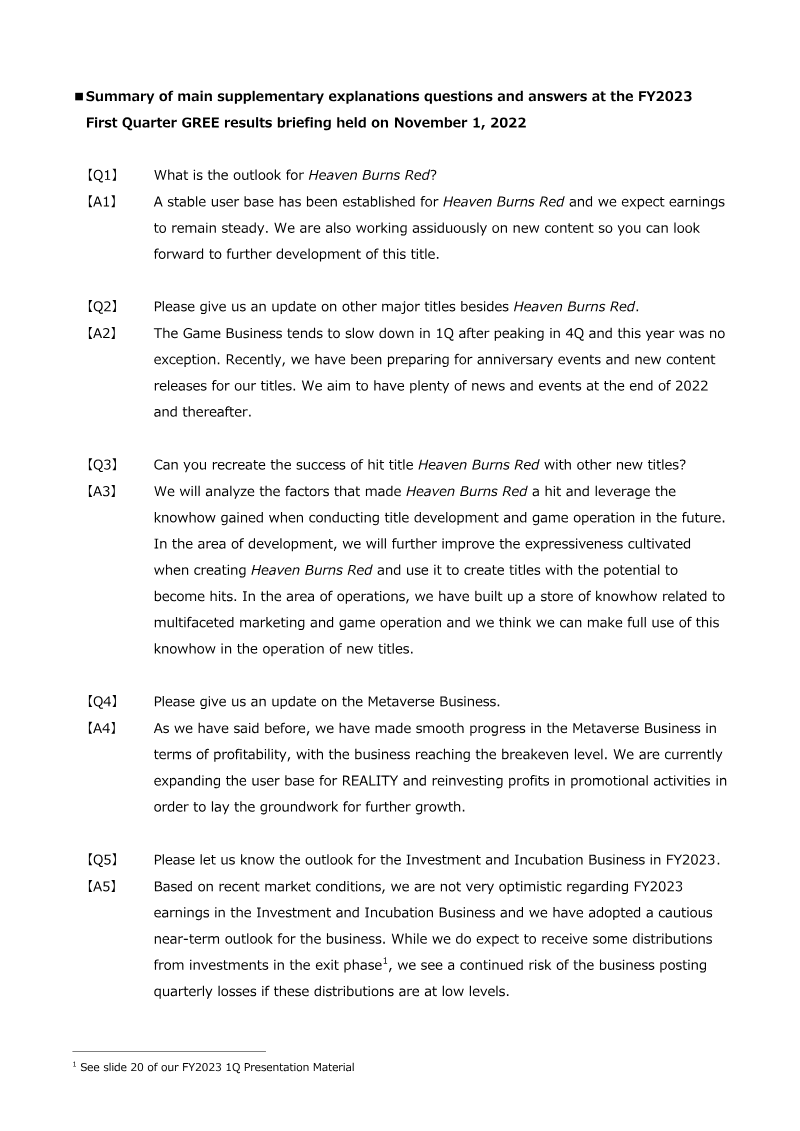
Summary of Main Supplementary Explanations Questions and Answers: FY2023 First Quarter GREE Results Briefing
The briefing outlines GREE’s strategic outlook and performance expectations for FY2023, focusing on its core gaming, metaverse, and investment activities. The company reports a stable user base for the flagship title “Heaven Burns Red,” anticipating steady earnings while continuing to develop new content. Other major titles are expected to experience a typical first‑quarter slowdown after a fourth‑quarter peak, with the company preparing anniversary events and content releases to sustain engagement through late 2022 and beyond.
GREE plans to replicate the success of “Heaven Burns Red” by applying lessons learned in development and operations to future titles, emphasizing expressive design and multifaceted marketing know‑how. In the metaverse segment, profitability has reached breakeven; the firm is expanding its user base for REALITY and reinvesting profits into promotional activities to support further growth.
The investment and incubation arm faces a cautious outlook for FY2023, with potential quarterly losses if exit distributions remain low despite some expected payouts. For the Internet and Entertainment Business, operating income for Q2 FY2023 is projected between ¥1.0 billion and ¥1.5 billion, reflecting moderate growth expectations amid market uncertainties.
Overall, GREE’s strategy centers on leveraging proven game development expertise, expanding metaverse user engagement, and managing investment risks while targeting modest income growth in its entertainment portfolio.
- GREE projects operating income for the Internet and Entertainment Business to reach between ¥1.0 billion and ¥1.5 billion in Q2 FY2023.
- The flagship title 'Heaven Burns Red' maintains a stable user base, with the company leveraging its development and marketing lessons from this game to inform future title releases.
- The metaverse segment, anchored by the platform REALITY, has reached a breakeven point and is currently reinvesting profits into promotional activities to scale its user base.
- Major game titles are expected to face a typical Q1 seasonal slowdown following a Q4 peak, with management planning anniversary events and content updates to drive engagement through late 2022.
- The investment and incubation arm faces a cautious outlook for FY2023, with the potential for quarterly losses if exit distributions remain low.
+2
GREE
Report2 pages
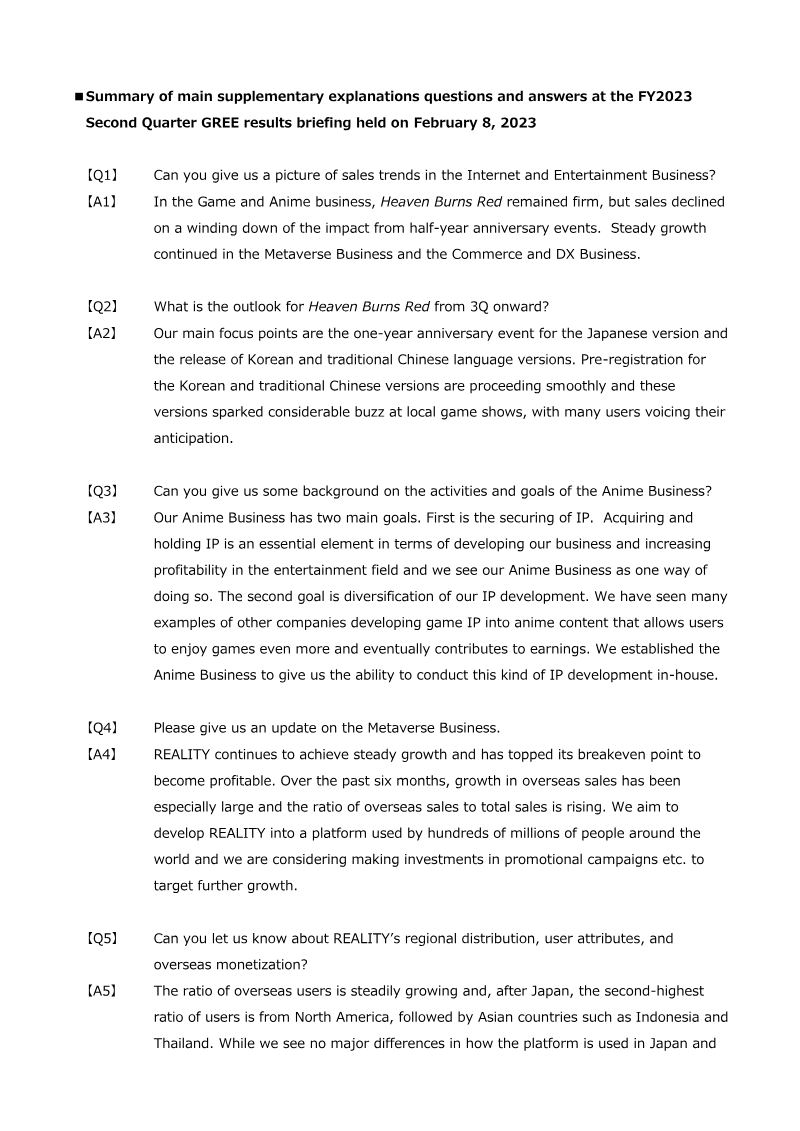
Summary of Main Supplementary Explanations Questions and Answers: FY2023 Second Quarter
The briefing outlines GREE’s performance and strategic outlook for the second quarter of FY2023, focusing on its Internet and Entertainment Business. Sales in the Game and Anime segment remained steady for “Heaven Burns Red,” though revenue tapered after the half‑year anniversary promotion; growth continued in Metaverse and Commerce & DX divisions. The company anticipates a one‑year anniversary event for the Japanese version of Heaven Burns Red and imminent releases in Korean and traditional Chinese, with pre‑registrations already generating significant buzz at local game shows. The Anime Business is positioned to secure and diversify intellectual property, enabling in‑house development of game‑to‑anime adaptations that can enhance user engagement and revenue.
Metaverse operations, branded as REALITY, have surpassed the break‑even point and achieved profitability. Over the past six months, overseas sales grew markedly, with North America leading after Japan, followed by Indonesia and Thailand. User demographics skew female and Generation Z, with a strong preference for private communication features. Monetization streams—live‑stream gifting, avatar sales, and in‑game purchases—are expanding consistently across regions.
Advertising spend is expected to rise in the third quarter, driven by anniversary events and new language releases for Heaven Burns Red, as well as intensified promotion of REALITY. Operating income projections for the Internet and Entertainment Business in Q3 FY2023 range from ¥1.0 billion to ¥1.5 billion, contingent on the performance of the Korean and Chinese versions.
The Investment and Incubation Business remains cautious, with potential short‑term losses anticipated due to market conditions. However, diversified investment timing and targets are projected to stabilize contributions over the medium‑to‑long term.
- GREE projects Q3 FY2023 operating income for its Internet and Entertainment Business to range between ¥1.0 billion and ¥1.5 billion, heavily dependent on the performance of new Korean and traditional Chinese releases of 'Heaven Burns Red'.
- The 'REALITY' metaverse platform has achieved profitability, with significant overseas growth led by North America, followed by Indonesia and Thailand.
- GREE is scaling marketing spend in Q3 to support the one-year anniversary of 'Heaven Burns Red' and the international expansion of the 'REALITY' platform.
- The 'REALITY' user base is primarily composed of Gen Z females who prioritize private communication features, driving consistent monetization through gifting, avatar sales, and in-game purchases.
- The Anime Business is shifting toward an in-house model to develop game-to-anime adaptations, aiming to diversify intellectual property and increase long-term user engagement.
+4
GREE
Report2 pages
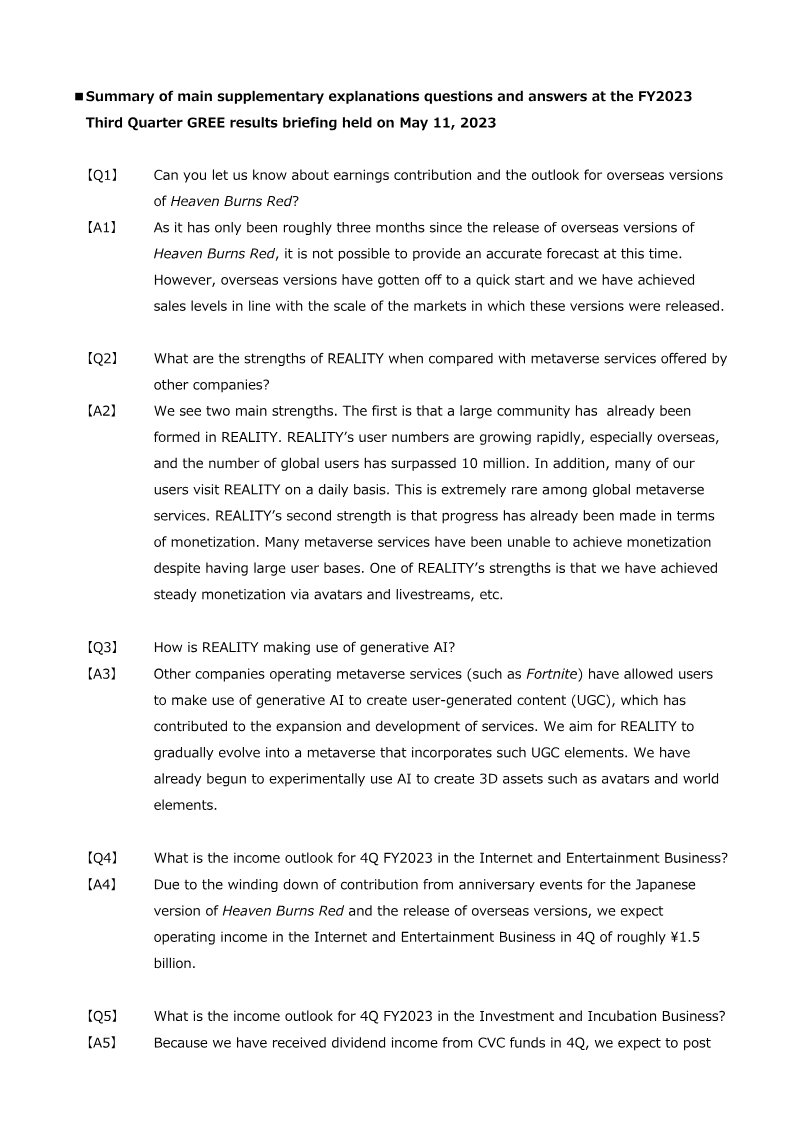
FY2023 Third Quarter GREE Results Briefing: Summary of Supplementary Explanations
The briefing clarifies GREE’s financial outlook and strategic positioning for FY2023, focusing on the third quarter results. It reports that overseas releases of “Heaven Burns Red” have begun to generate sales consistent with market size, though a precise forecast remains unavailable due to the short time frame. In the Internet and Entertainment segment, operating income for Q4 is projected at approximately ¥1.5 billion, reflecting a decline from the Japanese version’s anniversary event contributions but offset by overseas expansion.
The company highlights its metaverse platform, REALITY, as a key growth driver. REALITY boasts over 10 million global users, with daily engagement rates that surpass many competitors, and has achieved steady monetization through avatar sales and livestreaming. GREE plans to enhance the platform with generative AI, enabling user‑generated 3D content such as avatars and world elements, mirroring approaches seen in other metaverse services.
For the Investment and Incubation Business, Q4 operating income is expected to reach roughly ¥0.5 billion, largely supported by dividend receipts from corporate venture capital funds. Overall, the briefing underscores GREE’s focus on expanding overseas markets, monetizing its metaverse ecosystem, and leveraging AI to sustain growth across its entertainment and investment portfolios.
- GREE’s metaverse platform, REALITY, has surpassed 10 million global users and maintains high daily engagement rates through avatar sales and livestreaming.
- The Internet and Entertainment segment projects Q4 operating income of approximately ¥1.5 billion, balancing the decline of domestic anniversary event revenue with new overseas expansion.
- GREE is integrating generative AI into the REALITY platform to facilitate user-generated 3D content, including avatars and world elements.
- The Investment and Incubation Business is expected to generate ¥0.5 billion in Q4 operating income, primarily driven by dividend receipts from corporate venture capital funds.
- Overseas releases of 'Heaven Burns Red' are currently generating sales consistent with market expectations, though long-term forecasts remain pending due to the limited duration since launch.
+3
GREE
Report2 pages
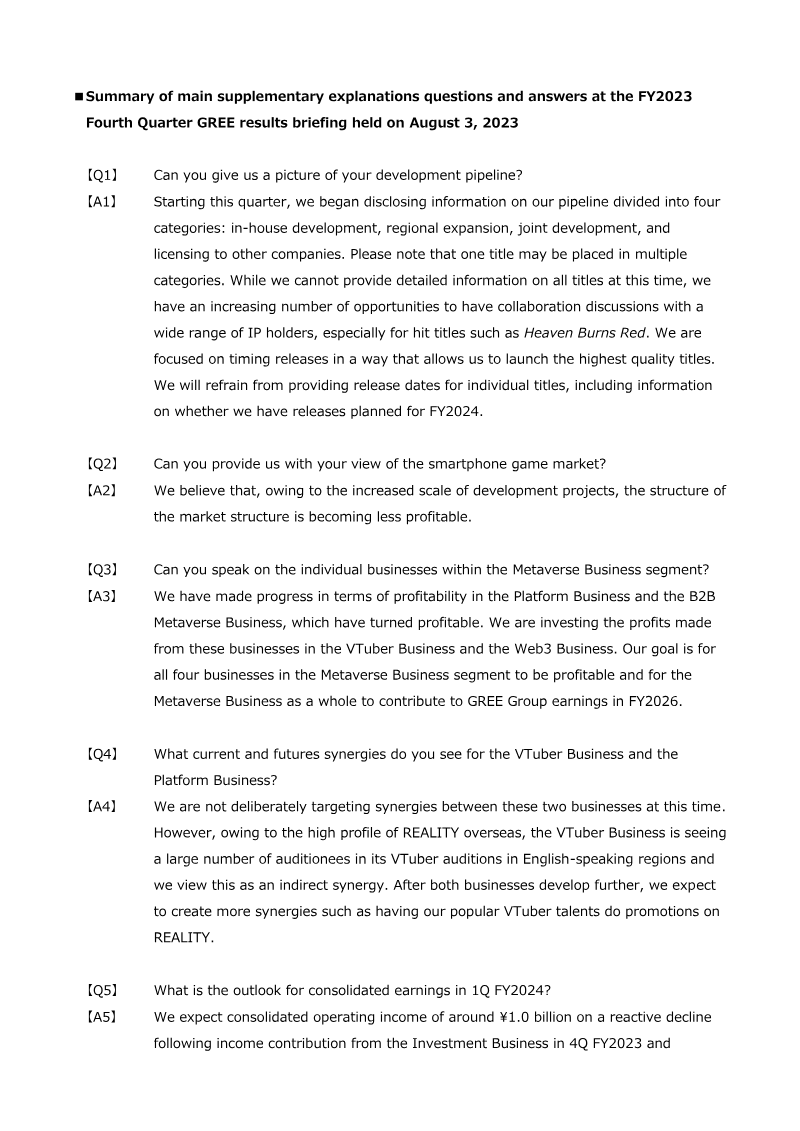
Summary of Main Supplementary Explanations Questions and Answers: FY2023 Fourth Quarter
The briefing outlines GREE’s strategic direction for FY2023‑FY2026, emphasizing a diversified portfolio beyond core gaming. In the fourth quarter, the company began categorizing its development pipeline into in‑house, regional expansion, joint development, and licensing, noting increased collaboration prospects with major IP holders such as Heaven Burns Red. Release dates remain undisclosed for FY2024 titles, reflecting a focus on quality over speed.
GREE views the smartphone game market as increasingly less profitable due to larger development scales, prompting a shift toward higher‑margin ventures. Within the Metaverse Business segment, Platform and B2B sub‑segments have achieved profitability; profits are being reinvested into the VTuber and Web3 businesses. The company aims for all four Metaverse sub‑segments to be profitable by FY2026, contributing significantly to group earnings.
Synergies between the VTuber and Platform businesses are currently indirect, driven by international talent recruitment for REALITY. Future cross‑promotions are anticipated once both units mature.
Financial outlooks indicate a consolidated operating income of approximately ¥1.0 billion for Q1 FY2024, with a full‑year target of ¥4.0–5.0 billion for FY2024, excluding new game or anime contributions and investment income. For FY2026, the company projects similar operating income levels while targeting a 10 % return from its Investment Business and aiming for half of non‑investment earnings to derive from non‑game, non‑anime sources. This reflects a medium‑term strategy of expanding stable revenue streams beyond traditional gaming.
- GREE is pivoting away from the declining profitability of the smartphone game market toward a diversified portfolio, aiming for half of non-investment earnings to come from non-game, non-anime sources by FY2026.
- The company projects a consolidated operating income of ¥4.0–5.0 billion for FY2024, excluding contributions from new game releases, anime, or investment income.
- Within the Metaverse Business segment, the Platform and B2B sub-segments are currently profitable, with a group-wide goal for all four sub-segments to reach profitability by FY2026.
- GREE is restructuring its game development pipeline into four categories—in-house, regional expansion, joint development, and licensing—while prioritizing quality over speed by withholding release dates for FY2024 titles.
- The Investment Business is targeted to achieve a 10% return by FY2026 as part of the company's medium-term strategy to build stable revenue streams.
+1
GREE
Report1 pages
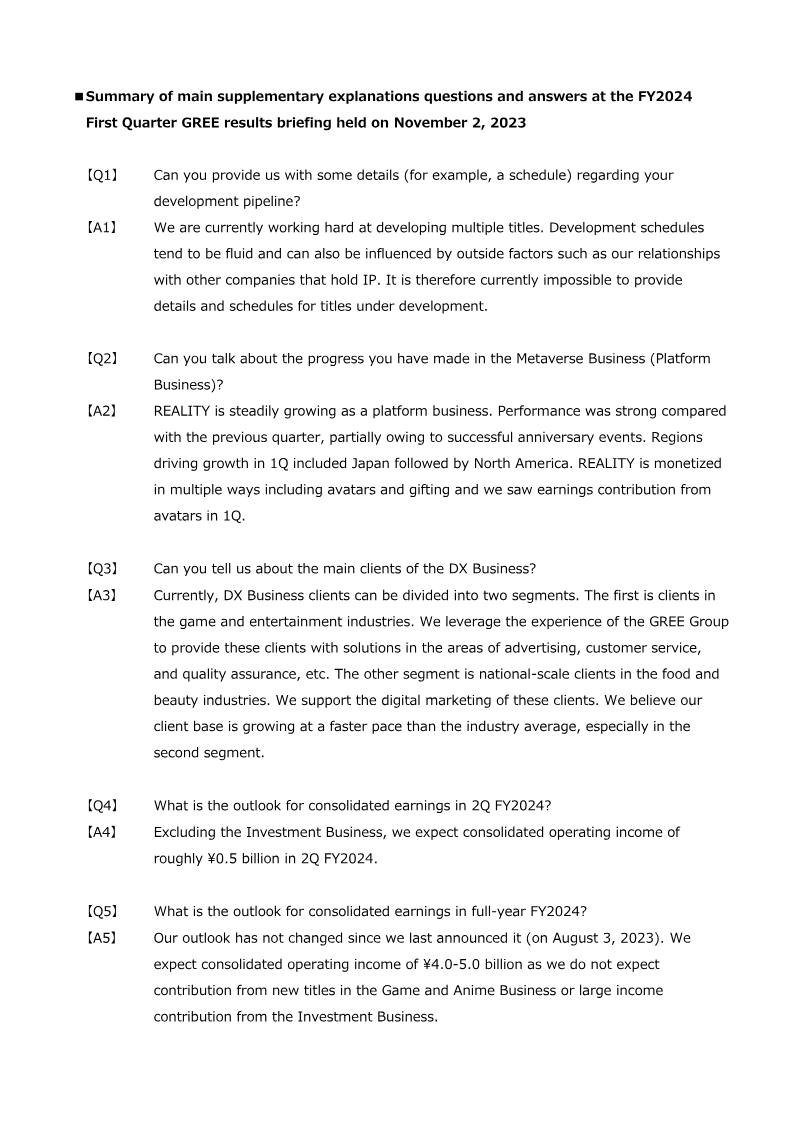
Summary of Main Supplementary Explanations Questions and Answers: FY2024 First Quarter GREE Results Briefing
The briefing clarified GREE’s strategic focus and financial outlook for FY2024. Development activities remain fluid, with no concrete release schedule disclosed due to external IP dependencies and shifting priorities. In the Metaverse platform segment, the REALITY service showed robust growth in the first quarter, driven by Japan and North America. Monetization diversified across avatars and gifting, contributing to earnings from the platform business. The DX Business continues to expand its client base, split between game and entertainment firms—leveraging GREE’s expertise in advertising, customer service, and quality assurance—and national‑scale food and beauty companies that benefit from digital marketing support. Growth in the latter segment is noted to outpace industry averages.
Financial projections for the second quarter exclude investment activities, estimating consolidated operating income around ¥0.5 billion. Year‑end guidance remains unchanged from the August 3, 2023 announcement, targeting consolidated operating income between ¥4.0 and ¥5.0 billion for FY2024, with no significant impact expected from new game or anime titles or the investment arm. The company’s emphasis on platform monetization and diversified DX services underpins its confidence in maintaining steady earnings growth amid a competitive digital landscape.
- GREE maintains its FY2024 consolidated operating income guidance of ¥4.0 billion to ¥5.0 billion, as originally announced on August 3, 2023.
- The company projects consolidated operating income for the second quarter at approximately ¥0.5 billion, excluding the impact of investment activities.
- The REALITY metaverse platform achieved robust growth in Q1, driven by strong performance in the Japanese and North American markets through avatar and gifting monetization.
- The DX Business is experiencing growth that outpaces industry averages, particularly within its client segment of national-scale food and beauty companies.
- GREE’s DX Business continues to expand its client base by leveraging internal expertise in advertising, customer service, and quality assurance for both entertainment firms and non-gaming sectors.
+2
GREE
Report2 pages
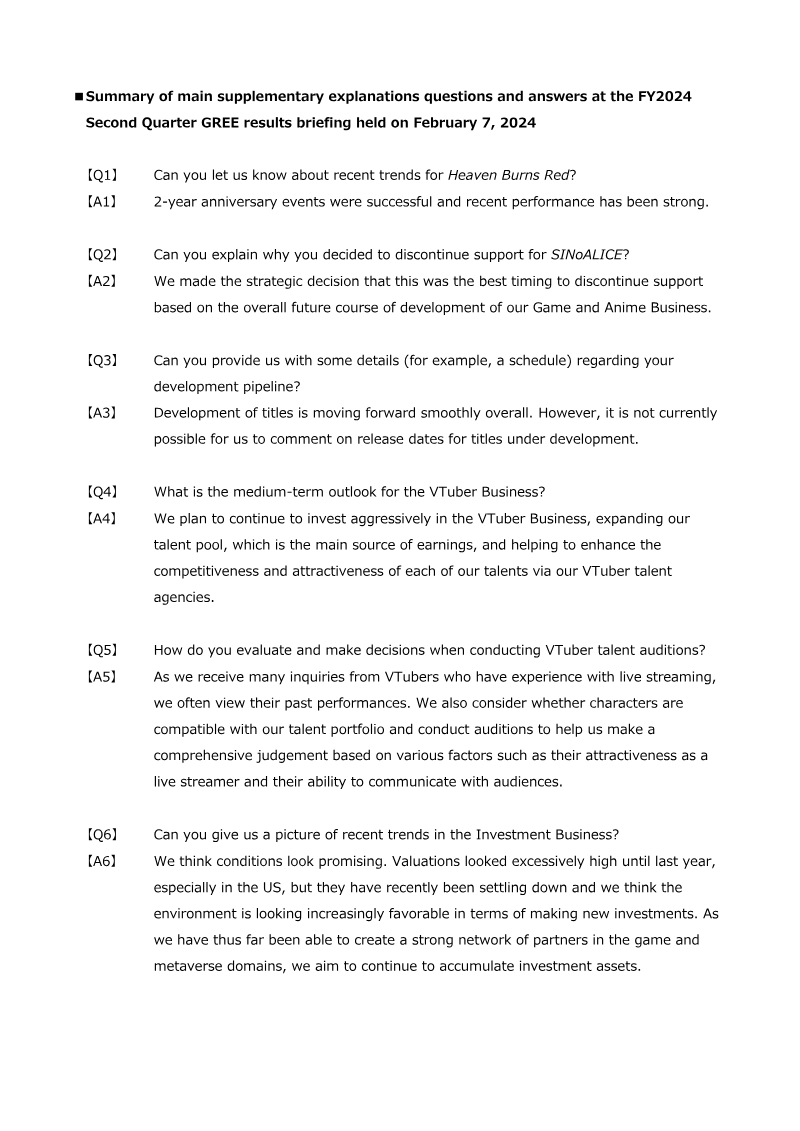
Summary of Main Supplementary Explanations Questions and Answers: FY2024 Second Quarter
The briefing clarified GREE’s strategic priorities and financial outlook for the second quarter of FY2024. Recent events for Heaven Burns Red celebrated its two‑year anniversary, generating strong performance and reinforcing the company’s focus on successful titles. The decision to discontinue support for SINoALICE was framed as a timing choice aligned with the broader development trajectory of GREE’s Game and Anime Business, indicating a shift toward more promising projects.
Development activities continue to progress smoothly, though specific release dates remain undisclosed. In the VTuber segment, GREE plans aggressive investment to expand its talent pool and enhance competitiveness through its talent agencies. Talent auditions are evaluated on past streaming performance, character fit with the existing portfolio, and audience engagement capabilities.
Investment business conditions are described as improving; after a period of inflated valuations—particularly in the United States—market values have stabilized, creating a favorable environment for new investments. GREE’s established network in gaming and metaverse sectors positions it to accumulate additional investment assets.
Financial projections for the third quarter exclude the Investment Business, estimating consolidated operating income of approximately ¥1.5 billion. For the full fiscal year FY2024, the company forecasts consolidated operating income of roughly ¥5.0 billion under the same exclusion. These figures suggest a steady growth trajectory driven by core gaming, anime, and VTuber operations while maintaining a cautious stance on investment activities.
- GREE forecasts consolidated operating income of approximately ¥1.5 billion for Q3 and ¥5.0 billion for the full fiscal year FY2024, excluding the Investment Business.
- The company is shifting its Game and Anime Business strategy by discontinuing support for SINoALICE to prioritize more promising development projects.
- Heaven Burns Red remains a core performance driver, with its two-year anniversary events contributing to strong financial results.
- GREE is aggressively increasing investment in its VTuber segment to expand its talent pool and improve competitiveness through its talent agencies.
- Market conditions for the Investment Business have stabilized following a period of inflated valuations in the United States, prompting GREE to seek new investment assets.
+3
GREE
Report1 pages
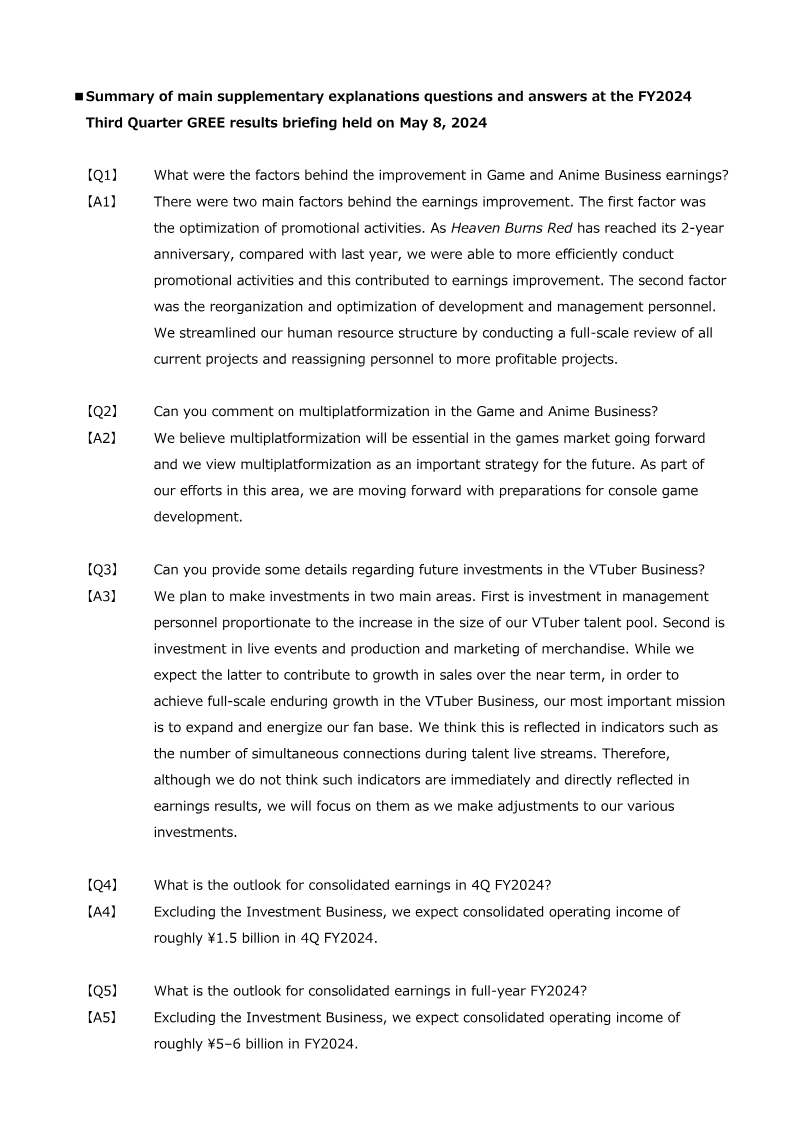
Summary of Main Supplementary Explanations Questions and Answers: FY2024 Third Quarter Results Briefing
The briefing clarified that the FY2024 third‑quarter earnings improvement in GREE’s Game and Anime Business stemmed from two primary initiatives: a more efficient promotional strategy following the second anniversary of “Heaven Burns Red,” and a comprehensive reorganization that reassigned staff to higher‑margin projects. The company emphasized multiplatformization as a strategic priority, noting active preparations for console game development to capture broader market segments.
In the VTuber segment, planned investments focus on expanding management capacity in line with a growing talent roster and enhancing live‑event production, merchandise marketing, and fan engagement metrics such as concurrent viewer counts. While these initiatives are expected to drive near‑term sales, the company views sustained growth as contingent on deepening fan base loyalty.
Financial outlooks presented exclude investment business figures. Consolidated operating income for the fourth quarter is projected at approximately ¥1.5 billion, and full‑year FY2024 earnings are estimated between ¥5–6 billion. These targets reflect the company’s confidence in its streamlined operations and strategic expansion across gaming, anime, and VTuber platforms.
- GREE projects a full-year FY2024 consolidated operating income between ¥5 billion and ¥6 billion.
- The company forecasts a consolidated operating income of approximately ¥1.5 billion for the fourth quarter of FY2024.
- Earnings growth in the Game and Anime Business was driven by optimized promotional spending for 'Heaven Burns Red' and the reallocation of staff to higher-margin projects.
- GREE is prioritizing multiplatformization, with active preparations underway to expand game development into the console market.
- VTuber segment investments are targeting increased management capacity, live-event production, and merchandise marketing to boost fan engagement metrics.
+2
GREE
Report1 pages
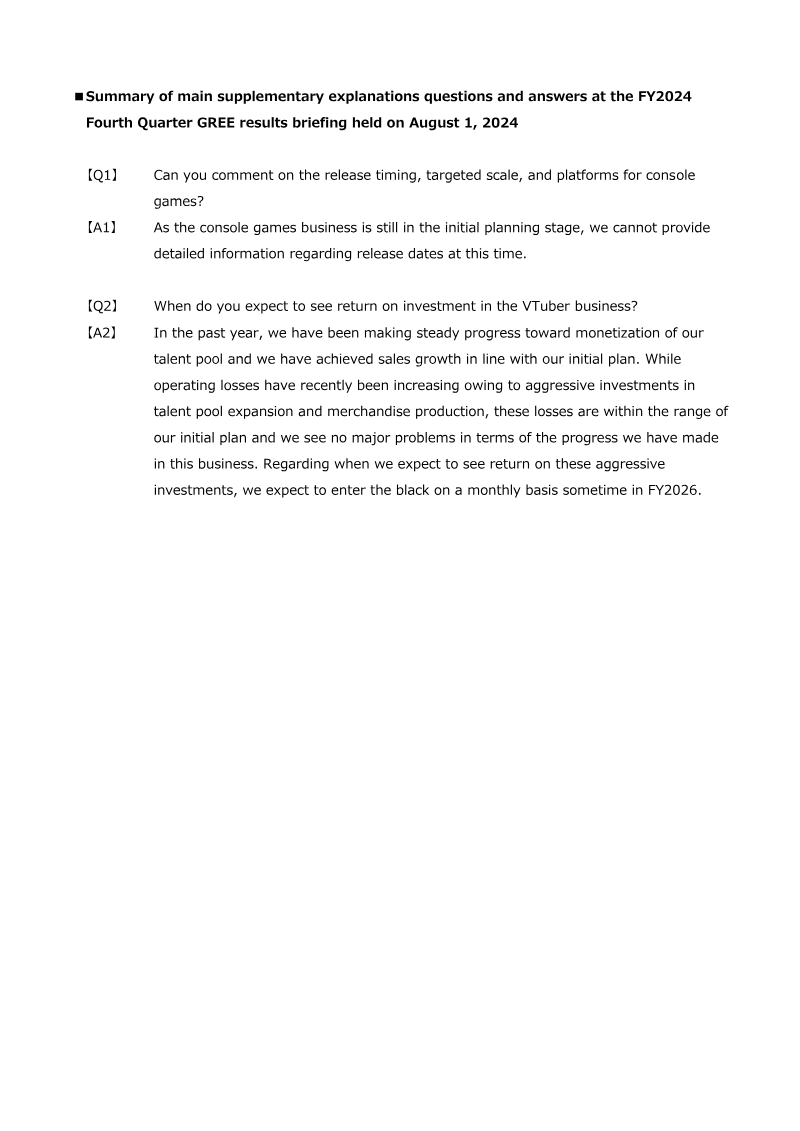
Summary of Main Supplementary Explanations Questions and Answers: FY2024 Fourth Quarter GREE Results Briefing
The briefing clarified GREE’s strategic outlook for FY2024, focusing on console game development and the VTuber business. The company confirmed that its console gaming venture remains in early planning, with no concrete release dates or platform commitments disclosed. This indicates a cautious approach as GREE evaluates market entry points and potential partnerships before committing resources.
In contrast, the VTuber segment is progressing toward profitability. GREE reported steady sales growth aligned with its initial projections, despite operating losses that have risen due to aggressive talent acquisition and merchandise production. These losses fall within the company’s planned range, suggesting disciplined financial management amid expansion efforts. GREE projects that monthly operating losses will be eliminated in FY2026, marking the anticipated break‑even point for its VTuber investments.
The briefing covered a domestic Japanese market focus, with no mention of international expansion for either segment. The time frame discussed spans FY2024 through FY2026, highlighting short‑term challenges and medium‑term profitability goals. Methodological details were limited; the company referenced internal financial metrics rather than external surveys or third‑party data. Overall, GREE’s communication signals a phased growth strategy: cautious console game development coupled with aggressive scaling of its VTuber platform, aiming for profitability by the middle of FY2026.
- GREE targets a break-even point for its VTuber business by the middle of FY2026, with monthly operating losses expected to be eliminated by that time.
- The VTuber segment is currently experiencing rising operating losses due to aggressive investments in talent acquisition and merchandise production, though these costs remain within the company's planned budget.
- GREE’s console game development remains in the early planning stages, with no confirmed release dates, platforms, or resource commitments disclosed.
- The company is pursuing a phased growth strategy that prioritizes cautious evaluation for console gaming while aggressively scaling its VTuber platform.
- GREE’s current strategic outlook is focused exclusively on the domestic Japanese market, with no stated plans for international expansion in the console or VTuber segments.
+2
GREE
Report1 pages
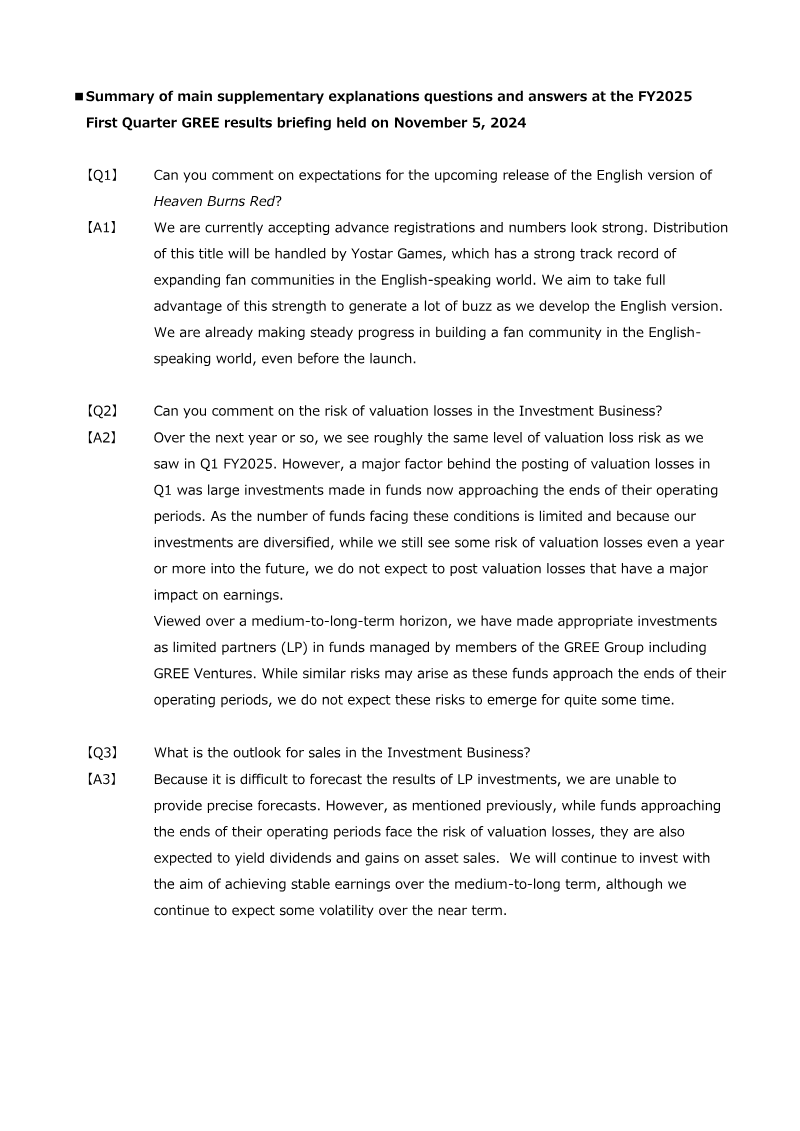
Summary of main supplementary explanations questions and answers at the FY2025 First Quarter GREE results briefing held on November 5, 2024
The briefing clarified GREE’s strategic focus for FY2025 first‑quarter results, emphasizing both gaming and investment operations. In the gaming segment, the company confirmed that advance registrations for the English version of “Heaven Burns Red” are strong and that distribution will be handled by Yostar Games, whose track record in expanding English‑speaking fan communities is expected to generate significant buzz. GREE highlighted ongoing community building efforts prior to launch, underscoring a proactive marketing approach.
Regarding the investment business, management acknowledged that valuation‑loss risk remains comparable to Q1 FY2025 levels. The primary driver of past losses was large investments in funds nearing the end of their operating periods; however, diversification and limited exposure to such funds mitigate long‑term impact. GREE maintains that while short‑term volatility may persist, medium‑to‑long‑term earnings should remain stable as funds mature and yield dividends or asset sales. The company reiterated its commitment to investing in GREE‑Group managed funds, including GREE Ventures, and expects related risks to surface only after several years.
Overall, the briefing presented a balanced outlook: aggressive growth in the gaming arm through strategic partnerships and community engagement, coupled with cautious yet steady investment practices aimed at preserving earnings stability amid inherent valuation risks.
- GREE is launching the English version of 'Heaven Burns Red' in partnership with Yostar Games, leveraging the publisher's expertise in growing English-speaking fan communities.
- The company is prioritizing proactive community building and marketing efforts ahead of the 'Heaven Burns Red' English launch to drive engagement.
- Management expects valuation-loss risks in the investment segment to remain consistent with Q1 FY2025 levels in the near term.
- While short-term volatility persists, GREE anticipates stable medium-to-long-term earnings as existing funds mature through asset sales and dividend yields.
- The company has mitigated long-term investment risk by diversifying its portfolio and limiting exposure to funds nearing the end of their operating cycles.
+3
GREE
Report2 pages
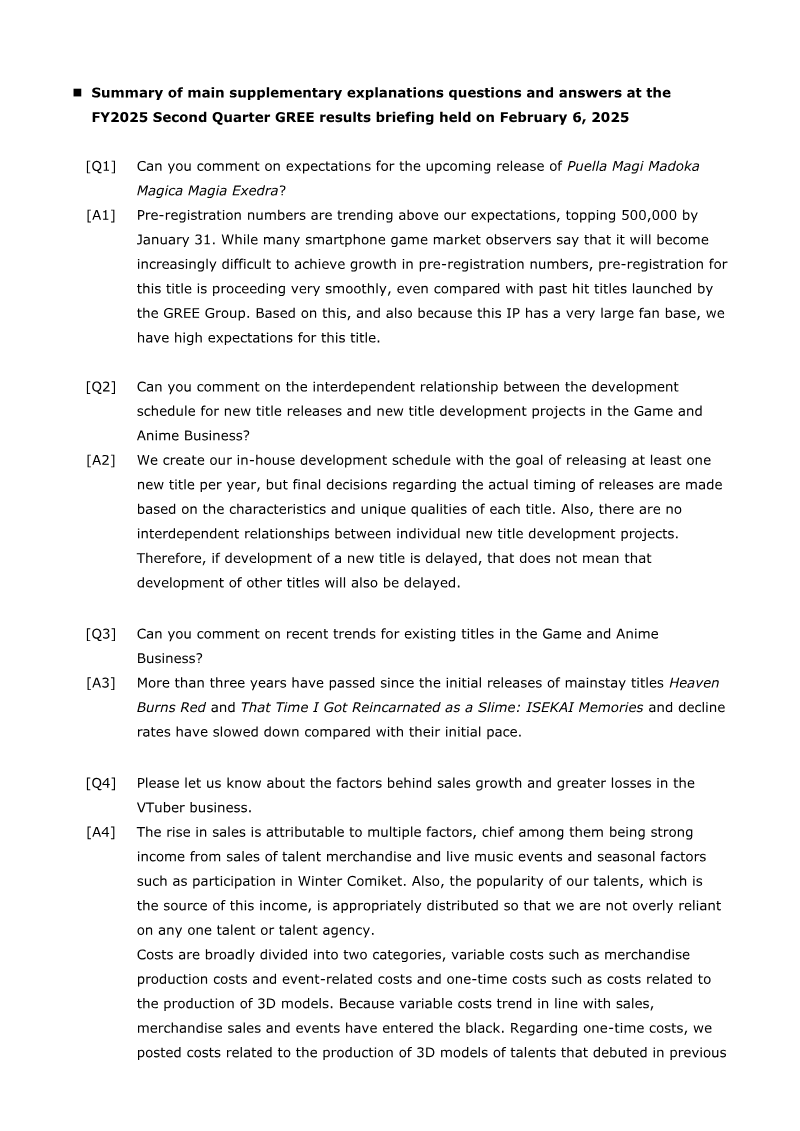
Summary of Main Supplementary Explanations Questions and Answers: FY2025 Second Quarter GREE Results Briefing
The briefing outlines GREE’s performance and strategic outlook for FY2025 Q2, focusing on game releases, existing title dynamics, and the VTuber business. Pre‑registration for “Puella Magi Madoka Magica Magia Exedra” surpassed 500,000 by January 31, exceeding expectations and reinforcing confidence in the IP’s strong fan base. The company maintains an annual release cadence for new titles, but schedules are determined independently per project; delays in one title do not cascade to others. Existing flagship games such as Heaven Burns Red and That Time I Got Reincarnated as a Slime: ISEKAI Memories have experienced a deceleration in decline rates after three years, indicating sustained player engagement.
In the VTuber segment, sales growth is driven by talent merchandise, live music events, and seasonal participation in Winter Comiket. Revenue has turned profitable as variable costs align with sales, while one‑time expenses—primarily 3D model production for new and returning talents—have increased quarterly, contributing to larger losses. Management anticipates that expanding the talent roster will stabilize one‑time costs and enhance profitability.
Looking ahead, GREE projects monthly profitability in FY2026 with annual VTuber sales near ¥3.0 billion, followed by accelerated growth targets. The briefing underscores a balanced approach to new title development, sustained performance of legacy games, and a focused strategy for scaling the VTuber business while managing cost structures.
- GREE targets monthly profitability for its VTuber segment in FY2026, with annual sales projected to reach approximately ¥3.0 billion.
- Pre-registration for the upcoming title 'Puella Magi Madoka Magica Magia Exedra' exceeded 500,000 by January 31, signaling strong market interest.
- Flagship games 'Heaven Burns Red' and 'That Time I Got Reincarnated as a Slime: ISEKAI Memories' have stabilized, showing a deceleration in decline rates after three years of operation.
- The VTuber business is currently experiencing increased quarterly losses due to one-time 3D model production expenses, though variable costs have successfully aligned with sales.
- GREE maintains an independent release schedule for new games, ensuring that project-specific delays do not impact the broader annual release cadence.
+2
GREE
Report3 pages
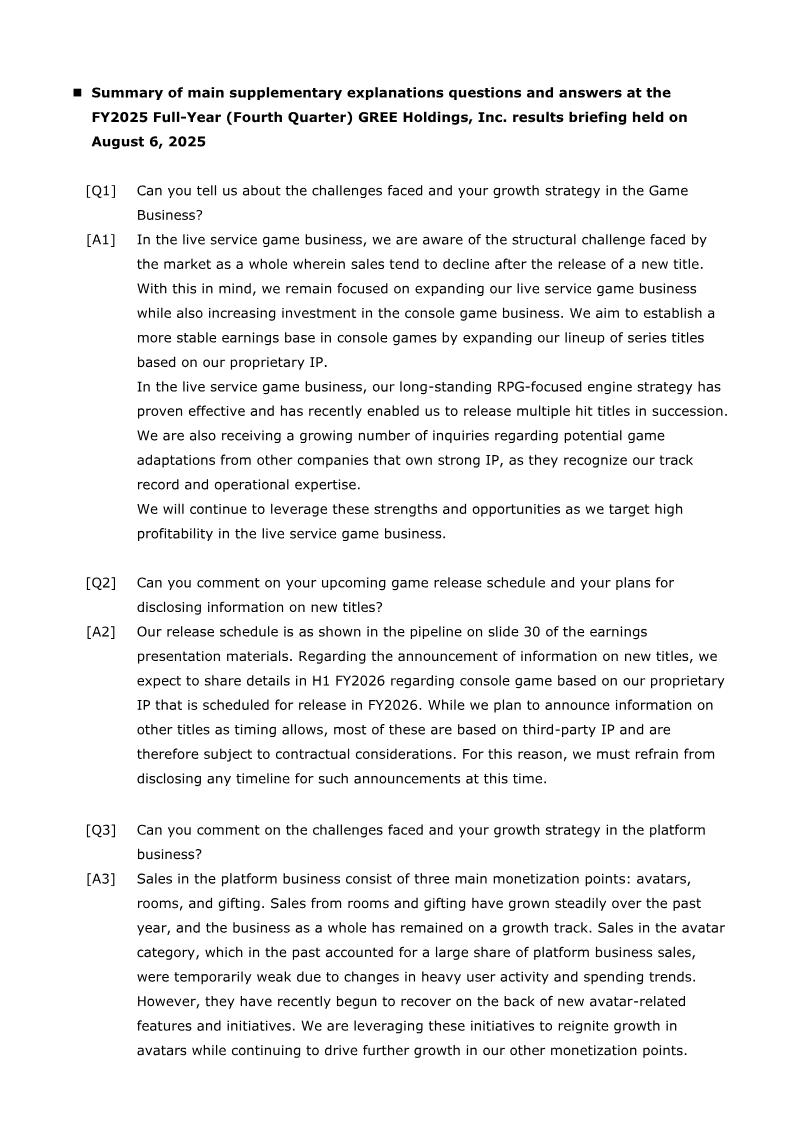
Summary of Main Supplementary Explanations Questions and Answers: FY2025 Full-Year Results
GREE Holdings outlines its FY2025 full‑year results and forward strategy across several business segments. In the game division, the company acknowledges the typical post‑launch decline in live‑service titles and counters it by expanding both its live‑service portfolio—leveraging a proven RPG engine—and investing in console games built on proprietary IP to create a steadier earnings base. The company reports multiple recent hit releases and anticipates further inquiries for third‑party IP adaptations, positioning itself to capture high profitability in the live‑service arena.
The platform business remains growth‑oriented, with steady increases in room and gifting revenue offsetting a temporary dip in avatar sales. New avatar features are expected to revive this segment, while the company continues to push other monetization channels. In the VTuber sector, GREE pursues a two‑stage growth model: first expanding its talent roster—now about 90 talents—and then boosting sales per talent through diversified merchandise channels and nascent live‑event advertising. Sales per talent have doubled since FY2024, and the company maintains a balanced portfolio to avoid over‑reliance on any single talent.
The DX business is undergoing a structural shift from one‑time project sales to recurring revenue, with modest growth projected through FY2026 as the transition completes. Investment activities in FY2026 will see increased volatility due to fund maturity and potential impairment, yet the company expects stable income streams from dividends and performance fees. Overall, GREE projects balanced returns while navigating market challenges across its diversified entertainment portfolio.
- GREE is shifting its game division strategy to balance post-launch live-service volatility by investing in console titles built on proprietary IP.
- The VTuber business has doubled sales per talent since FY2024, supported by a roster of approximately 90 talents and expanded merchandise and advertising channels.
- The DX business is transitioning from a one-time project sales model to a recurring revenue structure, with modest growth expected through FY2026.
- Platform revenue growth is currently driven by room and gifting monetization, which is offsetting a temporary decline in avatar sales.
- Investment activities in FY2026 are expected to experience increased volatility due to fund maturity and potential impairments, though stable income from dividends and performance fees is anticipated.
+4
GREE
Report3 pages
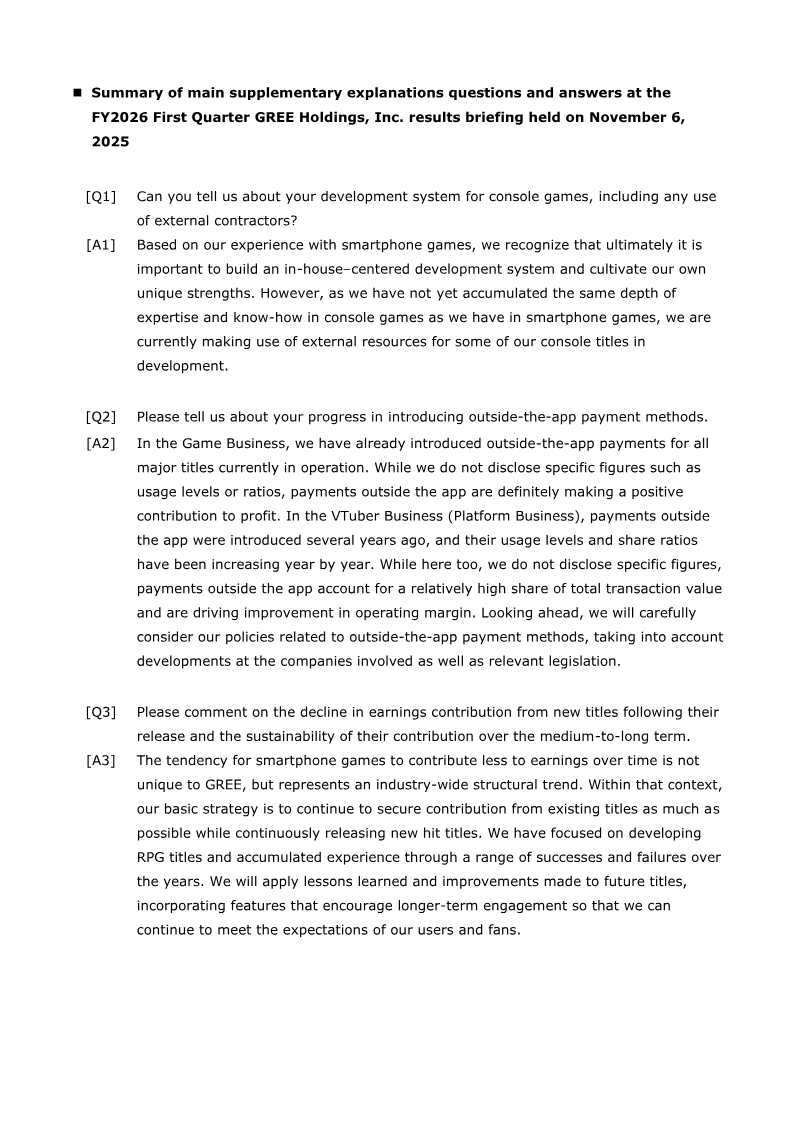
Summary of main supplementary explanations questions and answers at the FY2026 First Quarter GREE Holdings, Inc. results briefing held on November 6, 2025
GREE Holdings’ FY2026 first‑quarter briefing clarified strategic priorities across its game, VTuber, and investment divisions. The company emphasized a shift toward an in‑house development model for console titles while still leveraging external contractors to bridge current expertise gaps. In the mobile game segment, outside‑app payment methods have been fully deployed across all major titles and are contributing positively to profitability; the VTuber platform has similarly expanded its outside‑app transactions, boosting operating margins. The firm acknowledges a structural decline in earnings from new smartphone releases but plans to sustain revenue by focusing on long‑term engagement features and continuous hit title launches, particularly within the RPG genre.
Market outlooks reveal a plateau in smartphone installs but growing potential through high‑value IP and outside‑app monetization. Console gaming is viewed as a long‑term investment, with an emphasis on cultivating enduring IP series. The VTuber market is still expanding globally, especially overseas, and the company projects full‑year profitability for its VTuber production arm by FY2027 as higher‑margin merchandise and live events offset earlier talent acquisition costs.
Exit strategies for the investment business have shifted from IPOs to M&A, reflecting broader market conditions. Generative AI is being integrated across game development, VTuber content creation, and digital transformation services to enhance efficiency and service quality, though its direct earnings impact remains difficult to quantify. Overall, GREE aims to strengthen core competencies, diversify revenue streams, and adapt to evolving market dynamics while pursuing sustainable growth.
- GREE is transitioning to an in-house development model for console titles, utilizing external contractors to address current expertise gaps while focusing on long-term IP cultivation.
- Outside-app payment methods have been fully implemented across all major mobile titles and the VTuber platform, directly contributing to improved operating margins.
- The VTuber production arm is projected to reach full-year profitability by FY2027 as high-margin merchandise and live events offset initial talent acquisition costs.
- The company is shifting its investment business exit strategy from IPOs to M&A to better align with current market conditions.
- Generative AI is being integrated into game development, VTuber content creation, and digital transformation services to improve operational efficiency and service quality.
+3
GREE
Report72 pages
Annual Report and Consolidated Financial Statements 2023
ANNUAL R THE YEAR ENDED FINANCIAL STATEMENTS FOR THE YEAR ENDED Business model 10 Chief Executive’s review 15 Chief Financial Officer’s review 17 Environmental, social and governance (ESG) 19 Principal risks and uncertainties 20 Corporate Governance 25 Board of Directors 25 Corporate governance report ...
- Revenue generated from own-IP (1st and 2nd party games) decreased to 65% of gaming revenues in 2023, down from 77% in 2022, due to changes in the portfolio mix. Conversely, revenues from the back-catalogue increased to 92% of total revenues in 2023 (up from 80% in 2022), driven by successful new releases like "I am Future" (Early Access) and "Punch Club 2".
- The company maintains a strong social media presence with over 1.7 million followers across platforms by the end of 2023, placing it competitively with other gaming companies like Devolver Digital (1.1m) and Paradox Interactive (0.9m). They also boast c.5 billion YouTube views and over 10,000 verified influencers.
- The top 5 games generated 46.8% of total revenues in 2023 (up from 44.8% in 2022), and the top 10 games generated 65.44% (down from 66.3% in 2022), indicating broad diversification across audiences, genres, and technologies.
- The company incurred $3.5 million in legal settlement fees in 2023 and continues to face costs related to the Ukraine/Russia conflict, which are now included in operating expenses, with potential for future charges.
- The company mitigates risks associated with early-stage developer engagement by providing milestone-based funding, acquiring IP as part of agreements, and adjusting budgets using data-driven approaches. They also intensify audience validation through playtests and demos to align with consumer trends.
+1
tinyBuild
Report71 pages
Annual Report 2012: 11 bit studios S.A.
I. PISMO ZARZĄDU ............................................................................................................. 3 II. WYBRANE JEDNOSTKOWE DANE FINANSOWE ZAWIERAJĄCE PODSTAWOWE POZYCJE ROCZNEGO SPRAWOZDANIA FINANSOWEGO WRAZ Z DANYMI PORÓWNYWALNYMI ................ 4 III. SPRAWOZDANIE FINANSOWE ZA ROK 2012 11 BIT STUDIOS S.A. ........................................ 4 IV. SPRAWOZDANIE ZARZĄDU Z DZIAŁALNOŚCI SPÓŁKI W ROKU 2012....................................
- 11 bit studios S.A. reported a net profit of 1,344,700.33 PLN in 2012, a slight increase from 1,292,777.32 PLN in 2011.
- The company's equity significantly increased from 2,560,977.91 PLN in 2011 to 6,913,931.74 PLN in 2012, primarily due to an increase in share capital and reserve capital.
- Share capital increased from 187,076.10 PLN to 221,719.90 PLN in 2012 through the issuance of Series D and E shares, with nominal values of 0.10 PLN per share.
- Revenue from sales in 2012 totaled 3,346,593.68 PLN, with 95.5% of this revenue coming from foreign sales.
- Operating costs amounted to 3,007,118.43 PLN in 2012, with salaries constituting 59.7% and external services 31.9% of these costs.
+2
11 bit studios
Report86 pages
Consolidated Annual Report 2016: 11 bit studios
Kapitat PISMO ZARZĄDU z nadwyzki rezerwowy Przypadajace Przypadajace Kapitat wartosci Kapitat z tytutu z przeliczenia Zyski akcjonariuszom dziatom podstawowy emisyjnej jednostek Warszawa, 30 marca 2017 roku ponad wartosc zapasowy ptatnosci w zagranicznych i zatrzymane dominujacej kontro nominal...
- 11 bit studios S.A. achieved its best financial year ever in 2016, with revenues reaching PLN 27 million, a 16.6% increase from 2015, and net profit growing by 11.8% to PLN 12.9 million, despite a one-time non-cash write-off of PLN 0.64 million from the Games Republic platform.
- The company's operational profit increased by nearly 3% to PLN 14.1 million in 2016, and it held PLN 29.11 million in cash by the end of December 2016, indicating strong financial health.
- The game "This War of Mine" (TWoM), released in autumn 2014, has generated over PLN 60 million in cumulative revenue, establishing 11 bit studios' brand recognition and financial stability.
- 11 bit studios S.A. is focusing on developing PC games using its proprietary engine, with "Frostpunk" being the main project, scheduled for release in the second half of 2017, with a significantly larger production and marketing budget than TWoM.
- The company's primary activities are the production and sale of multi-platform video games and global digital distribution of video games, with its shares publicly traded since its founding in 2009.
+1
11 bit studios
Report139 pages
Raport Roczny 11 bit studios: 2022
RAPORT ROCZNY 11 BIT STUDIOS ZA 2022 ROK (wszystkie kwoty podane są w złotych o ile nie podano inaczej) SZANOWNI AKCJONARIUSZE I INWESTORZY Serdecznie zapraszamy Państwa do lektury Raportu rocznego 11 bit studios S.A. za rok 2022. Był to dla nas, z uwagi na trudne otoczenie makroekonomiczne (spowolnienie gospodarcze, wysoka inflacja) i geopolityczne (wojna na Ukrainie), bardzo intensywny, wymagający rok.
- 11 bit studios S.A. aims to be an "alternative to the mainstream" in gaming, focusing on high-quality, distinctive titles with increasing production and marketing budgets, targeting one new proprietary game release annually in the medium term.
- The company plans to expand its publishing activities, releasing 3-4 titles from external studios annually in the medium term, alongside its own games, to stabilize financial results.
- 11 bit studios S.A. is developing three internal development teams to work on three parallel titles, aiming for releases every few quarters and optimizing resource utilization.
- The company's functional and reporting currency is the Polish Złoty, and it recognizes revenue from PC/console and mobile games after platform deductions, while acting as a principal for games published from external developers.
- In 2022, the company's net cash flow from operating activities was 32,931,559 PLN, a decrease from 40,942,289 PLN in 2021, despite a lower profit for the year (22,889,816 PLN in 2022 vs. 28,685,582 PLN in 2021).
11 bit studios

Report140 pages
Raport Roczny 2021: 11 bit studios S.A.
RAPORT ROCZNY 11 BIT STUDIOS S.A. ZA 2021ROK Szanowni Akcjonariusze i Inwestorzy Serdecznie zapraszamy Was do lektury Raportu rocznego 11 bit studios S.A. za 2021 rok. Wyniki finansowe wypracowane w tym okresie, z których jesteśmy bardzo zadowoleni dowodzą, że Spółka bez perturbacji przeszła przez ten trudny od strony operacyjnej, z uwagi na COVID-owe ograniczenia i obostrzenia rok. W 2021 roku 11 bit studios S.A miało 70,12 mln PLN przychodów ze sprzedaży. Wynik EBITDA sięgnął 38,95 mln PLN.
- 11 bit studios S.A.'s revenue decreased by 19.49% in 2021, falling to 70,122,691 PLN from 87,101,774 PLN in 2020.
- The primary source of revenue for 11 bit studios S.A. in 2021 was the sale of its own games and games published for external developers, with Valve Corporation (Steam) being the main recipient, generating over 10% of total revenue.
- The USA was the dominant geographic market for 11 bit studios S.A. in 2021, accounting for 75.95% of external customer revenue, followed by Japan at 13.75%.
- Investment in unfinished development work significantly increased in 2021, rising to 52,926,024 PLN from 25,545,704 PLN in 2020.
- 11 bit studios S.A. does not currently hold its own shares and has incentive programs for key employees and management that could alter shareholder proportions in the future.
+1
11 bit studios
Report132 pages
Annual Report of 11 bit studios S.A.: 2023
ANNUAL REPORT OF 11 BIT STUDIOS S.A. FOR 2023 (all amounts in PLN unless stated otherwise) DEAR SHAREHOLDERS AND INVESTORS, Please be invited to read 11 bit studios S.A.’s 2023 This past year has brought significant achievements in both sales and game production. We launched a number of major titles that had been in development for some time.
- 11 bit studios S.A. generated PLN 21,147,406 in cash flows from operating activities in 2023, a 37.97% decrease from 2022, despite no new game releases significantly contributing to financial performance. This was driven by strong sales of older titles like Frostpunk, Moonlighter, Children of Morta, This War of Mine, and The Invincible.
- The company significantly increased capital expenditure in 2023, spending PLN 58,813,599 on property, plant, and equipment and intangible assets (up from PLN 45,679,530 in 2022), primarily for new proprietary games (Frostpunk 2, The Alters, Project 8) and publishing division games.
- Contract liabilities surged to PLN 13,355,194 as of December 31, 2023, from PLN 1,128,700 in 2022, representing advance payments from trading partners, including Microsoft Corporation, for future game sales, payable within 24 months.
- The global gaming industry is projected to return to growth, with Newzoo forecasting spending of USD 205.4 billion by 2026 (11.6% more than 2023) and the number of gamers reaching 3.675 billion by 2026 (a CAGR of 3.7% from 2021-2026).
- 11 bit studios S.A. aims to fund its development and publishing activities internally for at least the next few quarters, reducing reliance on external funding or funds from trading partners.
+2
11 bit studios
Report27 pages
Quarterly Report of 11 Bit Studios S.A.: Q1 2019
portfolio of proprietary games) is expected to help stabilise the Company's financial results, which in the video games industry are typically highly volatile. The Company's revenue sources should also be considerably impacted by further development of its publishing division (11 bit publishing), which in 2018, driven primarily by the very successful release of Moonlighter, contributed 18% of the LETTER FROM THE MANAGEMENT BOARD ...
- 11 bit studios S.A. experienced a significant revenue increase of nearly 632% in Q1 2019 compared to Q1 2018, reaching PLN 14,183,796, primarily driven by strong sales of Frostpunk and This War of Mine.
- Operating expenses rose by 267.5% to PLN 8,524,924 in Q1 2019 (from PLN 3,186,555 in Q1 2018), with major items being salaries and wages (PLN 3,306,961), services (PLN 3,367,572, including Moonlighter royalties), and a non-cash provision for the Incentive Scheme (over PLN 2.05m).
- The company's publishing division, 11 bit publishing, contributed 18% of total revenue in 2018, largely due to the successful release of Moonlighter, and is expected to considerably impact future revenue.
- The porting of Beat Cop to PS4, Xbox One, Nintendo Switch, iOS, and Android, released in Q1 2019, proved profitable and supported the company's financial performance.
- 11 bit studios S.A. aims to stabilize its typically volatile financial results through its portfolio of proprietary games and plans to launch third-party games every quarter through its publishing arm.
+2
11 bit studios