1 free read left. Create a free account for unlimited reading + AI research.
Create free accountRegulatory notice Stillfront
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountRegulatory noticeStillfront
Stillfront operates 20 independent studios.
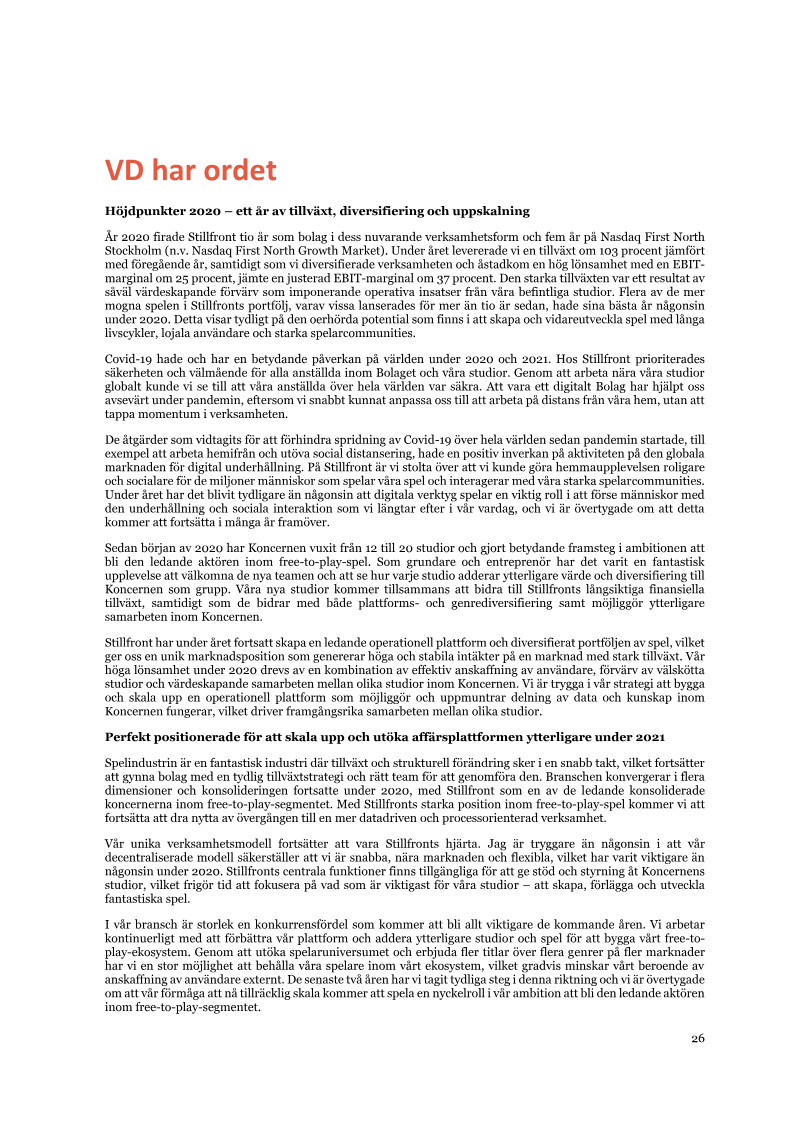
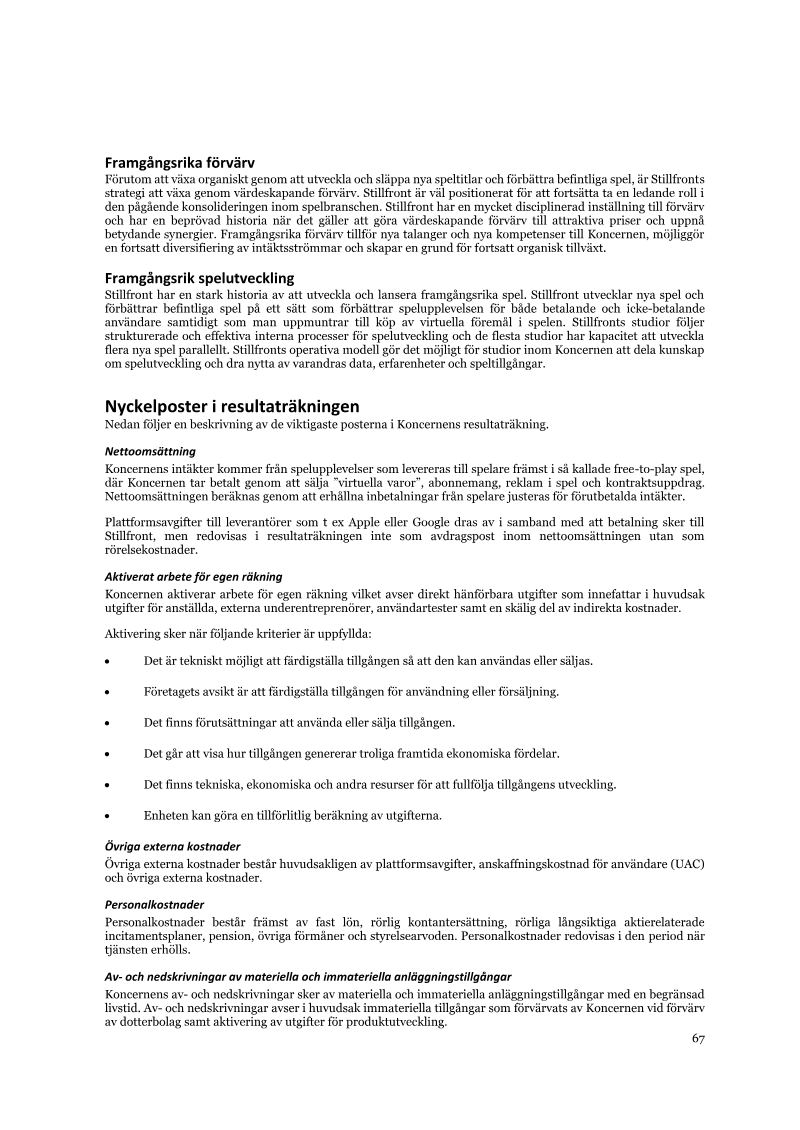
Stillfront Group AB (publ) transitioned its shares from Nasdaq First North Premier to the Nasdaq Stockholm main market in May 2021 to enhance its corporate profile and access broader capital markets. As a global gaming conglomerate, the company operates 20 independent studios focused on the free-to-play mobile segment. Its primary business thesis centers on a decentralized organizational model that balances studio autonomy with centralized financial oversight, supported by an aggressive growth strategy that combines organic development with systematic acquisitions of profitable gaming entities.
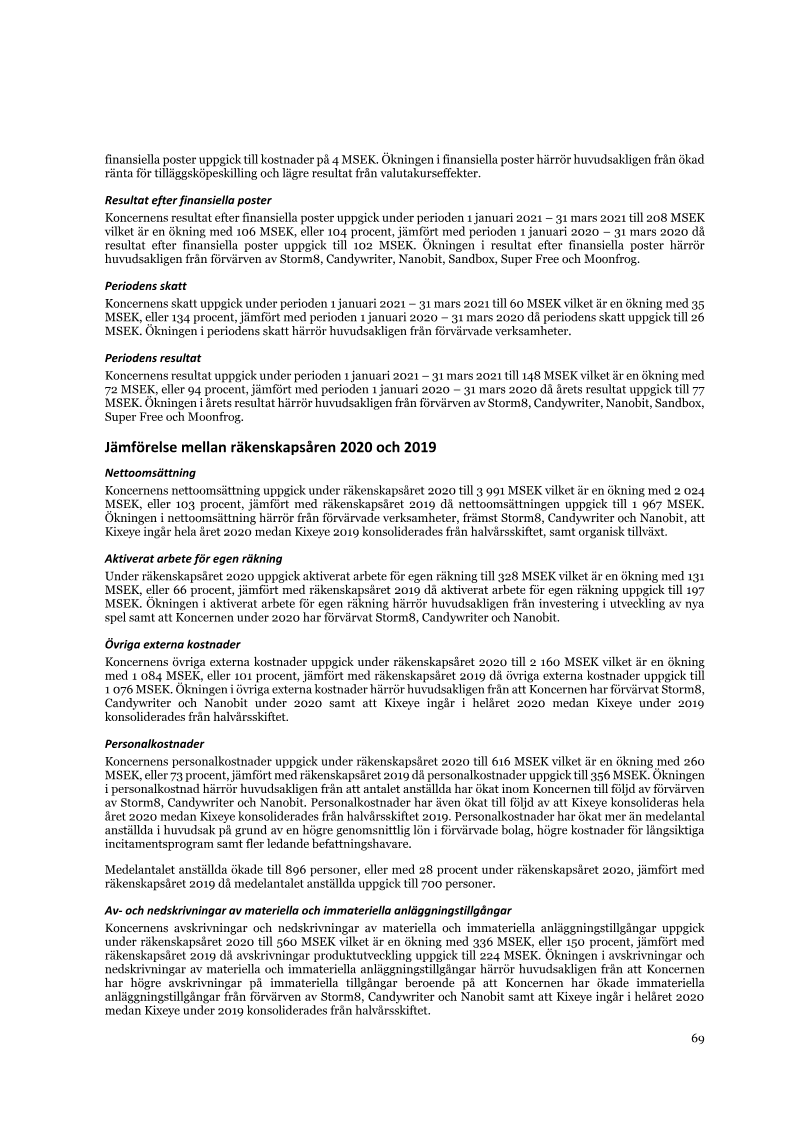
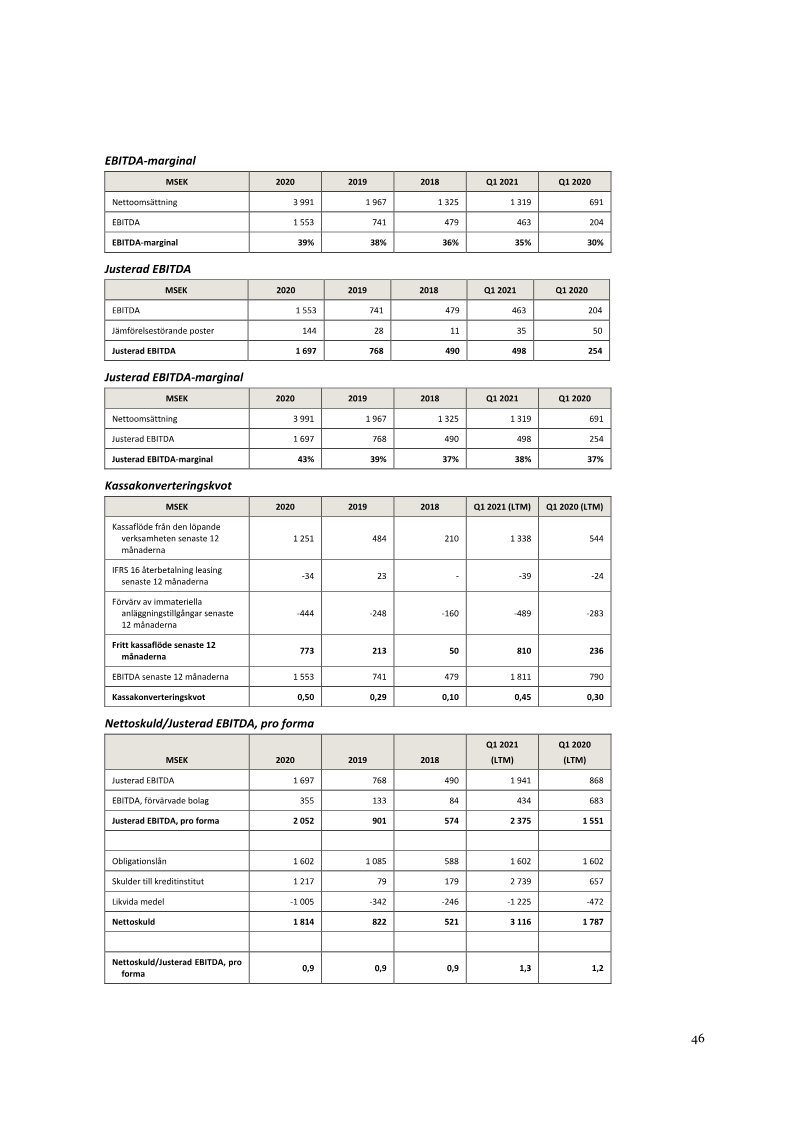
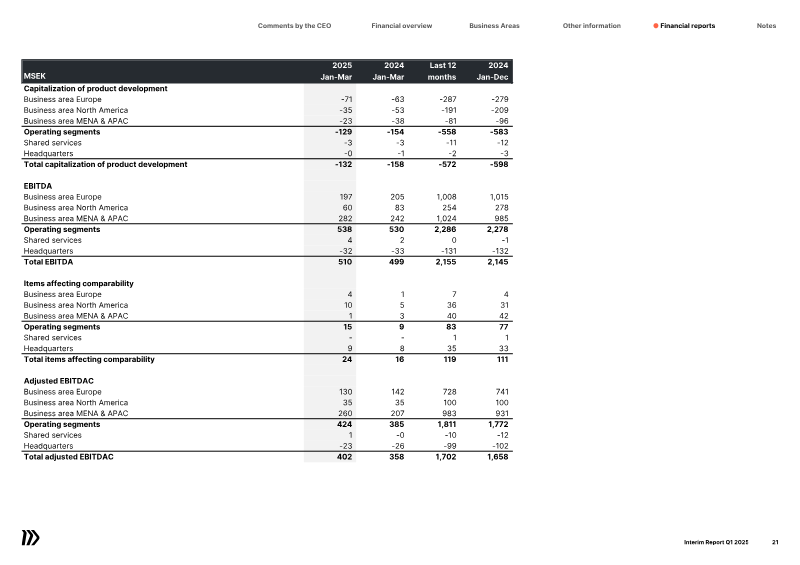
Financial performance between 2018 and early 2021 reflects this rapid expansion, with net sales rising from 1,325 MSEK to 3,991 MSEK by the end of 2020. This growth has been fueled by significant acquisitions, including Storm8, Kixeye, and Moonfrog, which necessitated complex pro forma adjustments to align disparate accounting practices with IFRS standards. While the company maintains strong operating cash flows and an adjusted EBIT margin of approximately 25% as of 2020, its balance sheet carries substantial leverage, including 3,116 MSEK in net financial debt and significant contingent liabilities related to acquisition earn-outs.
The company faces a range of operational and regulatory risks inherent to the digital gaming industry. These include a heavy reliance on major third-party distribution platforms like Apple and Google, which accounted for approximately 74% of 2020 revenue, and vulnerability to shifts in mobile advertising tracking, such as IDFA changes. Furthermore, the business must navigate evolving global regulations regarding data protection, monetization mechanics like loot boxes, and potential gambling classifications. Despite these challenges, Stillfront remains committed to a growth-oriented capital allocation policy, prioritizing reinvestment in acquisitions and organic initiatives over dividend distributions through 2022.
Stillfront · 2026
Stillfront · 2026
Stillfront · 2026
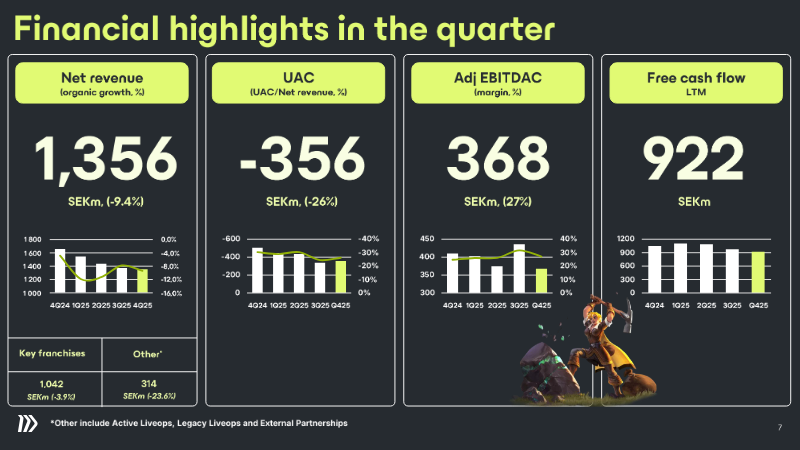
Stillfront · 2026
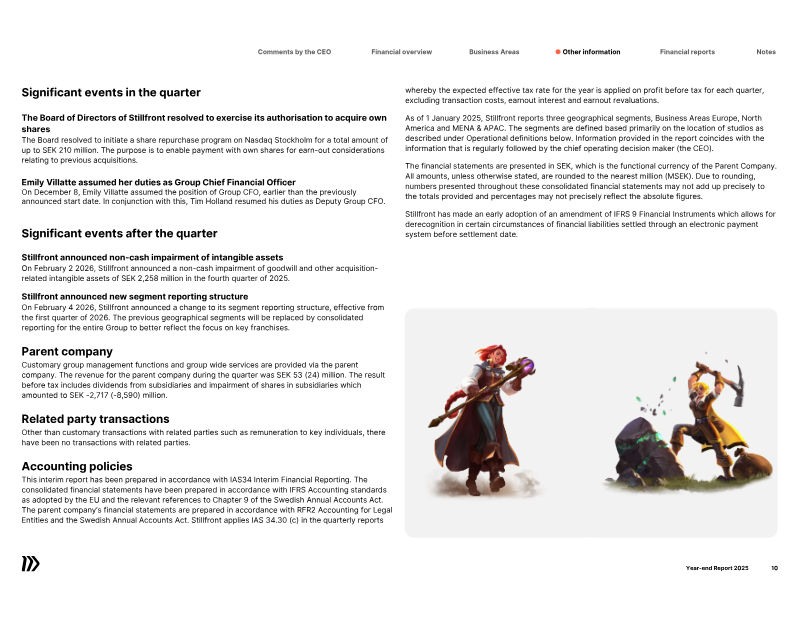
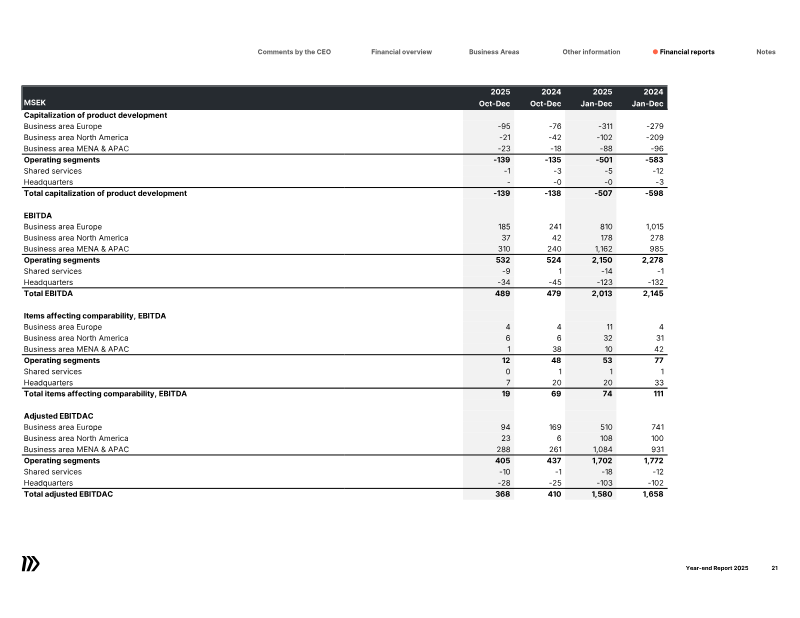
Stillfront · 2025
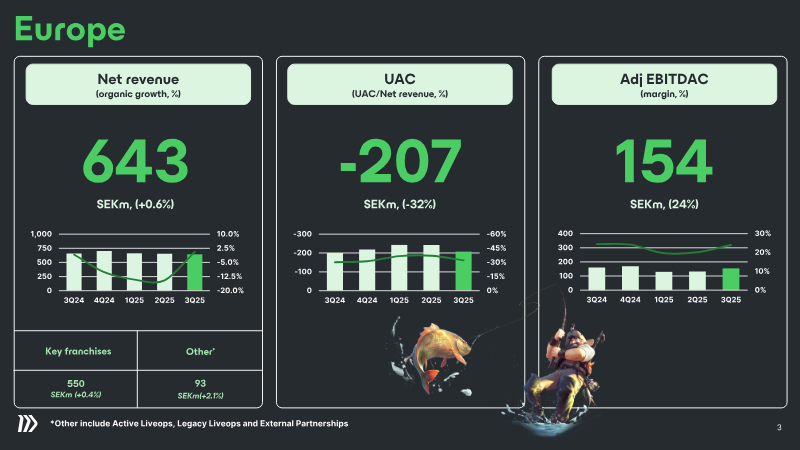
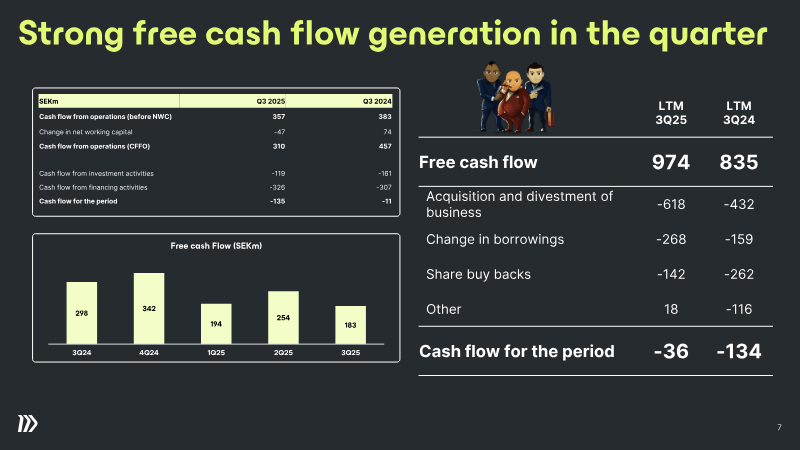
Stillfront · 2025
Stillfront · 2025
Stillfront · 2025
Stillfront · 2025
Stillfront · 2024
Stillfront · 2024
Stillfront · 2024
Deconstructor of Fun · 2026