Nihon Falcom
Game Co.3 documents
Documents
Financial9 pages
Financial Results: Fiscal Year 2026 Second Quarter (Japan)
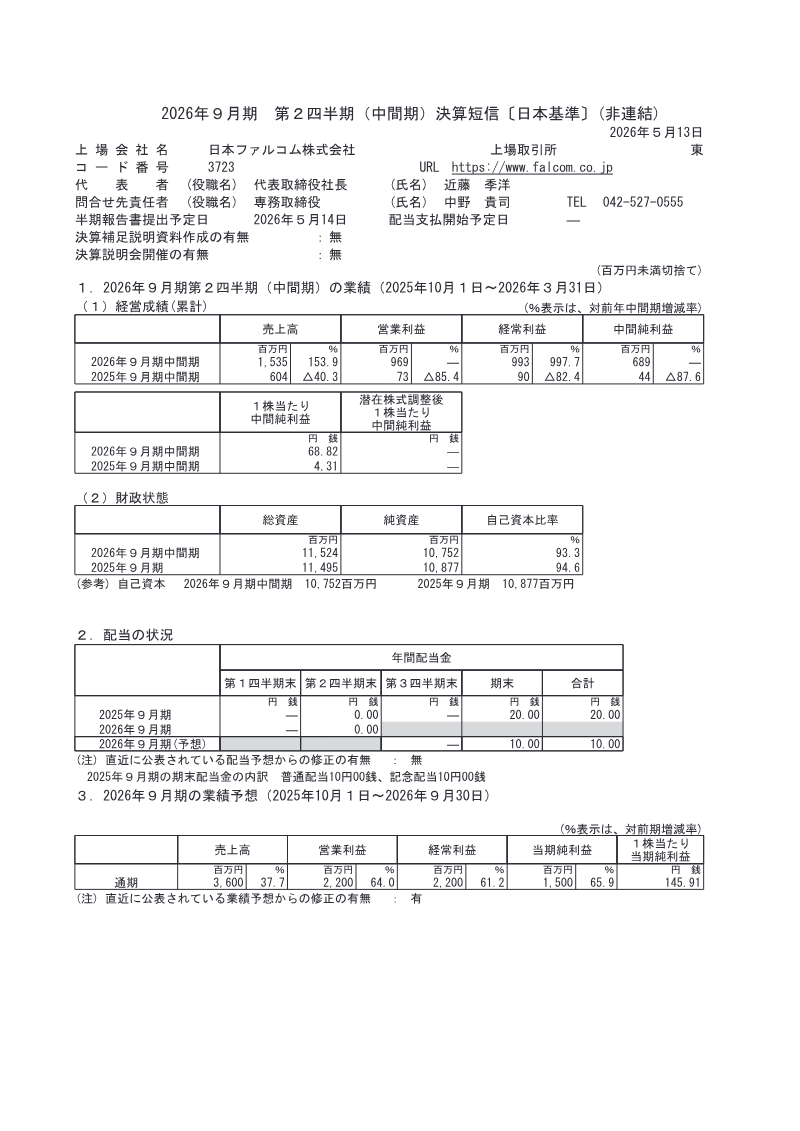
Fiscal year 2026, second‑quarter results for Falcom Corporation show a dramatic rebound from the previous quarter. Total sales rose 153.9 % to ¥1,535 million, driven by a 194.8 % increase in licensing revenue and a modest 5.5 % decline in product sales, reflecting strong performance of the “Sora no Kiseki” series and new releases across Nintendo Switch 2, PlayStation 5, Steam, and mobile platforms. Operating profit surged 1,216.4 % to ¥969 million, and ordinary profit climbed 997.7 % to ¥994 million, largely due to higher gross margins and favorable foreign‑exchange gains. Net profit for the interim period reached ¥689 million, a 1,454.3 % jump from the prior year’s quarter.
Balance‑sheet strength remained robust: total assets increased 0.3 % to ¥11,524 million, with cash and deposits up by ¥372 million. Net equity stood at ¥10,752 million, a 1.1 % decline mainly from share buybacks of ¥608 k and dividend payouts of ¥205 million. The equity ratio remained high at 93.3 %. Cash flow from operations grew to ¥1,186 million, supported by strong sales and efficient working‑capital management.
For the full fiscal year, Falcom forecasts revenue of ¥3,600 million (up 37.7 %), operating profit of ¥2,200 million (up 64.0 %), ordinary profit of ¥2,200 million (up 61.2 %), and net income of ¥1,500 million (up 65.9 %). Earnings per share are projected at ¥145.91. The company attributes the upward revision to continued momentum in its flagship titles and expanding international licensing, while noting that future results may vary with market conditions.
- Falcom Corporation reported a significant rebound in Q2 FY2026, with total sales rising 153.9% to ¥1,535 million and net profit surging 1,454.3% to ¥689 million compared to the prior year's quarter.
- Operating profit grew 1,216.4% to ¥969 million, driven primarily by a 194.8% increase in licensing revenue and favorable foreign-exchange gains.
- The company has issued an upward revision for its full-year FY2026 forecast, projecting revenue of ¥3,600 million (up 37.7%) and net income of ¥1,500 million (up 65.9%).
- Financial stability remains high with an equity ratio of 93.3% and total assets of ¥11,524 million, despite a slight 1.1% decline in net equity due to share buybacks and dividend payouts.
- Performance was bolstered by the 'Sora no Kiseki' series and multi-platform releases across Nintendo Switch 2, PlayStation 5, Steam, and mobile devices.
+1
Nihon Falcom
Financial8 pages
Q1 2026 Fiscal Financial Results: Nihon Falcom
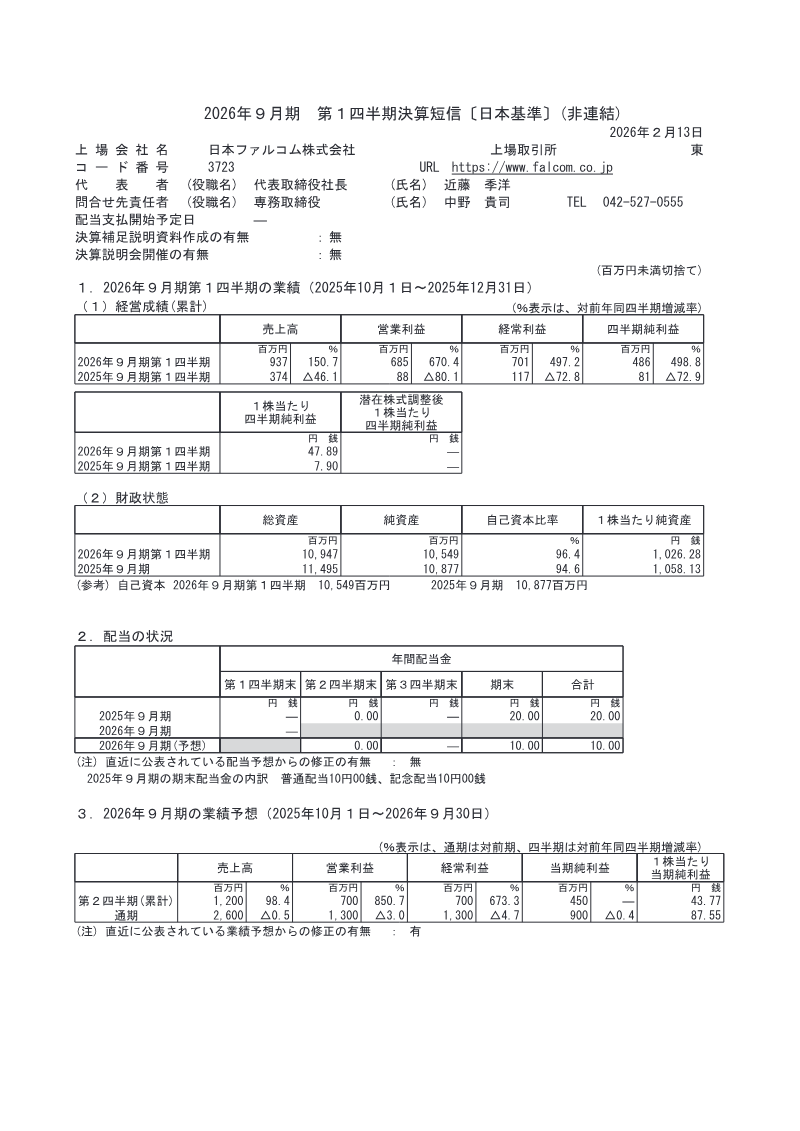
Nihon Falcom’s first‑quarter 2026 fiscal results, covering October to December 2025, show a dramatic turnaround from the previous year’s decline. Total revenue surged 150.7 % to ¥937 million, driven by strong sales of the flagship “Trails” series title “Sky: The First” across Nintendo Switch 2, PlayStation 5, and Steam, as well as a new music album. Licensing revenue expanded 218.3 % to ¥888 million, reflecting the release of overseas editions for several legacy titles and new releases such as “Eiyuu Densetsu: Kuro no Kiseki II – Crimson Sin.” Operating profit rose 670.4 % to ¥685 million, and net income climbed 498.8 % to ¥486 million, with earnings per share reaching ¥47.89 after potential dilution adjustments.
Total assets stood at ¥10,947 million, down 4.8 % from the prior year’s end, largely due to a ¥374 million drop in cash and deposits and a ¥190 million decline in accounts receivable. Net assets were ¥10,549 million, a 3.0 % decrease, after accounting for a ¥608 million share buyback and ¥205 million dividend payout. The company’s equity ratio remained robust at 96.4 %.
For the full fiscal year, Falcom forecasts revenue of ¥2,600 million (−0.5 % YoY) and net profit of ¥900 million (−0.4 %). The second‑quarter outlook projects sales of ¥1,200 million and net profit of ¥450 million, reflecting confidence in the continued momentum of “Sky: The First” while acknowledging uncertainties surrounding upcoming projects such as “Kento Zanadu – Sakura Hana Gembu.” The company maintains a single‑segment classification, with no significant changes in accounting policy or material contingencies reported.
- Nihon Falcom reported a significant Q1 2026 turnaround, with revenue surging 150.7% to ¥937 million and operating profit jumping 670.4% to ¥685 million.
- Licensing revenue was a primary growth driver, increasing 218.3% to ¥888 million due to overseas releases of legacy titles and 'Eiyuu Densetsu: Kuro no Kiseki II – Crimson Sin.'
- Strong sales of the flagship 'Trails' title 'Sky: The First' across Nintendo Switch 2, PlayStation 5, and Steam served as the core catalyst for the quarterly performance.
- The company executed a capital return strategy during the quarter, totaling ¥608 million in share buybacks and ¥205 million in dividend payouts.
- Despite the strong Q1, the company forecasts flat full-year results, projecting revenue of ¥2,600 million and net profit of ¥900 million, both down roughly 0.5% year-over-year.
+2
Nihon Falcom
Financial8 pages
Nihon Falcom Q1 FY2026 Financial Results (Japanese GAAP, Non-Consolidated)
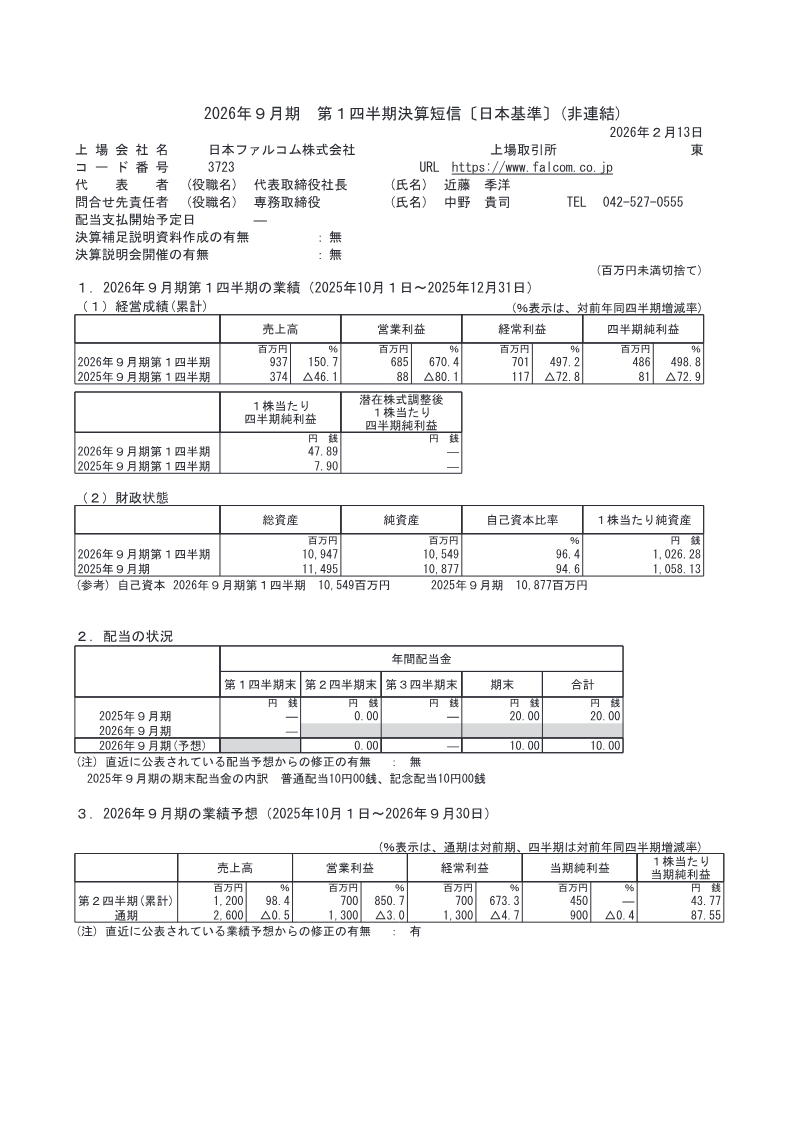
Nihon Falcom’s financial results for the first quarter of the fiscal year ending September 2026 reveal significant year-over-year growth driven by strong international licensing performance. For the three-month period ending December 31, 2025, net sales reached 937 million yen, a 150.7% increase over the previous year. Profitability saw even sharper gains, with operating income rising 670.4% to 685 million yen and net income increasing 498.8% to 486 million yen.
The licensing division served as the primary growth engine, generating 888 million yen in sales, a 218.3% increase. This surge was fueled by the global rollout of The Legend of Heroes: Trails in the Sky the 1st across multiple platforms, alongside continued international sales of the Trails and Ys series. Conversely, the product division, which handles direct domestic sales, saw revenue decline by 47.6% to 49 million yen, reflecting a period focused on development and upcoming releases.
Geographically, the results highlight a heavy reliance on global markets and multi-platform availability, including Nintendo Switch, PlayStation 5, and Steam. Looking ahead, the company has upwardly revised its mid-term forecasts due to the steady performance of its flagship titles. However, full-year forecasts remain unchanged at 2.6 billion yen in net sales, as management remains cautious regarding the timing and market reception of upcoming projects like Kyoto Xanadu and the worldwide simultaneous release of Trails in the Sky the 2nd.
The financial position remains stable with a high equity ratio of 96.4%. Total assets decreased slightly to 10.9 billion yen, primarily due to a 608 million yen share buyback and dividend payments. The company continues to focus on its single segment of game development and licensing, leveraging its established intellectual properties to maintain high profit margins.
- Nihon Falcom reported a 150.7% year-over-year increase in Q1 FY2026 net sales to 937 million yen, with operating income surging 670.4% to 685 million yen.
- The licensing division drove the majority of revenue, generating 888 million yen—a 218.3% increase—largely due to the global multi-platform rollout of 'The Legend of Heroes: Trails in the Sky the 1st'.
- Domestic product sales declined by 47.6% to 49 million yen, reflecting a strategic shift toward development cycles for upcoming titles.
- Management maintained the full-year net sales forecast at 2.6 billion yen, citing caution regarding the market reception of future projects like 'Kyoto Xanadu' and 'Trails in the Sky the 2nd'.
- The company maintains a strong financial position with a 96.4% equity ratio, despite a slight decrease in total assets to 10.9 billion yen following a 608 million yen share buyback.
Nihon Falcom CorporationFeb 2026