The 2024 financial analysis of publicly traded gaming companies evaluates the shifting landscape of global industry revenue and the significant disparity in merger and acquisition (M&A) capacity between Asia-Pacific (APAC) firms and their Western counterparts. The primary thesis posits that APAC companies, bolstered by massive cash reserves, are uniquely positioned to drive global consolidation, while Western firms focus on operational efficiency and digesting previous acquisitions.
Data from 2023 indicates a pivotal shift in market dominance, with China’s publicly traded gaming revenue estimated at $60.59 billion, surpassing the U.S. total of $50.14 billion. This financial strength is further reflected in M&A leverage; APAC giants hold approximately $61.03 billion in net cash, compared to a combined $1.65 billion for North American and EMEA companies. This liquidity gap translates to an estimated potential M&A leverage of over $222 billion for APAC, roughly 11 times the capacity of Western competitors. Furthermore, APAC companies generated $2.16 billion in net interest income, whereas Western firms collectively incurred $780 million in interest expenses.
The analysis highlights a broader industry trend toward "efficiency," characterized by reduced marketing expenditures as a percentage of revenue across most regions. Additionally, the report identifies the Saudi Arabian Public Investment Fund’s Savvy Games Group as a major market force, noting that with approximately $25 billion in uninvested capital, the entity possesses the liquidity to acquire the entire publicly traded gaming sector in EMEA. Looking forward, the industry is expected to see continued consolidation within China, driven by regulatory pressures, alongside increased strategic international expansion by APAC firms seeking to leverage their substantial cash war chests.
The analysis examines the performance of gaming-related intellectual properties on Netflix, specifically identifying the top 15 franchises by hours watched during the first half of 2023. By leveraging viewership data released by the platform, the assessment highlights the dominance of family-oriented content and the rapid growth of narrative-driven adaptations.
Pokémon leads the rankings with 261 million hours watched across 29 titles, underscoring the enduring appeal of established family-friendly franchises. Collectively, family-oriented IPs—including Sonic, Angry Birds, Cuphead, Rabbids, Wakfu, and Skylanders—account for over 56% of the total hours watched among the top 15 gaming properties. This concentration of viewership suggests a strong, consistent demand for wholesome, accessible gaming entertainment on the streaming service.
The Witcher stands out as a significant outlier, securing the second-place position with 233 million hours watched. Its performance is particularly notable for its high engagement velocity; the third season alone generated 33.4 million hours of viewership within its first two days of release. Given this trajectory, the franchise is positioned as a primary challenger to Pokémon for the top spot in future periods.
The findings illustrate a bifurcated landscape where long-standing family brands maintain a broad, stable audience, while high-production, narrative-driven sagas drive intense, short-term spikes in engagement. This data provides a clear indicator of how gaming-derived content is successfully integrated into broader streaming strategies, reflecting a diverse audience appetite for both episodic family adventures and mature, serialized storytelling.
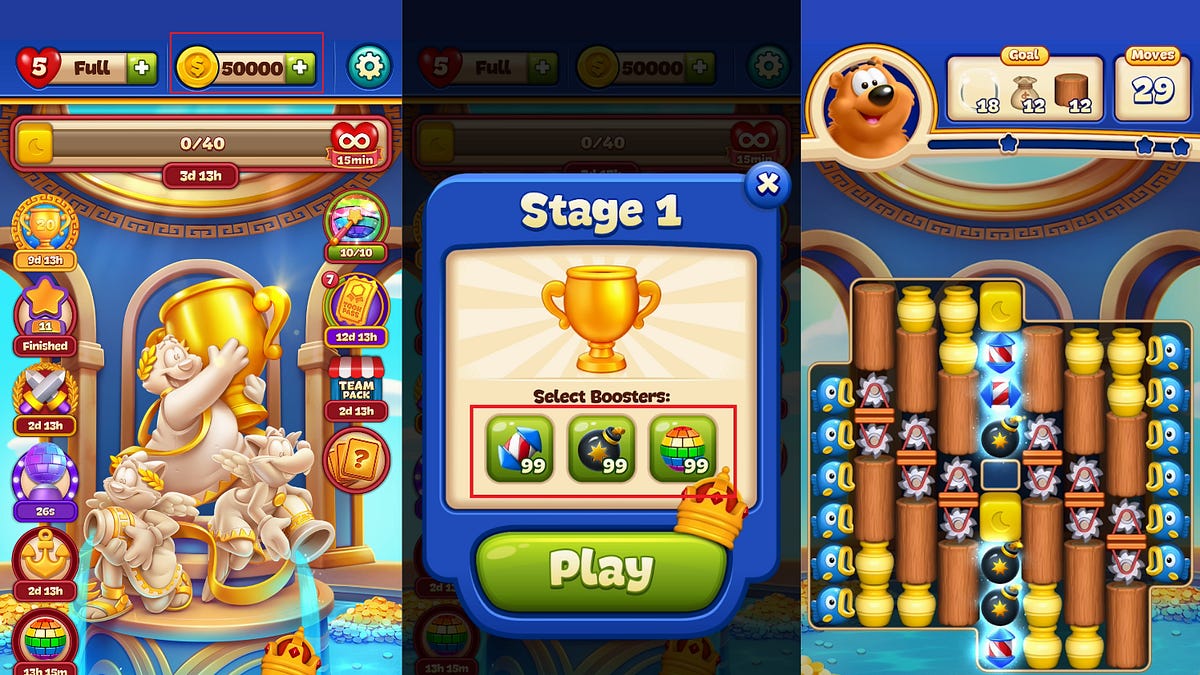
The freemium gaming model relies on sophisticated monetization strategies designed to maximize player spending through psychological triggers and algorithmic control. These games typically employ three primary revenue streams: stats-based purchases that provide competitive advantages, cosmetic or content-based items that enhance the user experience, and subscription-based perks such as battle passes or ad-free access. To drive these purchases, developers utilize a carrot-and-stick approach, which incentivizes spending through artificial scarcity, time-limited challenges, and dynamic difficulty adjustments.
A central finding is that many competitive elements in casual and mobile games are orchestrated by algorithms rather than genuine human interaction. Weekly tournaments, for instance, often feature AI-controlled participants designed to manipulate player behavior. These algorithms track login patterns and performance to create artificial pressure, forcing players into situations where they feel compelled to spend money to protect their time-invested progress. Furthermore, developers implement dynamic difficulty scaling, which acts as a soft cap on progression to ensure that content is not consumed too rapidly and that players remain consistently challenged.
The analysis suggests that these systems are pervasive across the mobile gaming sector, particularly in puzzle and casual titles. By understanding the underlying mechanics of these algorithmic symphonies, players can adopt counter-strategies—such as timing their entry into tournaments or managing their engagement with unlimited-life bonuses—to achieve better progress without resorting to real-money transactions. Ultimately, the industry’s reliance on these data-driven engagement loops highlights a shift toward highly optimized, developer-controlled environments that prioritize revenue retention over purely organic gameplay experiences.
The mobile gaming industry experienced a notable stagnation in 2022, characterized by flat revenue growth for Apple’s App Store and a decline in Google Play revenue. While Apple reported that developers earned $320 billion cumulatively since 2008—an increase of $60 billion over the 2021 total—this figure indicates that annual developer earnings remained largely unchanged year-over-year. These findings are contextualized by the implementation of reduced commission structures for smaller developers, which complicates precise revenue calculations but suggests a broader plateau in platform performance.
Industry discourse frequently attributes this slowdown to Apple’s App Tracking Transparency (ATT) framework and the deprecation of the Identifier for Advertisers (IDFA). However, the evidence suggests these privacy changes are being used as scapegoats for deeper, pre-existing issues. The industry was already trending toward a slowdown prior to the pandemic, and current market conditions are likely influenced by a combination of macroeconomic factors, the normalization of consumer behavior post-pandemic, and structural inefficiencies within the mobile gaming sector.
The analysis highlights a shift in corporate strategy, as mobile game companies move away from aggressive user acquisition and arbitrage-heavy models. Instead, there is a growing emphasis on cautious investment and high-quality user experiences. Financial data from publicly traded mobile game companies, including EBITDA margins and marketing spend, reflects this transition toward more selective resource allocation. Ultimately, the industry is undergoing a necessary correction that prioritizes sustainable game design over the rapid scaling of low-quality content, a shift that may prove beneficial for the long-term health of the mobile gaming ecosystem.