1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial report Everplay
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial reportEverplay
Everplay Group plc delivered unaudited FY 2025 results that demonstrate resilient profitability amid flat headline revenue. Total sales held steady at £166.0 million, a slight decline from the prior year, yet underlying revenue grew 5% when excluding the impact of Astragon’s exit from physical distribution. Gross profit rose to £76.3 million, achieving a 46.0% margin, while adjusted EBITDA increased 11% to £48.5 million (29.2% margin). Profit before tax surged 44% to £36.6 million, driven by higher gross margins and reduced royalty expenses.
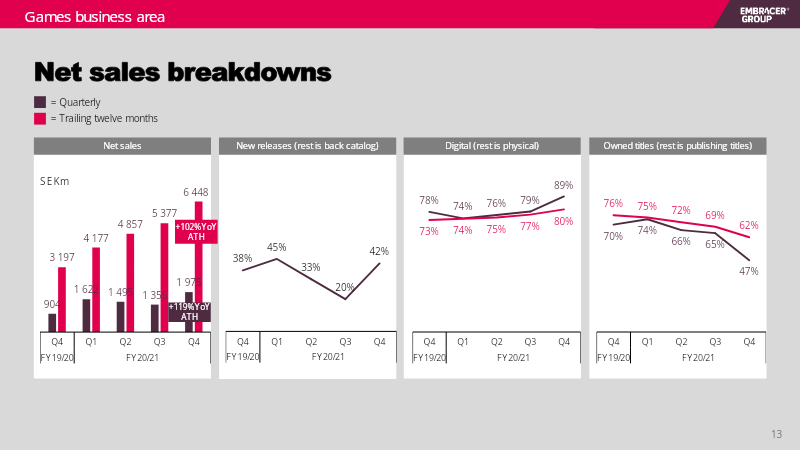
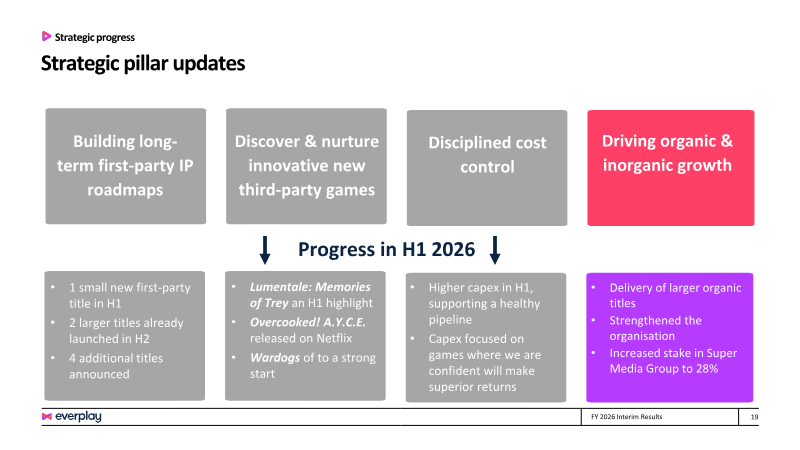
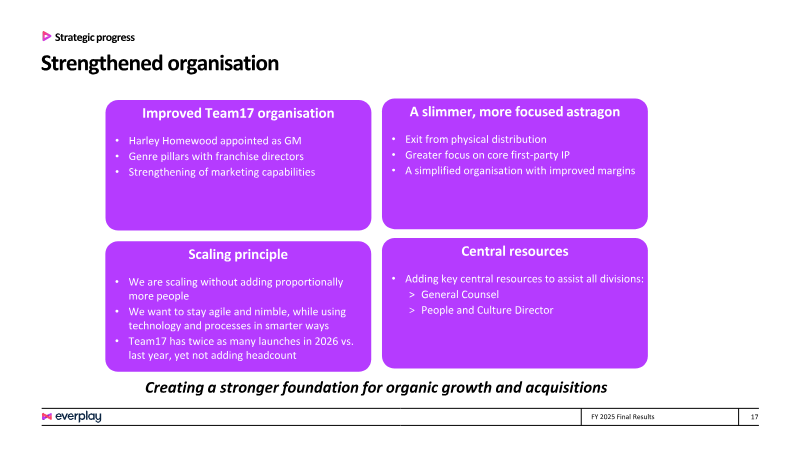
The Group’s performance was underpinned by robust new-release activity, with an 80% revenue increase from fresh titles and a 75% share of income derived from its back catalogue. Strategic initiatives—such as securing platform partnerships with Netflix Games, Apple Arcade and Amazon Game Night, exiting low-margin physical distribution, and acquiring additional IP rights—position the company for future growth. Astragon’s revenue fell 33% to £29.5 million after the distribution exit, yet its first-party IP share climbed to 83% of sales; StoryToys expanded revenue by 25% to £30.4 million, buoyed by high-profile licenses like LEGO® Bluey and Netflix Games.
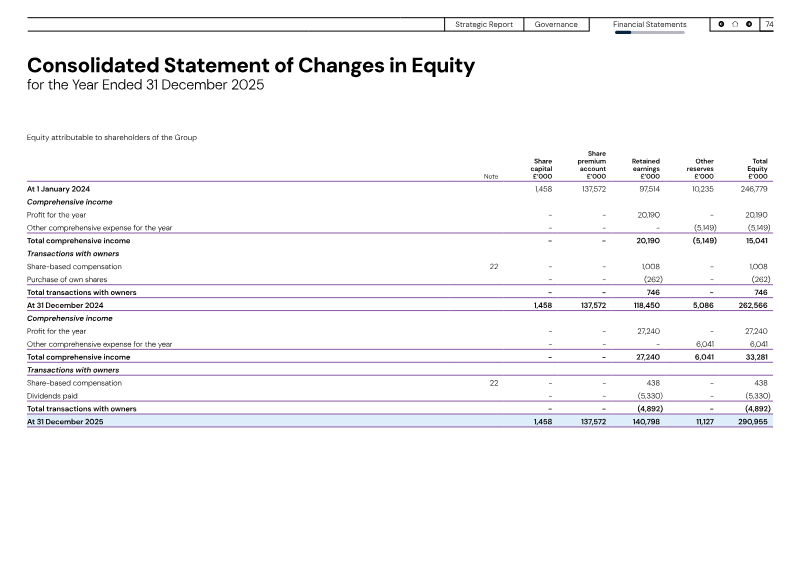
Share-based remuneration expanded, with 317,970 options granted to Executive Directors, 349,805 to other employees and 87,957 to Non-Executive Directors in FY 2025. The Long-Term Incentive Plan now covers senior divisional leaders, and an All-Employee Share Incentive Plan remains active. Outlook for FY 2026 highlights a pipeline of over 15 new games, including five first-party IP titles, and anticipates H2-weighted EBITDA growth.
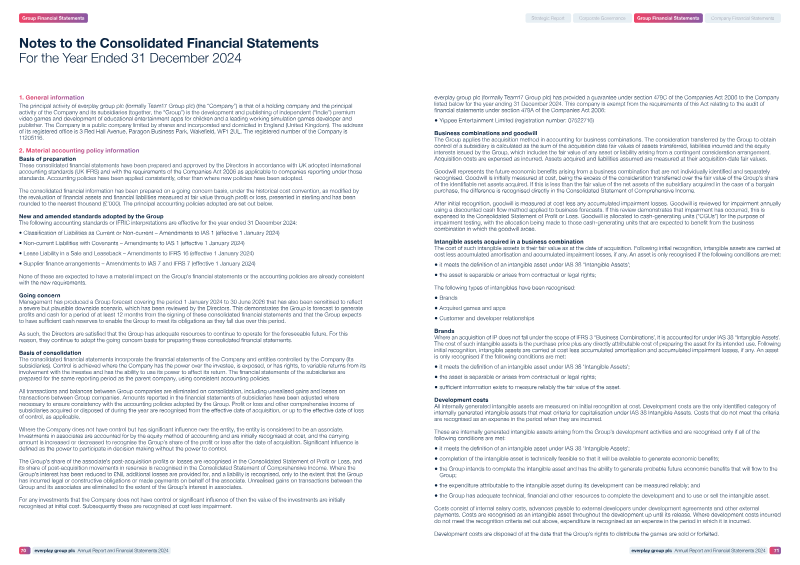
Financially, the Group reports a single aggregated segment comprising Games Label, Simulation and Edutainment. Revenue in 2025 split evenly between first-party (£56.13 m) and third-party IP (£109.86 m), with major platforms such as Steam, Microsoft, Sony, Nintendo and Apple each contributing over 10% of sales. Operating profit benefited from amortisation of development costs (£14.16 m) and publishing rights, while tax expense rose to £9.35 million from £5.13 million in 2024 due to higher current and deferred tax adjustments.
Goodwill impairment testing revealed no shortfalls except for the Astragon Simulation CGU, where recoverable amounts exceed carrying value by £78.5 million (2024: £31.0 million). Sensitivity analysis indicates that a 25% decline in unreleased title revenues would bring the Astragon CGU to breakeven, but no other reasonable changes trigger impairment. Cash balances remained robust at £51.9 million in 2025, with operating cash flow of £57.7 million slightly below the prior year’s £59.9 million, underscoring solid liquidity and a foundation for continued profitable expansion.
Everplay · 2026
Everplay · 2026
Everplay · 2026
Everplay · 2025
Everplay · 2025
Everplay · 2024
Everplay
Deconstructor of Fun · 2026