Skip to main content
Game Industry
Library
Ask AI
Cited answers
Search…
⌘
K
Library
Search
TL;DR
Connect your AI
PRO
Browse
Topics
Collections
Writers
Glossary highlights
Theme
Help & info
Subscribe
Game Industry
Library
Library
TL;DR
Search
Ask AI
Saved
Collections
Development & Publishing
Development & Publishing
Making and shipping games: design, engines, QA and publishing deals.
375 documents
Reports
Presentations
Whitepapers
Newest first
Oldest first
Title A–Z
Title Z–A
Koei Tecmo
Report
Financial Highlights: 1st Quarter of the Fiscal Year Ending March 2017
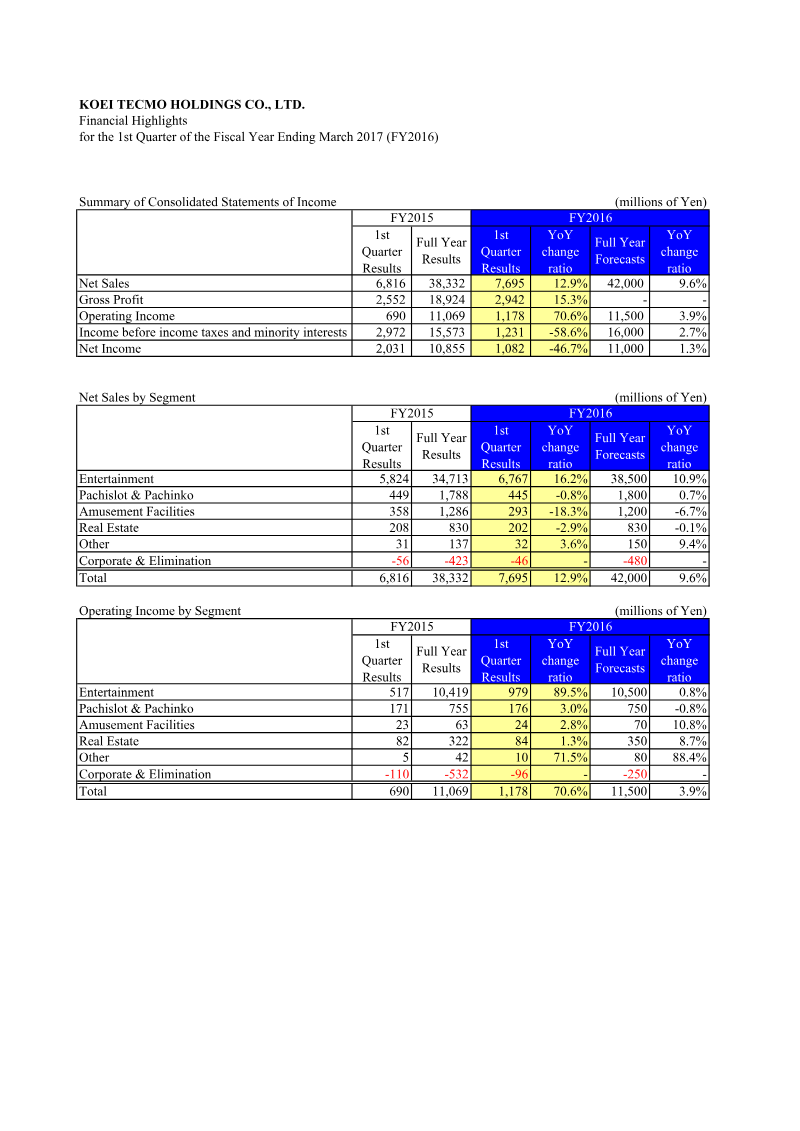
Financial highlights for the first quarter of KOEI TECMO Holdings’ fiscal year ending March 2017 reveal a robust revenue increase and strong profitability across most segments. Net sales rose 12.9 % year‑over‑year to ¥38,332 million, driven primarily by the entertainment segment, which grew 16.2 % to ¥34,713 million; pachislot & pachinko sales increased modestly by 0.8 % to ¥1,788 million, while amusement facilities and real‑estate segments contracted 18.3 % and 2.9 %, respectively. Operating income surged 70.6 % to ¥11,069 million, with the entertainment division contributing 89.5 % of this gain. Net income fell 46.7 % to ¥10,855 million, largely due to a 58.6 % decline in income before taxes and minority interests. On the balance‑sheet side, total assets contracted from ¥110.9 billion to ¥97.3 billion, largely driven by a reduction in current assets and investment securities. Current liabilities fell sharply from ¥10.6 billion to ¥4.9 billion, reflecting lower trade payables and accrued bonuses. Shareholders’ equity decreased from ¥99.0 billion to ¥94.7 billion, with retained earnings declining from ¥60.0 billion to ¥55.6 billion. Net assets fell from ¥98.7 billion to ¥91.0 billion, and accumulated other comprehensive income shifted from a negative ¥523 million to a positive ¥3.9 billion, largely due to foreign‑currency translation adjustments. The data cover Japan‑based operations for the fiscal year ending March 2016, with quarterly figures reported as of June 30 2016. The report aggregates consolidated financial statements without detailing survey methodology, relying instead on standard accounting disclosures.
Koei Tecmo
Report
Koei Tecmo Holdings Financial Summary: FY2024 3Q
Koei Tecmo Holdings reported FY2024 Q3 results, showing a 17.6 % decline in consolidated sales to ¥14,677 million versus ¥16,109 million in Q2 and a 25.4 % drop from the same period in FY2023. Gross profit fell to ¥8,392 million, reflecting higher cost of sales (¥6,285 million) and a lower gross margin of 32 % compared with 41 % in Q2. Operating profit contracted to ¥4,673 million (profit ratio 32 %) from ¥6,664 million in Q2 and 41 % in FY2023 Q3. Ordinary profit turned negative for the first time in the quarter, at ¥(787) million, largely due to a ¥5,461 million non‑operating loss. Net profit was ¥(171) million, a reversal from the ¥6,898 million gain in Q2. Segment analysis indicates entertainment sales dominated at ¥13,515 million (92 % of total), with console/PC and digital downloads each contributing roughly ¥5–6 million. Amusement revenue remained modest at ¥794 million, while real‑estate income was negligible. Regional sales were strongest in Japan (¥7,890 million) and Asia excluding Japan (¥5,232 million), with North America and Europe contributing ¥1,087 million and ¥468 million respectively. Expenses rose in cost of sales (¥6,285 million) and SG&A (¥3,718 million). Employment costs increased to ¥5,200 million, and outsourcing expenses climbed to ¥1,400 million. Digital download units accounted for 75 % of total sales units in Q3, up from 73.9 % in Q2, indicating a continued shift toward digital channels. Headcount remained steady at 2,400 employees. Capital expenditures for FY2024 were ¥1,967 million, with real‑estate investment at ¥1,631 million and depreciation expense at ¥1,776 million. The data cover the Japanese market and overseas regions for FY2024 Q3, with comparative figures from FY2023.
GREE
Report
Summary of Questions and Answers: FY2017 2Q GREE Results Briefing
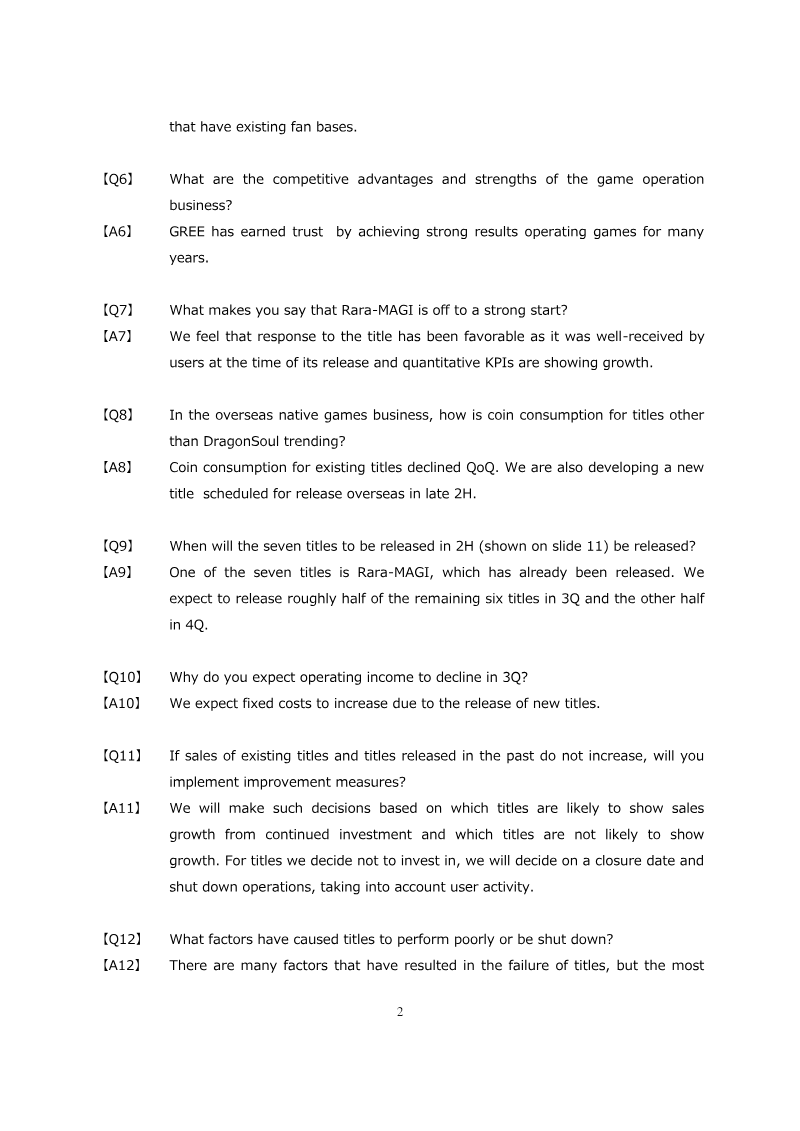
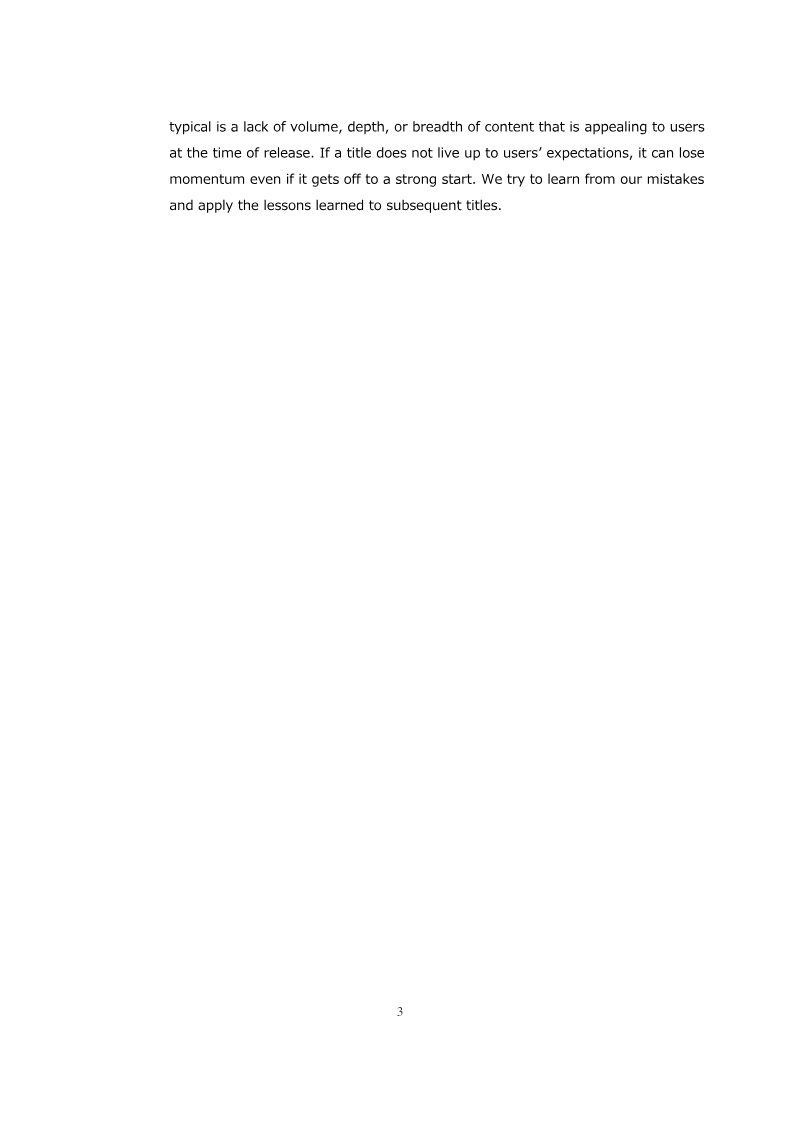
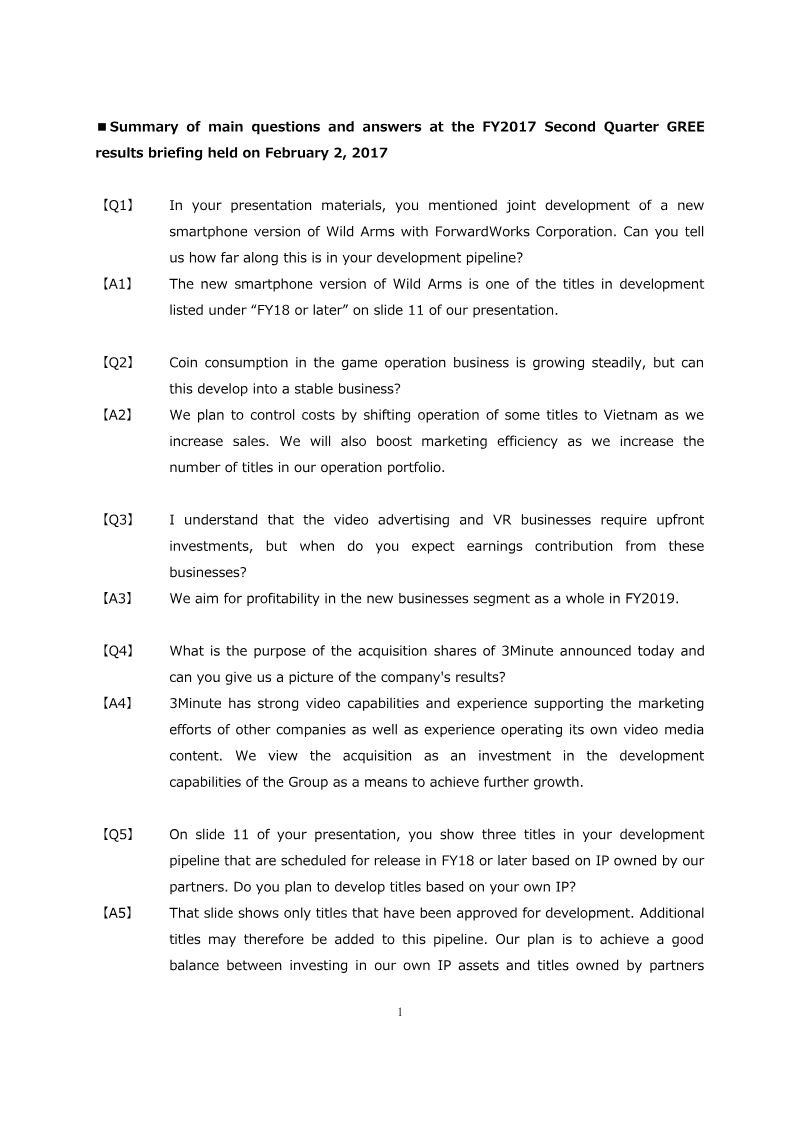
The briefing clarified GREE’s strategic focus for FY2017 and beyond. The company confirmed that a smartphone adaptation of Wild Arms, developed with ForwardWorks Corporation, remains in the FY18‑later pipeline. To stabilize coin‑consumption revenue from its game operation segment, GREE plans to shift operations of select titles to Vietnam and enhance marketing efficiency as its portfolio expands. New ventures in video advertising and virtual reality are expected to reach profitability by FY2019, while the acquisition of 3Minute is positioned as an investment in video‑content capabilities to support broader growth. Regarding intellectual property, GREE indicated that its development pipeline includes both partner‑owned IP and its own assets, aiming for a balanced mix. The company highlighted Rara‑MAGI’s strong launch performance and noted that coin consumption for other overseas native titles has declined quarter‑over‑quarter, though a new title is slated for late second half release. Seven titles scheduled for the latter half of the year will see roughly half released in Q3 and the remainder in Q4, with Rara‑MAGI already live. Operating income is projected to dip in Q3 due to increased fixed costs from new releases. GREE will evaluate ongoing titles, closing those unlikely to grow while reallocating resources to high‑potential games. Poor performance is attributed mainly to insufficient content depth or breadth at launch, and lessons learned will inform future development.
GREE
Report
FY2018 2Q Result Presentation
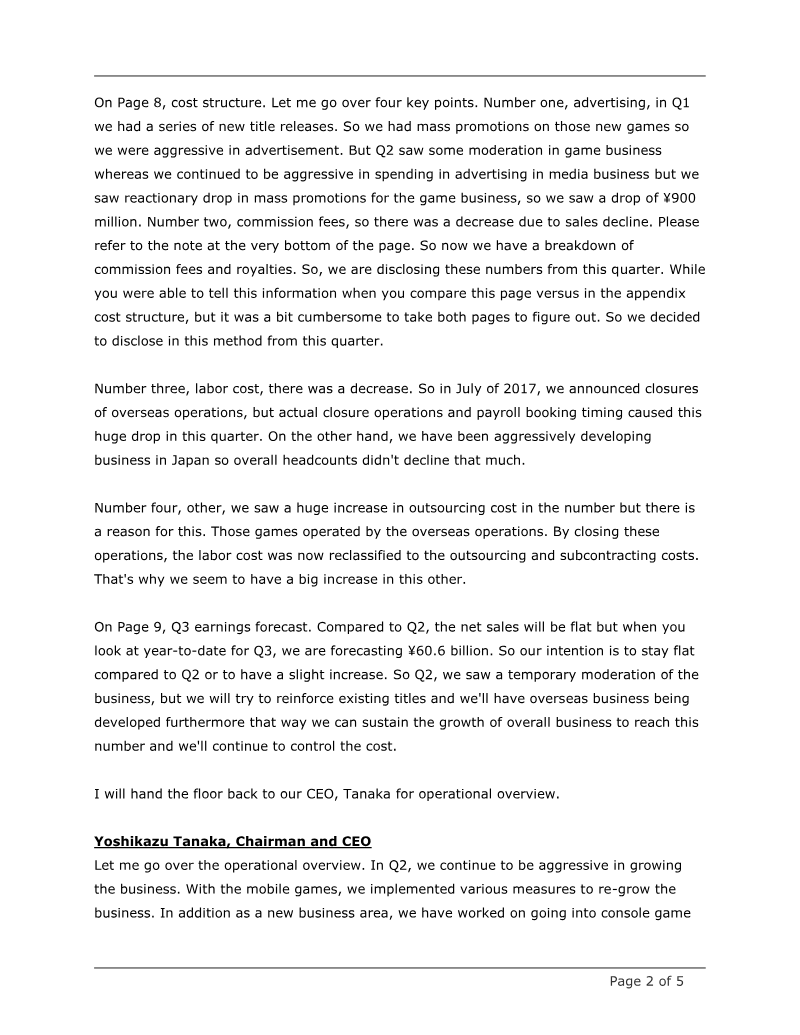
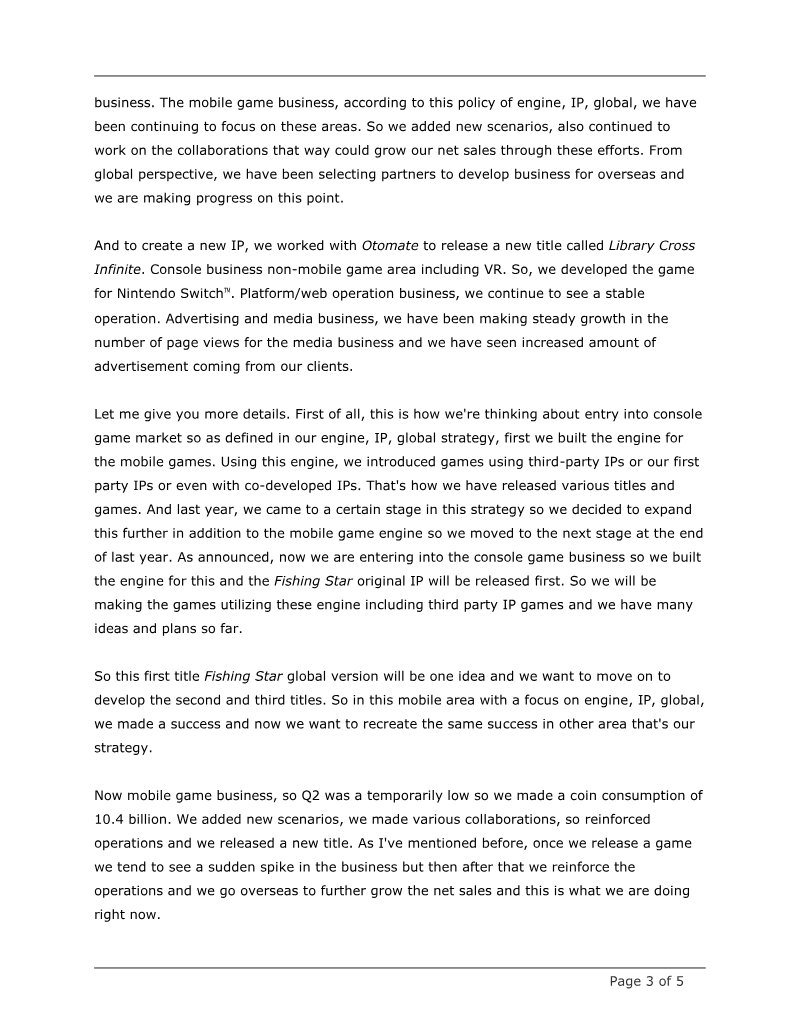
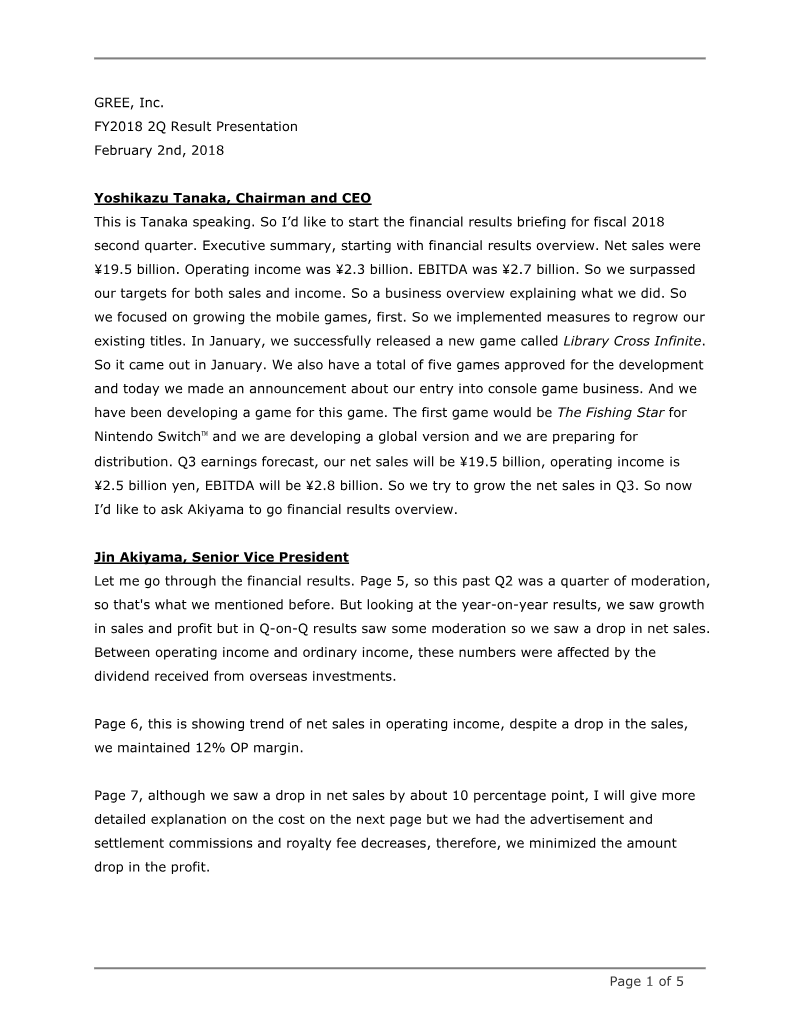
GREE, Inc. reported FY2018 second‑quarter results on February 2, 2018, with net sales of ¥19.5 billion and operating income of ¥2.3 billion, exceeding targets for both metrics. EBITDA reached ¥2.7 billion. Year‑on‑year growth was achieved, though quarter‑over‑quarter sales moderated by roughly 10 percentage points; operating margin remained at 12 %. The company attributed the sales dip to reduced advertising spend and lower commission fees, while cost controls on labor and outsourcing mitigated profit erosion. A strategic shift toward console gaming was announced, with the first title “The Fishing Star” slated for Nintendo Switch and a global release in development. Mobile game performance was bolstered by the launch of “Library Cross Infinite” and ongoing content updates for titles such as Another Eden, Danmachi, SINoALICE, SYMPHOGEAR, and Puchiguru Love Live. Five new mobile titles are approved for development, with three slated for release this fiscal year. The FY2018 Q3 forecast projects flat net sales at ¥19.5 billion and operating income of ¥2.5 billion, aiming for a year‑to‑date total of ¥60.6 billion. GREE plans to sustain growth through aggressive title reinforcement, overseas expansion, and cost discipline across mobile, console, VR, advertising, and media segments. The presentation covered financial performance, cost structure adjustments following overseas operation closures, and a pipeline of upcoming releases across multiple platforms.
GREE
Report
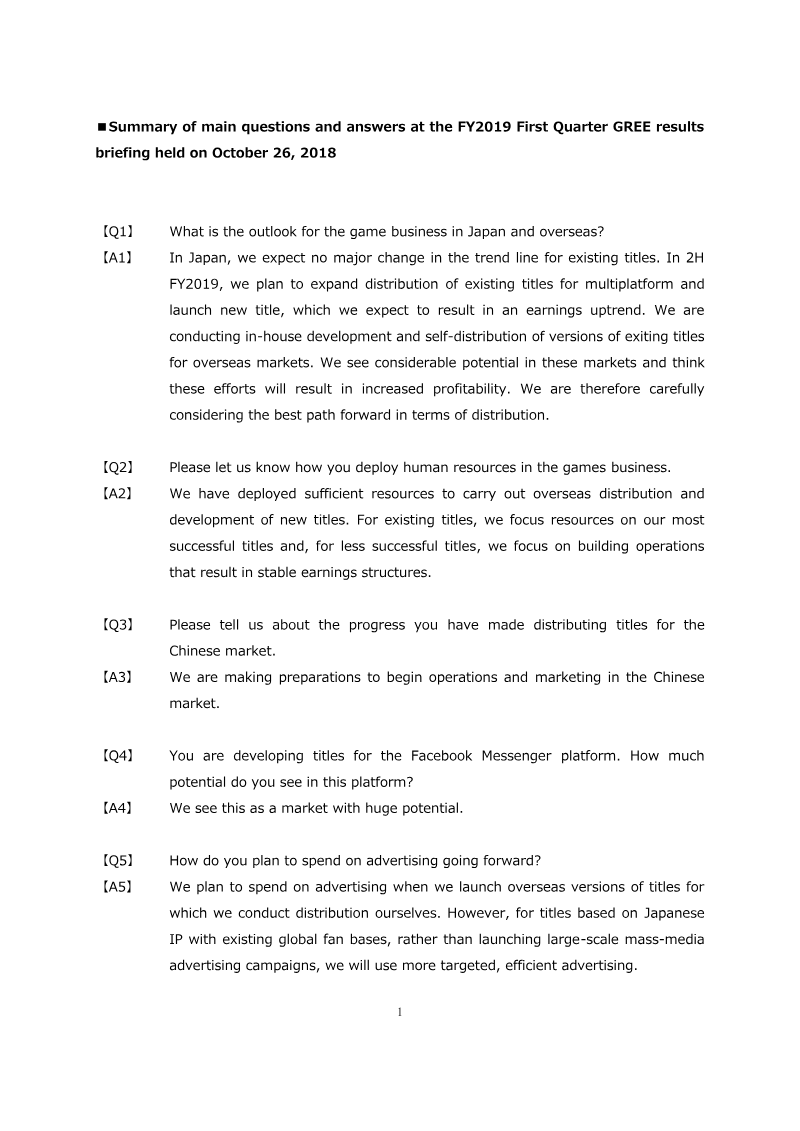
Summary of main questions and answers at the FY2019 First Quarter GREE results briefing held on October 26, 2018
The briefing clarified GREE’s strategic outlook for FY2019, emphasizing a steady domestic game portfolio while pursuing growth overseas. In Japan, the company expects no major shift in performance for existing titles but plans to broaden multiplatform distribution and launch new releases in the second half of FY2019, projecting an earnings uptrend. Internationally, GREE is developing and self‑distributing overseas versions of current titles, targeting markets with high profitability potential. Human resource allocation reflects this focus: sufficient staff are dedicated to overseas distribution and new title development, while existing titles receive concentrated support for top performers and operational stability for less successful ones. China is identified as a priority market, with preparations underway to initiate operations and marketing. The company also highlights the Facebook Messenger platform as a high‑potential channel for new titles, indicating an expansion into social media gaming. Advertising strategy will be selective; overseas launches of self‑distributed titles will receive targeted, efficient campaigns rather than broad mass media spend. Regulatory compliance and consumer protection are addressed through company‑wide measures to prevent gacha system issues, including strengthened evaluation protocols and employee training. The REALITY livestreaming platform for VTubers is in an exploratory phase, with ongoing data collection on technology, planning, and marketing to build know‑how for future content expansion. Overall, GREE’s FY2019 strategy balances domestic stability with aggressive international diversification and platform innovation.
GREE
Report
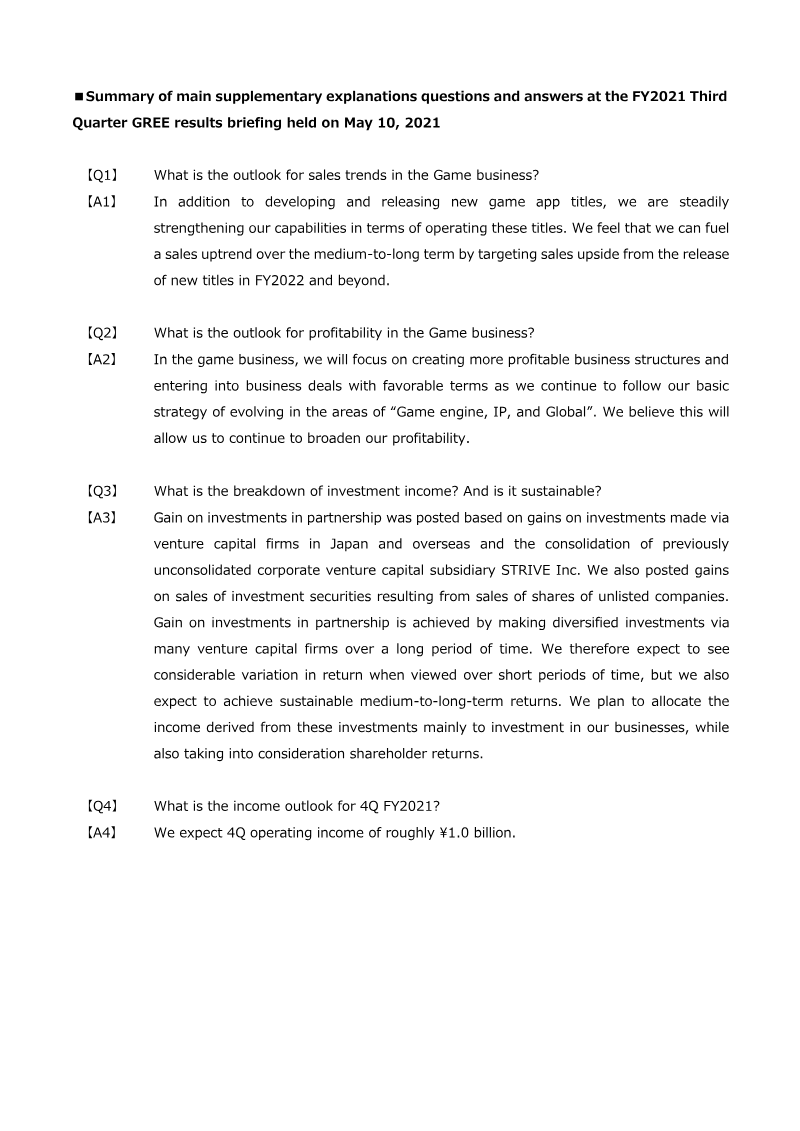
Summary of Main Supplementary Explanations Questions and Answers: FY2021 Third Quarter GREE Results Briefing
The briefing outlines GREE’s strategic outlook for the remainder of FY2021 and beyond, focusing on its core Game business, profitability trajectory, investment income sustainability, and short‑term financial expectations. GREE anticipates a medium‑to‑long‑term sales uptrend driven by the release of new game titles in FY2022 and subsequent years, while simultaneously strengthening operational capabilities for existing titles. Profitability is expected to broaden through the creation of more profitable business structures and favorable contractual terms, aligned with a strategy centered on Game engine development, intellectual property acquisition, and global expansion. Investment income derives primarily from gains on venture‑capital partnerships in Japan and overseas, as well as the consolidation of previously unconsolidated subsidiary STRIVE Inc. The company notes that short‑term returns may fluctuate due to diversified investment portfolios, but medium‑to‑long‑term sustainability is projected. Planned allocation of these gains targets reinvestment in core businesses and shareholder returns. Financially, GREE projects operating income for the fourth quarter of FY2021 at approximately ¥1.0 billion, reflecting confidence in its current revenue streams and cost management. The briefing covers Japan’s domestic market with implications for global expansion, covering the period up to FY2021 and projecting into FY2022. Methodological details are limited, but the focus remains on strategic investment, operational efficiency, and incremental revenue growth.
GREE
Report
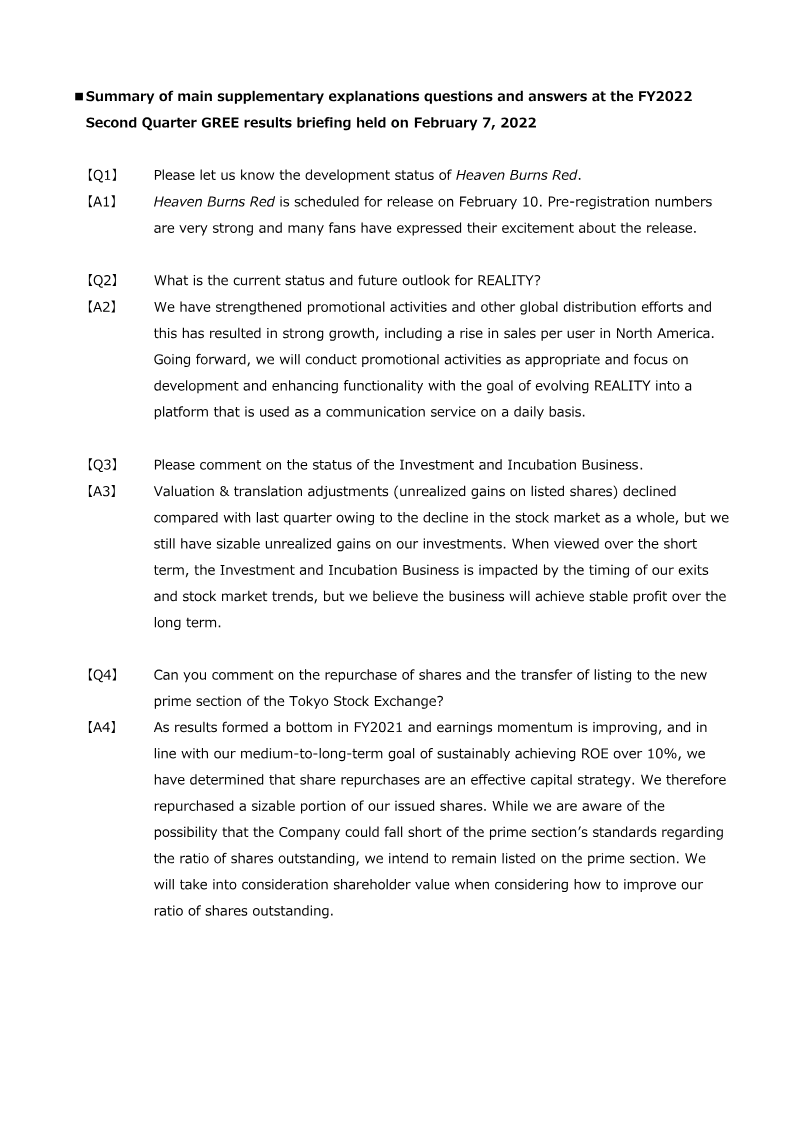
Summary of Main Supplementary Explanations Questions and Answers: GREE FY2022 Second Quarter Results
The briefing clarifies GREE’s strategic focus and financial outlook for the second quarter of FY2022. The company announces that “Heaven Burns Red” will launch on February 10, noting strong pre‑registration figures and fan enthusiasm. For the “REALITY” platform, GREE reports accelerated promotional efforts that have boosted North American sales per user; future plans emphasize continued marketing and feature development to position REALITY as a daily communication service. In the Investment and Incubation Business, unrealized gains on listed shares have fallen due to broader market declines, yet the firm maintains sizable gains and expects long‑term profitability despite short‑term exit timing effects. Capital strategy is highlighted through a substantial share repurchase program aimed at sustaining an ROE above 10 % and maintaining listing status in the Tokyo Stock Exchange’s prime section, even as share‑outstanding ratios approach regulatory thresholds. The “Money held in trust” line item is explained as short‑term, low‑risk investments treated similarly to cash. Finally, the company projects third‑quarter operating income for its Internet and Entertainment segment between ¥1.5 billion and just under ¥2.0 billion, driven by contributions from new titles. Overall, the presentation outlines GREE’s product rollout plans, market expansion tactics, investment portfolio resilience, capital allocation priorities, and near‑term earnings expectations within the broader context of a recovering market environment.
GREE
Report
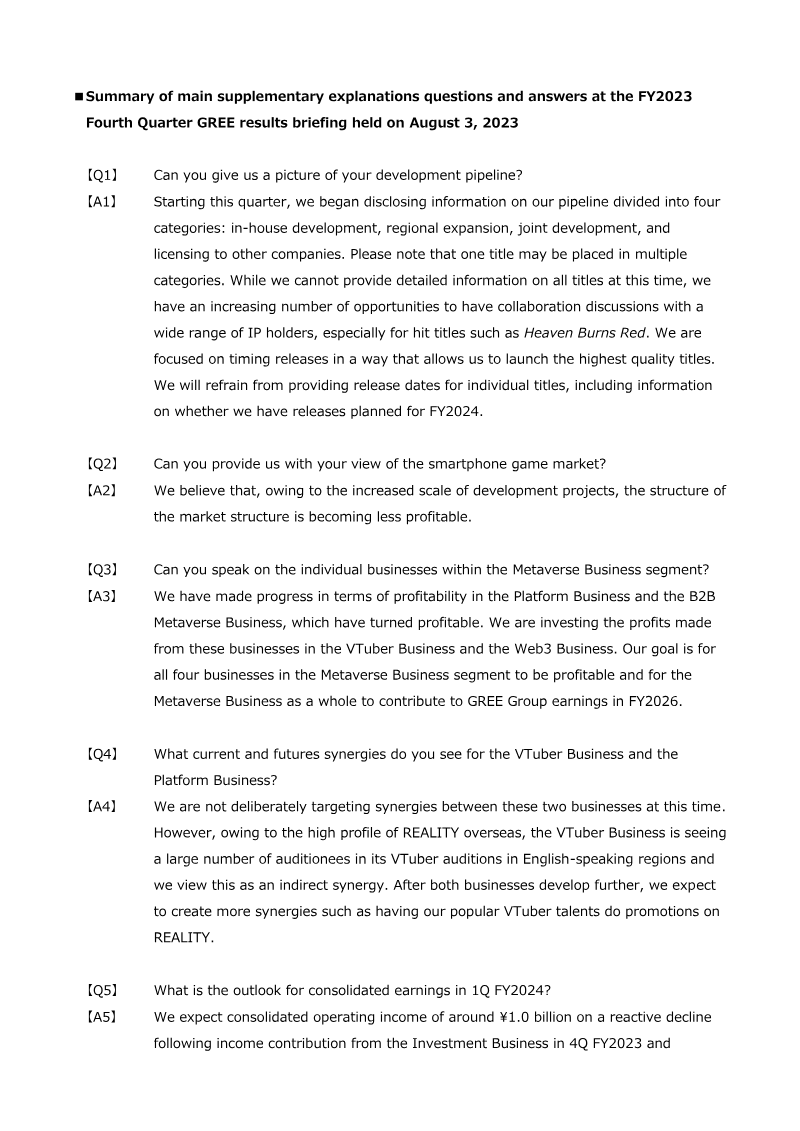
Summary of Main Supplementary Explanations Questions and Answers: FY2023 Fourth Quarter
The briefing outlines GREE’s strategic direction for FY2023‑FY2026, emphasizing a diversified portfolio beyond core gaming. In the fourth quarter, the company began categorizing its development pipeline into in‑house, regional expansion, joint development, and licensing, noting increased collaboration prospects with major IP holders such as Heaven Burns Red. Release dates remain undisclosed for FY2024 titles, reflecting a focus on quality over speed. GREE views the smartphone game market as increasingly less profitable due to larger development scales, prompting a shift toward higher‑margin ventures. Within the Metaverse Business segment, Platform and B2B sub‑segments have achieved profitability; profits are being reinvested into the VTuber and Web3 businesses. The company aims for all four Metaverse sub‑segments to be profitable by FY2026, contributing significantly to group earnings. Synergies between the VTuber and Platform businesses are currently indirect, driven by international talent recruitment for REALITY. Future cross‑promotions are anticipated once both units mature. Financial outlooks indicate a consolidated operating income of approximately ¥1.0 billion for Q1 FY2024, with a full‑year target of ¥4.0–5.0 billion for FY2024, excluding new game or anime contributions and investment income. For FY2026, the company projects similar operating income levels while targeting a 10 % return from its Investment Business and aiming for half of non‑investment earnings to derive from non‑game, non‑anime sources. This reflects a medium‑term strategy of expanding stable revenue streams beyond traditional gaming.
GREE
Report
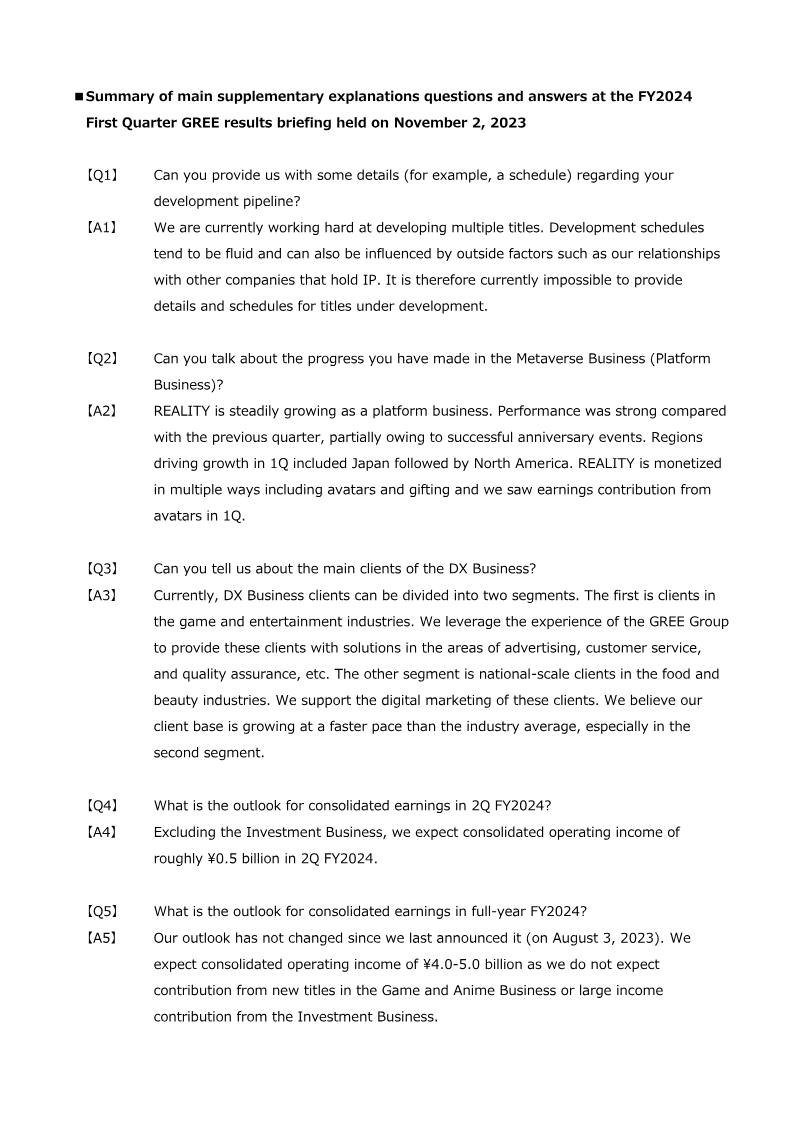
Summary of Main Supplementary Explanations Questions and Answers: FY2024 First Quarter GREE Results Briefing
The briefing clarified GREE’s strategic focus and financial outlook for FY2024. Development activities remain fluid, with no concrete release schedule disclosed due to external IP dependencies and shifting priorities. In the Metaverse platform segment, the REALITY service showed robust growth in the first quarter, driven by Japan and North America. Monetization diversified across avatars and gifting, contributing to earnings from the platform business. The DX Business continues to expand its client base, split between game and entertainment firms—leveraging GREE’s expertise in advertising, customer service, and quality assurance—and national‑scale food and beauty companies that benefit from digital marketing support. Growth in the latter segment is noted to outpace industry averages. Financial projections for the second quarter exclude investment activities, estimating consolidated operating income around ¥0.5 billion. Year‑end guidance remains unchanged from the August 3, 2023 announcement, targeting consolidated operating income between ¥4.0 and ¥5.0 billion for FY2024, with no significant impact expected from new game or anime titles or the investment arm. The company’s emphasis on platform monetization and diversified DX services underpins its confidence in maintaining steady earnings growth amid a competitive digital landscape.
GREE
Report
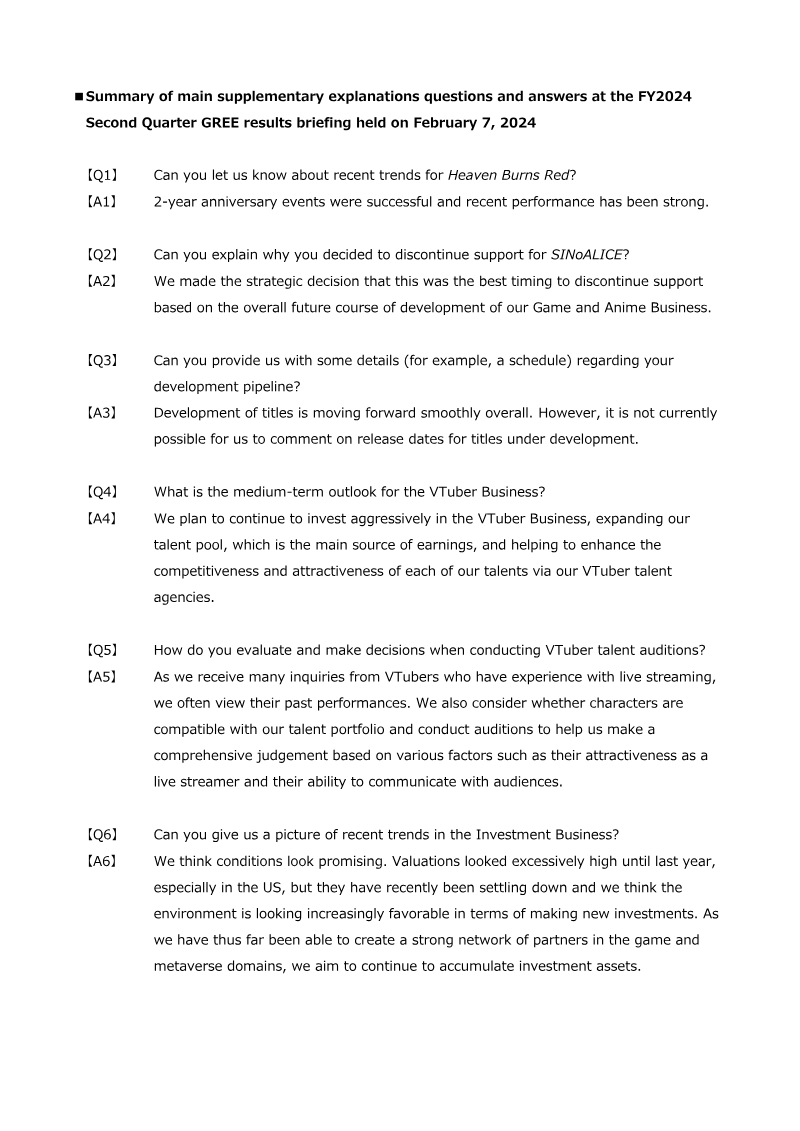
Summary of Main Supplementary Explanations Questions and Answers: FY2024 Second Quarter
The briefing clarified GREE’s strategic priorities and financial outlook for the second quarter of FY2024. Recent events for Heaven Burns Red celebrated its two‑year anniversary, generating strong performance and reinforcing the company’s focus on successful titles. The decision to discontinue support for SINoALICE was framed as a timing choice aligned with the broader development trajectory of GREE’s Game and Anime Business, indicating a shift toward more promising projects. Development activities continue to progress smoothly, though specific release dates remain undisclosed. In the VTuber segment, GREE plans aggressive investment to expand its talent pool and enhance competitiveness through its talent agencies. Talent auditions are evaluated on past streaming performance, character fit with the existing portfolio, and audience engagement capabilities. Investment business conditions are described as improving; after a period of inflated valuations—particularly in the United States—market values have stabilized, creating a favorable environment for new investments. GREE’s established network in gaming and metaverse sectors positions it to accumulate additional investment assets. Financial projections for the third quarter exclude the Investment Business, estimating consolidated operating income of approximately ¥1.5 billion. For the full fiscal year FY2024, the company forecasts consolidated operating income of roughly ¥5.0 billion under the same exclusion. These figures suggest a steady growth trajectory driven by core gaming, anime, and VTuber operations while maintaining a cautious stance on investment activities.
GREE
Report
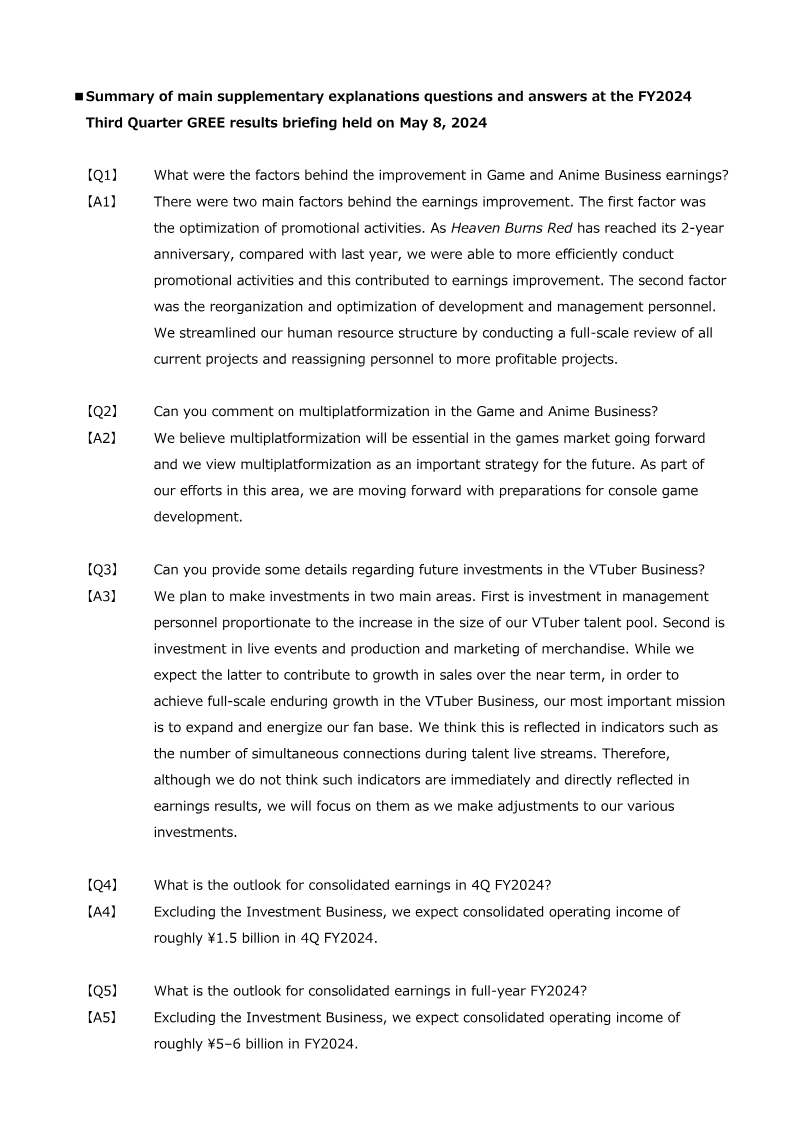
Summary of Main Supplementary Explanations Questions and Answers: FY2024 Third Quarter Results Briefing
The briefing clarified that the FY2024 third‑quarter earnings improvement in GREE’s Game and Anime Business stemmed from two primary initiatives: a more efficient promotional strategy following the second anniversary of “Heaven Burns Red,” and a comprehensive reorganization that reassigned staff to higher‑margin projects. The company emphasized multiplatformization as a strategic priority, noting active preparations for console game development to capture broader market segments. In the VTuber segment, planned investments focus on expanding management capacity in line with a growing talent roster and enhancing live‑event production, merchandise marketing, and fan engagement metrics such as concurrent viewer counts. While these initiatives are expected to drive near‑term sales, the company views sustained growth as contingent on deepening fan base loyalty. Financial outlooks presented exclude investment business figures. Consolidated operating income for the fourth quarter is projected at approximately ¥1.5 billion, and full‑year FY2024 earnings are estimated between ¥5–6 billion. These targets reflect the company’s confidence in its streamlined operations and strategic expansion across gaming, anime, and VTuber platforms.
GREE
Report
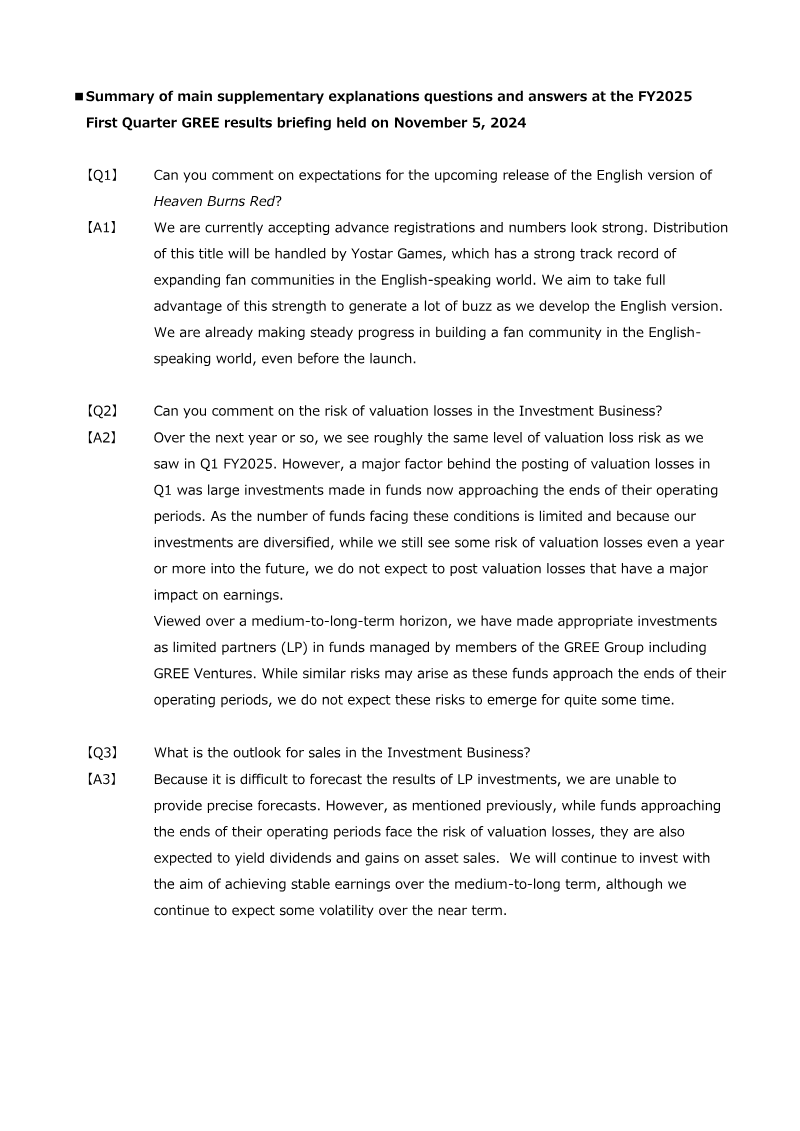
Summary of main supplementary explanations questions and answers at the FY2025 First Quarter GREE results briefing held on November 5, 2024
The briefing clarified GREE’s strategic focus for FY2025 first‑quarter results, emphasizing both gaming and investment operations. In the gaming segment, the company confirmed that advance registrations for the English version of “Heaven Burns Red” are strong and that distribution will be handled by Yostar Games, whose track record in expanding English‑speaking fan communities is expected to generate significant buzz. GREE highlighted ongoing community building efforts prior to launch, underscoring a proactive marketing approach. Regarding the investment business, management acknowledged that valuation‑loss risk remains comparable to Q1 FY2025 levels. The primary driver of past losses was large investments in funds nearing the end of their operating periods; however, diversification and limited exposure to such funds mitigate long‑term impact. GREE maintains that while short‑term volatility may persist, medium‑to‑long‑term earnings should remain stable as funds mature and yield dividends or asset sales. The company reiterated its commitment to investing in GREE‑Group managed funds, including GREE Ventures, and expects related risks to surface only after several years. Overall, the briefing presented a balanced outlook: aggressive growth in the gaming arm through strategic partnerships and community engagement, coupled with cautious yet steady investment practices aimed at preserving earnings stability amid inherent valuation risks.
Previous
1
…
5
6
7
…
32
Next