COLOPL
Game Co.13 documents
Documents
Financial10 pages
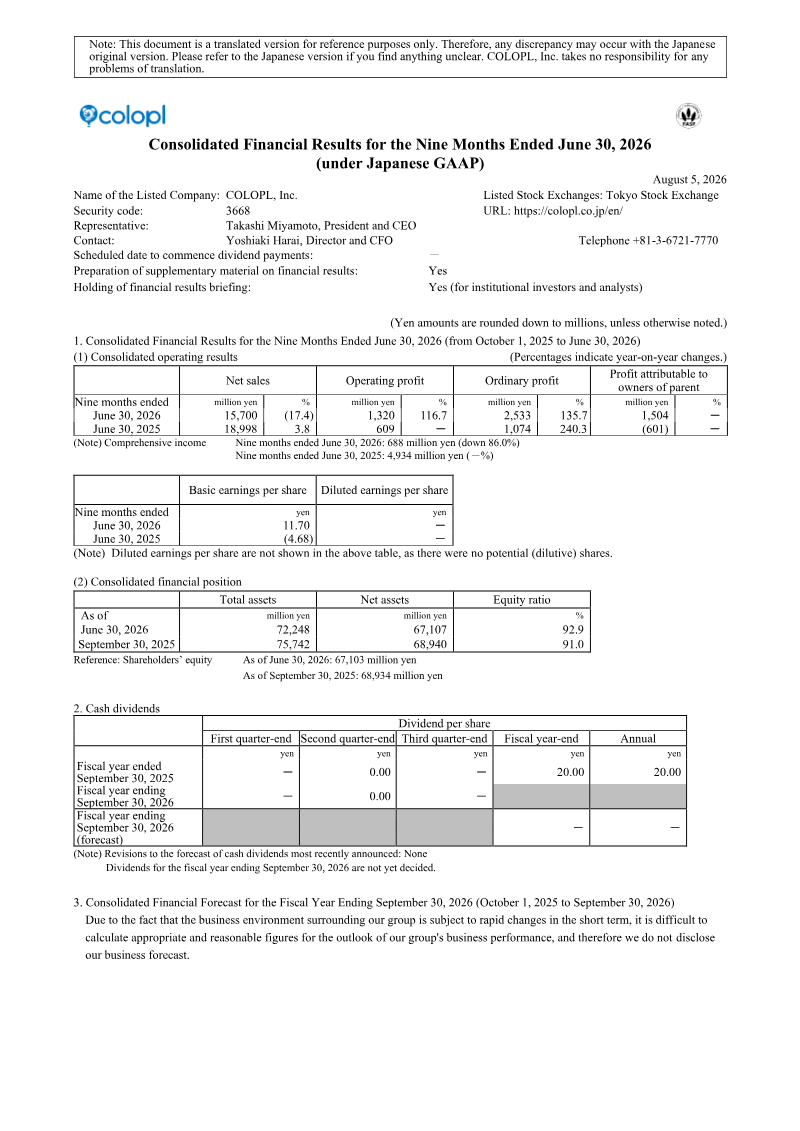
Consolidated Financial Results for the Nine Months Ended June 30, 2026: Japan
COLOPL, Inc. reported its consolidated financial results for the nine-month period ending June 30, 2026, reflecting a strategic shift toward cost optimization and improved profitability despite a decline in top-line revenue. The company operates primarily within the Japanese entertainment and investment sectors, focusing on smartphone game development and IT-related investments.
Financial performance for the period showed net sales of 15,700 million yen, a 17.4% decrease compared to the same period in the previous year. Despite this revenue contraction, the company achieved a significant turnaround in profitability, with operating profit rising 116.7% to 1,320 million yen and ordinary profit increasing 135.7% to 2,533 million yen. Profit attributable to owners of the parent reached 1,504 million yen, recovering from a 601 million yen loss in the prior year. This improved bottom-line performance was largely driven by a group-wide reduction in advertising and operational expenses within the Entertainment Business, which offset the impact of declining sales from legacy titles.
The Entertainment Business, anchored by the title Dragon Quest Walk, generated 14,676 million yen in sales. Meanwhile, the Investment and Development Business recorded 1,023 million yen in sales, a 52.2% decline attributed to the absence of large-scale deals that occurred in the previous year and the recognition of impairment losses on certain securities. As of June 30, 2026, the company maintained a strong financial position with total assets of 72,248 million yen and an equity ratio of 92.9%. Due to the volatility of the current business environment, the company has opted not to disclose specific earnings forecasts for the remainder of the fiscal year.
- COLOPL, Inc. achieved a significant profit turnaround for the nine months ending June 30, 2026, reporting a net profit of 1,504 million yen compared to a 601 million yen loss in the same period last year.
- Operating profit surged 116.7% to 1,320 million yen and ordinary profit rose 135.7% to 2,533 million yen, despite a 17.4% decline in net sales to 15,700 million yen.
- Profitability improvements were driven by aggressive cost-cutting measures, specifically a group-wide reduction in advertising and operational expenses within the Entertainment Business.
- The Entertainment Business remains the primary revenue driver, generating 14,676 million yen, largely anchored by the performance of the title Dragon Quest Walk.
- The Investment and Development Business saw a 52.2% revenue decline to 1,023 million yen, impacted by the absence of large-scale deals and the recognition of impairment losses on securities.
+1
COLOPL
Financial38 pages
3Q FY Sep. 2026 Financial Results Presentation: Japan
Financial Results Presentation Note: This document is a translated version for reference purposes only. Therefore, any discrepancy may occur with the Japanese original version. Please refer to the Japanese version if you find anything unclear. COLOPL, Inc. takes no responsibility for any problems of translation.
- COLOPL achieved a financial turnaround in 3Q FY2026, reporting 5.6 billion yen in total sales (up 13.2% YoY) and an operating profit of 0.7 billion yen, compared to an 804 million yen operating loss in the same period last year.
- The Investment and Development business segment saw significant growth, with sales reaching 0.7 billion yen—a 600.2% increase YoY—and contributing 0.3 billion yen to operating profit.
- The core Entertainment business generated 4.8 billion yen in sales, maintaining steady performance with a 0.2% YoY increase, supported by collaboration events for titles like 'Alice Gear Aegis' and 'Quiz RPG: The World of Mystic Wiz'.
- COLOPL announced the upcoming release of a new game, 'Active Cinema RPG 369', and confirmed that a console title, 'Shironeko Project INFINITY', is scheduled for launch in 2027.
- The company reported a net profit of 0.6 billion yen for the quarter, reflecting a net profit margin of 12.1% and a recovery from the 779 million yen net loss recorded in 3Q FY2025.
+1
COLOPL
Financial29 pages
3Q FY Sep. 2026 Financial Results Presentation: Japan
COLOPL’s financial results for the third quarter of the fiscal year ending September 30, 2026, demonstrate a successful turnaround to profitability, driven by robust performance in its core mobile gaming portfolio and strategic exits within its investment arm. The company reported consolidated sales of 5.6 billion yen, representing a 13.2% year-on-year increase, and an operating profit of 0.7 billion yen. This financial recovery was supported by disciplined cost optimization, particularly in advertising expenditures, and significant gains from the secondary sale of shares in an investee company.
The Entertainment Business remains the primary revenue driver, contributing 4.8 billion yen in sales. Performance was bolstered by sustained engagement with major mobile titles, including DRAGON QUEST WALK and Shironeko Project, the latter of which celebrated its 12th anniversary during the quarter. The Investment and Development Business also saw substantial growth, with sales rising by 600.2% year-on-year to 0.7 billion yen, largely due to the divestment of SALOWIN Co., Ltd. The company maintains a strong financial position, characterized by an equity ratio of 92.9% and a stable balance of operational investment securities totaling 8.8 billion yen.
Looking forward, the company is executing a mid-term management strategy aimed at achieving "Global Top 20" status in the mobile game market, targeting 100 billion yen in sales and 50 billion yen in operating profit. Future growth initiatives include the development of new location-based games, the upcoming release of the "Active Cinema RPG 369," and the expansion of its console footprint with the 2027 launch of Shironeko Project INFINITY. Additionally, the company continues to leverage its XR and digital twin technologies through its subsidiary, 360Channel, to diversify its service offerings beyond traditional gaming.
- COLOPL returned to profitability in 3Q FY2026 with 5.6 billion yen in consolidated sales, a 13.2% year-on-year increase, and an operating profit of 0.7 billion yen.
- The Entertainment Business generated 4.8 billion yen in sales, supported by the continued performance of core titles DRAGON QUEST WALK and the 12th-anniversary milestone of Shironeko Project.
- The Investment and Development Business saw a 600.2% year-on-year sales increase to 0.7 billion yen, primarily driven by the divestment of SALOWIN Co., Ltd.
- The company maintains a strong balance sheet with an equity ratio of 92.9% and 8.8 billion yen in operational investment securities.
- COLOPL is targeting long-term growth of 100 billion yen in sales and 50 billion yen in operating profit as part of its 'Global Top 20' mid-term management strategy.
+1
COLOPL
Financial2 pages
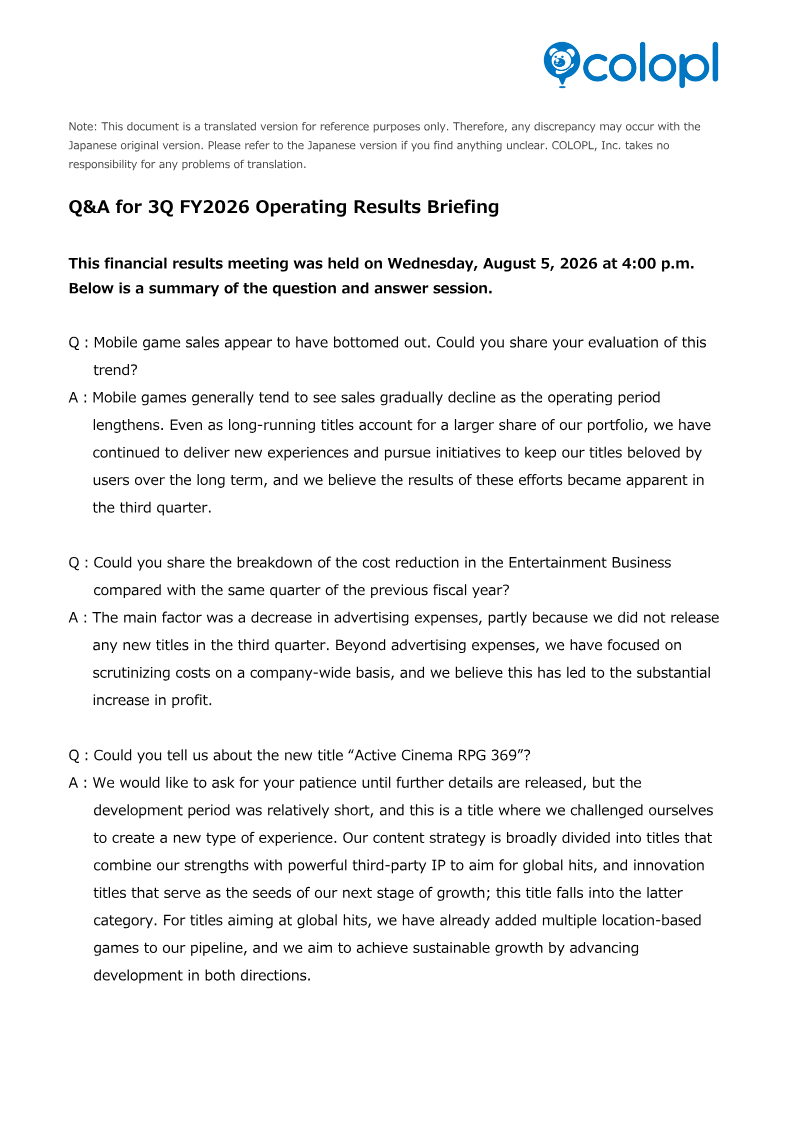
Q&A for 3Q FY2026 Operating Results Briefing
COLOPL’s third-quarter fiscal year 2026 performance reflects a strategic stabilization in mobile game revenue, signaling that long-running titles have successfully reached a performance floor. This trend is attributed to sustained efforts in user engagement and content longevity, which have mitigated the typical revenue decay associated with aging mobile portfolios. Profitability saw a substantial increase during this period, driven primarily by a disciplined reduction in advertising expenditures and a company-wide initiative to scrutinize operational costs. The absence of new title launches in the third quarter further contributed to this lean expenditure profile.
The company’s content strategy is bifurcated into two distinct pillars: leveraging third-party intellectual property for global market penetration and developing innovation-focused titles to serve as future growth catalysts. The upcoming Active Cinema RPG 369 represents the latter category, characterized by a condensed development cycle and an emphasis on experimental gameplay experiences. Simultaneously, the company is expanding its pipeline with multiple location-based games designed to secure sustainable, long-term growth.
Strategic expansion into the console market is also underway, marked by the announcement of Shironeko Project INFINITY. This project represents a departure from simple porting, as the company has invested in a bespoke development approach tailored to console hardware capabilities. Supported by an optimized personnel structure and advancements in development technology, the title is currently slated for a 2027 release. These initiatives collectively underscore a shift toward balancing the maintenance of established mobile assets with targeted investments in new platforms and innovative gaming experiences.
- COLOPL achieved increased profitability in 3Q FY2026 by significantly reducing advertising expenditures and implementing company-wide operational cost controls.
- Mobile game revenue has stabilized as long-running titles reached a performance floor, effectively mitigating typical revenue decay through sustained user engagement.
- The company is developing 'Active Cinema RPG 369,' an experimental title utilizing a condensed development cycle to serve as a future growth catalyst.
- COLOPL is expanding its console presence with 'Shironeko Project INFINITY,' a bespoke title built for console hardware rather than a simple port, scheduled for release in 2027.
- The current content strategy focuses on two pillars: leveraging third-party intellectual property for global reach and developing location-based games for long-term sustainability.
+2
COLOPL
Financial10 pages
Consolidated Financial Results for the Six Months Ended March 31, 2026: Japan
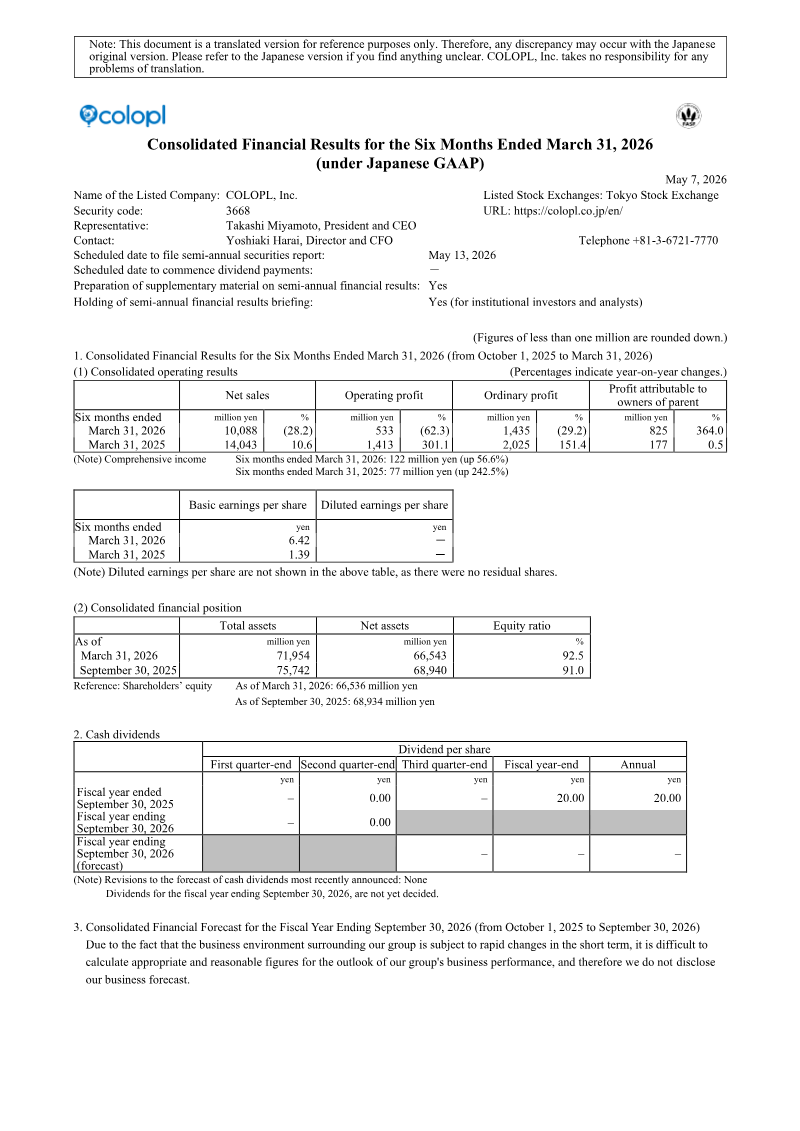
The consolidated financial results for the six months ended March 31, 2026, detail the performance of COLOPL, Inc. across its Entertainment and Investment and Development business segments. The company’s primary objective remains the enrichment of daily life through entertainment, balancing the operation of existing smartphone titles with new development and strategic investments in IT and entertainment sectors.
Financial performance for the period shows a contraction in top-line growth, with net sales reaching 10,088 million yen, a 28.2% decrease compared to the same period in the previous fiscal year. Operating profit also declined by 62.3% to 533 million yen. The Entertainment segment, driven by titles such as Dragon Quest Walk, saw net sales of 9,820 million yen, reflecting a decline in revenue from older titles despite efforts to maintain user engagement. The Investment and Development segment experienced a significant downturn, recording an operating loss of 123 million yen, largely due to a reduction in income from the sale of operational investment securities compared to the prior year and the recognition of impairment losses. Conversely, profit attributable to owners of the parent rose significantly to 825 million yen, a 364.0% increase, bolstered by lower extraordinary losses compared to the previous year.
The company maintains a strong financial position with total assets of 71,954 million yen and an equity ratio of 92.5% as of March 31, 2026. Cash and cash equivalents stood at 43,300 million yen, reflecting a net decrease of 2,348 million yen, primarily attributed to dividend payments. Due to the volatility of the current business environment, the company has opted not to disclose consolidated earnings forecasts for the fiscal year ending September 30, 2026, citing the difficulty in calculating reasonable projections.
- COLOPL, Inc. reported a 28.2% year-over-year decrease in net sales to 10,088 million yen and a 62.3% decline in operating profit to 533 million yen for the six months ended March 31, 2026.
- Profit attributable to owners of the parent surged 364.0% to 825 million yen, primarily driven by a reduction in extraordinary losses compared to the previous fiscal period.
- The Entertainment segment, anchored by titles like Dragon Quest Walk, generated 9,820 million yen in net sales, reflecting a decline in revenue from the company's aging smartphone game portfolio.
- The Investment and Development segment recorded an operating loss of 123 million yen, impacted by lower income from the sale of investment securities and the recognition of impairment losses.
- The company maintains a robust balance sheet with total assets of 71,954 million yen, an equity ratio of 92.5%, and 43,300 million yen in cash and cash equivalents.
+1
COLOPL
Financial39 pages
2Q FY Sep. 2026 Financial Results Presentation: Japan
COLOPL’s financial performance for the second quarter of fiscal year 2026 reflects a period of significant structural transition and contraction. Total sales reached 5.3 billion yen, representing a 39.1% year-over-year decline, while operating profit fell by 71.1% to 0.6 billion yen. This downturn is primarily attributed to a strategic exit from the Investment and Development segment. Despite these top-line challenges, the core Entertainment business demonstrated resilience, achieving a 49% increase in operating profit through disciplined cost management, specifically regarding advertising expenditures, and the sustained performance of flagship titles such as Dragon Quest Walk and Shironeko Project.
The company is currently navigating a shift toward a leaner operational model, evidenced by a reduction in total group headcount to 566 employees. This consolidation follows a period of historical volatility in profit margins, signaling a move away from previous peak performance levels toward a more stabilized, albeit smaller, footprint. Current profitability has recovered to an operating margin of 11.7%, providing a foundation for future initiatives.
Looking forward, the strategic focus centers on a "Global Top 20" objective, supported by a diversified pipeline that integrates AI-powered titles, location-based gaming, and high-profile intellectual property collaborations. Beyond traditional mobile gaming, the firm is actively diversifying its technological portfolio by investing in spatial computing, Web3, and XR applications. These efforts, alongside the upcoming August 2026 release of STEINS;GATE RE:BOOT, represent a concerted effort to pivot toward emerging digital markets while maintaining a commitment to ethical AI development and internal human capital management.
- COLOPL reported a 39.1% year-over-year decline in total sales to 5.3 billion yen and a 71.1% drop in operating profit to 0.6 billion yen for 2Q FY 2026.
- The core Entertainment business achieved a 49% increase in operating profit, driven by disciplined advertising cost management and the sustained performance of Dragon Quest Walk and Shironeko Project.
- The company’s significant financial contraction is primarily attributed to a strategic exit from its Investment and Development segment.
- Group headcount has been reduced to 566 employees as part of a transition toward a leaner operational model, resulting in a current operating margin of 11.7%.
- Future growth strategy focuses on a 'Global Top 20' objective, supported by a diversified pipeline including AI-powered titles, location-based gaming, and the August 2026 release of STEINS;GATE RE:BOOT.
+1
COLOPL

Financial30 pages
Financial Results Presentation: 2Q FY Sep. 2026
COLOPL’s financial results for the second quarter of the fiscal year ending September 30, 2026, reflect a period of transition characterized by a significant year-over-year decline in consolidated revenue, primarily driven by the absence of major investment exits that bolstered the prior-year period. For the quarter, the company reported consolidated sales of 5.3 billion yen, a 39.1% decrease year-over-year, and an operating profit of 0.6 billion yen, down 71.1%. Despite the top-line contraction, the Entertainment segment demonstrated resilience by achieving a 49% increase in operating profit to 0.7 billion yen, largely due to disciplined cost management and reduced advertising expenditures.
The Investment and Development business experienced a sharp decline, with sales falling 90.9% to 0.1 billion yen, reflecting the expected rebound from a major divestment recorded in the same quarter of the previous fiscal year. The segment reported an operating loss of 0.09 billion yen. However, the company maintains a robust financial position, reporting an equity ratio of 92.5% and an operational investment securities balance of 9.1 billion yen, supported by ongoing strategic investments in both domestic and international firms.
Looking ahead, the company remains committed to its mid-term "Global Top 20" strategy, which targets consolidated sales of 100 billion yen and operating profit of 50 billion yen. The content pipeline is focused on leveraging proprietary location-based gaming technology and powerful intellectual property to drive global growth. Recent milestones include the launch of "KAZUMA KANEKO'S TSUKUYOMI" and the upcoming August 2026 release of "STEINS;GATE RE:BOOT." Furthermore, the company is prioritizing the protection of creative assets through the launch of the "COLOPL Contents Protector" tool, aiming to foster a sustainable ecosystem for AI-integrated development.
- COLOPL reported a 39.1% year-over-year decline in consolidated sales to 5.3 billion yen and a 71.1% drop in operating profit to 0.6 billion yen for 2Q FY 2026.
- The Entertainment segment achieved a 49% increase in operating profit to 0.7 billion yen, driven by disciplined cost management and reduced advertising spend.
- The Investment and Development business saw sales plummet 90.9% to 0.1 billion yen, resulting in an operating loss of 0.09 billion yen due to the absence of major divestments seen in the prior year.
- Despite revenue contraction, the company maintains a strong balance sheet with a 92.5% equity ratio and 9.1 billion yen in operational investment securities.
- The company is pursuing a mid-term 'Global Top 20' strategy targeting 100 billion yen in consolidated sales and 50 billion yen in operating profit.
+1
COLOPL

Financial5 pages
Q&A for 2Q FY2026 Operating Results Briefing
The 2Q FY2026 operating results briefing outlines the strategic trajectory for COLOPL, Inc., emphasizing a transition toward long-term growth through the expansion of its location-based gaming portfolio and multi-platform development. The company’s primary thesis centers on leveraging its technical expertise in location-based mechanics to drive high user retention, while simultaneously diversifying its revenue streams beyond its current reliance on the title DRAGON QUEST WALK. Management aims to achieve a "Global Top 20" status by 2030, targeting 100 billion yen in consolidated sales and 50 billion yen in operating income.
Key operational findings indicate that while the company faces year-on-year revenue fluctuations due to the timing of large-scale collaboration events, the core retention rates for location-based titles remain robust. To support future growth, the company is investing in a new pipeline of location-based games that integrate powerful intellectual property, alongside expansion into console and VR/XR platforms. Furthermore, the company is actively integrating generative AI to streamline internal development processes and mitigate the impact of rising operational costs, reporting measurable gains in efficiency without compromising creative control.
The company’s broader business strategy includes a cautious approach to its Web3 and blockchain initiatives, which have faced headwinds due to regulatory uncertainty and market volatility. Moving forward, the firm intends to pivot its Web3 focus toward enhancing the value of existing digital assets while maintaining a diversified investment portfolio. By stabilizing its management foundations and focusing on high-margin, long-term operational models, the company expects to maintain its current scale over the next several years before realizing significant growth upon the release of its next generation of major titles.
- COLOPL aims to reach 'Global Top 20' status by 2030, targeting 100 billion yen in consolidated sales and 50 billion yen in operating income.
- The company is prioritizing a transition toward long-term growth by diversifying its revenue beyond its current reliance on the title DRAGON QUEST WALK.
- Strategic expansion efforts include developing a new pipeline of location-based games using powerful intellectual property, alongside growth in console and VR/XR platforms.
- COLOPL is integrating generative AI into internal development processes to improve operational efficiency and offset rising costs while maintaining creative control.
- Web3 and blockchain initiatives are being scaled back or pivoted toward enhancing existing digital asset value due to regulatory uncertainty and market volatility.
+1
COLOPL
Financial32 pages
Financial Results Presentation: 1Q FY Sep.2026
The presentation outlines COLOPL’s first‑quarter results for the fiscal year ending September 30, 2026, highlighting a mixed performance across its entertainment and investment segments. Consolidated sales reached 4.7 billion yen, down 10.2% year‑over‑year, while operating profit fell to a loss of 80 million yen, unchanged from the prior year. Ordinary profit surged 752% to 480 million yen, driven largely by foreign‑exchange gains and a reduction in advertising costs. Net profit improved to 170 million yen, reflecting a 279% increase despite extraordinary losses related to a career‑transition support program.
In the entertainment business, sales of 4.6 billion yen declined 10.6% YoY, yet operating loss narrowed to 50 million yen from a larger deficit the previous year. The investment and development arm recorded sales of 90 million yen, up 20% YoY, with operating loss improving to 32 million yen. Cash and deposits fell by 6% due to dividend payouts, but the equity ratio remained robust at 91.7%.
Geographically, COLOPL maintains a domestic focus while expanding overseas through new investments in Korean and Japanese firms and participation as a general partner in K‑Growth’s strategic fund. The company emphasizes location‑based gaming, AI‑powered titles, and XR initiatives such as the “360maps” navigation system. Strategic objectives target inclusion in the global mobile‑game top 20, with consolidated sales of 100 billion yen and operating profit of 50 billion yen as benchmarks. The presentation concludes with a call to leverage entertainment to inspire everyday life and references the recently released integrated report.
- COLOPL reported consolidated sales of 4.7 billion yen for 1Q FY2026, a 10.2% year-over-year decline, with an operating loss of 80 million yen.
- Net profit rose 279% to 170 million yen, while ordinary profit surged 752% to 480 million yen, primarily due to foreign-exchange gains and reduced advertising expenditures.
- The core entertainment segment generated 4.6 billion yen in sales—a 10.6% decline—though the segment's operating loss narrowed compared to the same period last year.
- Despite a 6% decrease in cash and deposits due to dividend payouts, the company maintains a strong financial position with an equity ratio of 91.7%.
- The investment and development arm saw a 20% year-over-year sales increase to 90 million yen, supported by new investments in Korean and Japanese firms and participation in the K-Growth strategic fund.
+1
COLOPL

Financial10 pages
Consolidated Financial Results for the Three Months Ended December 31, 2025: Japan
The quarterly consolidated financial results for the three months ended December 31, 2025 show a 10.2 % decline in net sales to ¥4,772 million compared with the same period a year earlier. Operating loss narrowed from ¥730 million to ¥86 million, while ordinary profit surged 752.4 % to ¥484 million due largely to foreign‑exchange gains and a gain on sale of investment securities. Profit attributable to owners of the parent rose 279.6 % to ¥170 million, and basic earnings per share increased from ¥0.35 to ¥1.32.
Total assets fell by ¥3,558 million to ¥72,183 million, driven mainly by a reduction in cash and deposits. Net assets declined to ¥66,215 million, with retained earnings reduced by ¥2,725 million after dividend payments. The equity ratio remained high at 91.7 %. No significant changes in consolidation scope or accounting policy were reported, and the company disclosed no retrospective restatements.
Segment analysis indicates that the Entertainment business generated ¥4,681 million in sales and incurred an operating loss of ¥54 million, while the Investment and Development business contributed ¥90 million in sales with an operating loss of ¥32 million. The company’s cash dividend policy for the fiscal year ending September 30, 2026 remains undecided.
Due to rapid changes in the business environment, the company refrained from providing a fiscal‑year forecast. The report covers Japan‑based operations under Japanese GAAP for the October–December 2025 quarter, with no significant geographic expansion or new industry segments noted.
- Net sales for the quarter ended December 31, 2025, declined 10.2% year-over-year to ¥4,772 million.
- Ordinary profit surged 752.4% to ¥484 million, primarily driven by foreign-exchange gains and the sale of investment securities.
- Operating losses narrowed significantly from ¥730 million in the previous year to ¥86 million for the current quarter.
- Profit attributable to owners of the parent rose 279.6% to ¥170 million, resulting in an increase in basic earnings per share from ¥0.35 to ¥1.32.
- The Entertainment segment generated ¥4,681 million in sales with an operating loss of ¥54 million, while the Investment and Development segment recorded ¥90 million in sales with a ¥32 million operating loss.
+1
COLOPL
Financial40 pages
1Q FY Sep. 2026 Financial Results Presentation
COLOPL’s financial performance for the first quarter of the fiscal year ending September 2026 reflects a strategic pivot toward profitability through rigorous cost management despite a shrinking core user base. While net sales declined 10.2% year-on-year to 4.7 billion yen, the company successfully reversed previous losses to achieve an ordinary profit of 0.4 billion yen. This recovery was primarily facilitated by aggressive reductions in advertising expenditures. The company maintains a highly stable financial foundation, characterized by a 91.7% equity ratio, providing the necessary capital to fund its transition from a mobile-centric developer to a multi-platform entertainment entity.
Operational data indicates significant headwinds in the mobile segment, with Quarterly Active Users dropping to 400,000 from a peak of 575,000 in 2022. This contraction is compounded by a long-term decline in Average Revenue Per User, which has fallen from 862 JPY to 680 JPY over the same period. To counter these trends, the growth strategy emphasizes expansion into the PC and console markets, highlighted by the upcoming April 2026 release of Kazuma Kaneko’s Tsukuyomi for the Nintendo Switch. Furthermore, investments in specialized game server services and location-based map distribution technologies aim to diversify revenue streams beyond traditional mobile gaming.
The long-term vision targets a "Global Top 20" market position with ambitious goals of 100 billion yen in sales and 50 billion yen in operating profit. Achieving these benchmarks relies on integrating cutting-edge technology, including AI-powered titles and XR experiences for next-generation mobility. By leveraging strategic investments in firms like CORE, Inc. and focusing on high-value intellectual property, the objective is to stabilize the current user contraction while building a sustainable pipeline of cross-platform content that can compete on a global scale.
- COLOPL returned to profitability in 1Q FY2026 with an ordinary profit of 0.4 billion yen, despite a 10.2% year-on-year decline in net sales to 4.7 billion yen.
- The company’s mobile segment is experiencing a significant contraction, with Quarterly Active Users falling to 400,000 from a 2022 peak of 575,000 and ARPU dropping from 862 JPY to 680 JPY.
- Profitability recovery was driven primarily by aggressive reductions in advertising expenditures, supported by a strong financial foundation with a 91.7% equity ratio.
- COLOPL is pivoting toward PC and console markets, with the upcoming April 2026 release of Kazuma Kaneko’s 'Tsukuyomi' for the Nintendo Switch serving as a key strategic milestone.
- Long-term growth objectives target a 'Global Top 20' market position, aiming for 100 billion yen in sales and 50 billion yen in operating profit.
+1
COLOPLFeb 2026
Financial2 pages
Q&A for 1Q FY2026 Operating Results Briefing
The first-quarter financial results for the fiscal year ending in 2026 reflect a strategic transition period for COLOPL, characterized by a lack of new releases and a focus on stabilizing existing mobile operations. Despite an anticipated decline in sales, the performance of established titles like Dragon Quest Walk and Alice Gear Aegis, alongside contributions from group companies, resulted in what leadership describes as solid progress. The company is currently navigating a challenging mobile market where the barrier to entry for new hits is rising, prompting a shift toward two primary development pillars: AI-powered titles and location-based games paired with globally recognized intellectual properties.
Financial performance in the first quarter was impacted by extraordinary losses related to special severance payments from a Career Transition Support Program. While headcount has decreased, the resulting reduction in personnel expenses is not expected to materialize until the second quarter of 2026. Regarding long-term operations for legacy titles such as Shironeko Project, the strategy emphasizes user satisfaction and game-balance adjustments over aggressive cost-cutting to ensure longevity.
The company is also diversifying its platform strategy beyond its core mobile business to include PC and console gaming. This is exemplified by the release of Kazuma Kaneko’s Tsukuyomi on Nintendo Switch, a title that originated as an exploration of generative AI in gaming. By establishing a new genre termed "Generative Games," the company aims to leverage AI-generated assets and systems across multiple hardware formats. Moving forward, the overarching goal remains achieving a "Global Top 20" position by integrating advanced technology with high-profile IPs and expanding the reach of its proprietary location-based gaming expertise.
- COLOPL is pivoting its development strategy toward two core pillars: AI-powered titles and location-based games utilizing globally recognized intellectual properties.
- The company is diversifying beyond mobile by expanding into PC and console gaming, exemplified by the release of 'Tsukuyomi' on Nintendo Switch.
- First-quarter fiscal year 2026 results were impacted by extraordinary losses from a Career Transition Support Program, with personnel cost savings expected to materialize in the second quarter.
- Legacy titles like 'Dragon Quest Walk', 'Alice Gear Aegis', and 'Shironeko Project' remain the primary revenue drivers, with the company prioritizing user satisfaction and game balance over cost-cutting for these assets.
- COLOPL is pioneering a new 'Generative Games' category that leverages AI-generated assets and systems across multiple hardware platforms.
+2
COLOPLFeb 2026